Equities Sector Analysis: Quick Overview
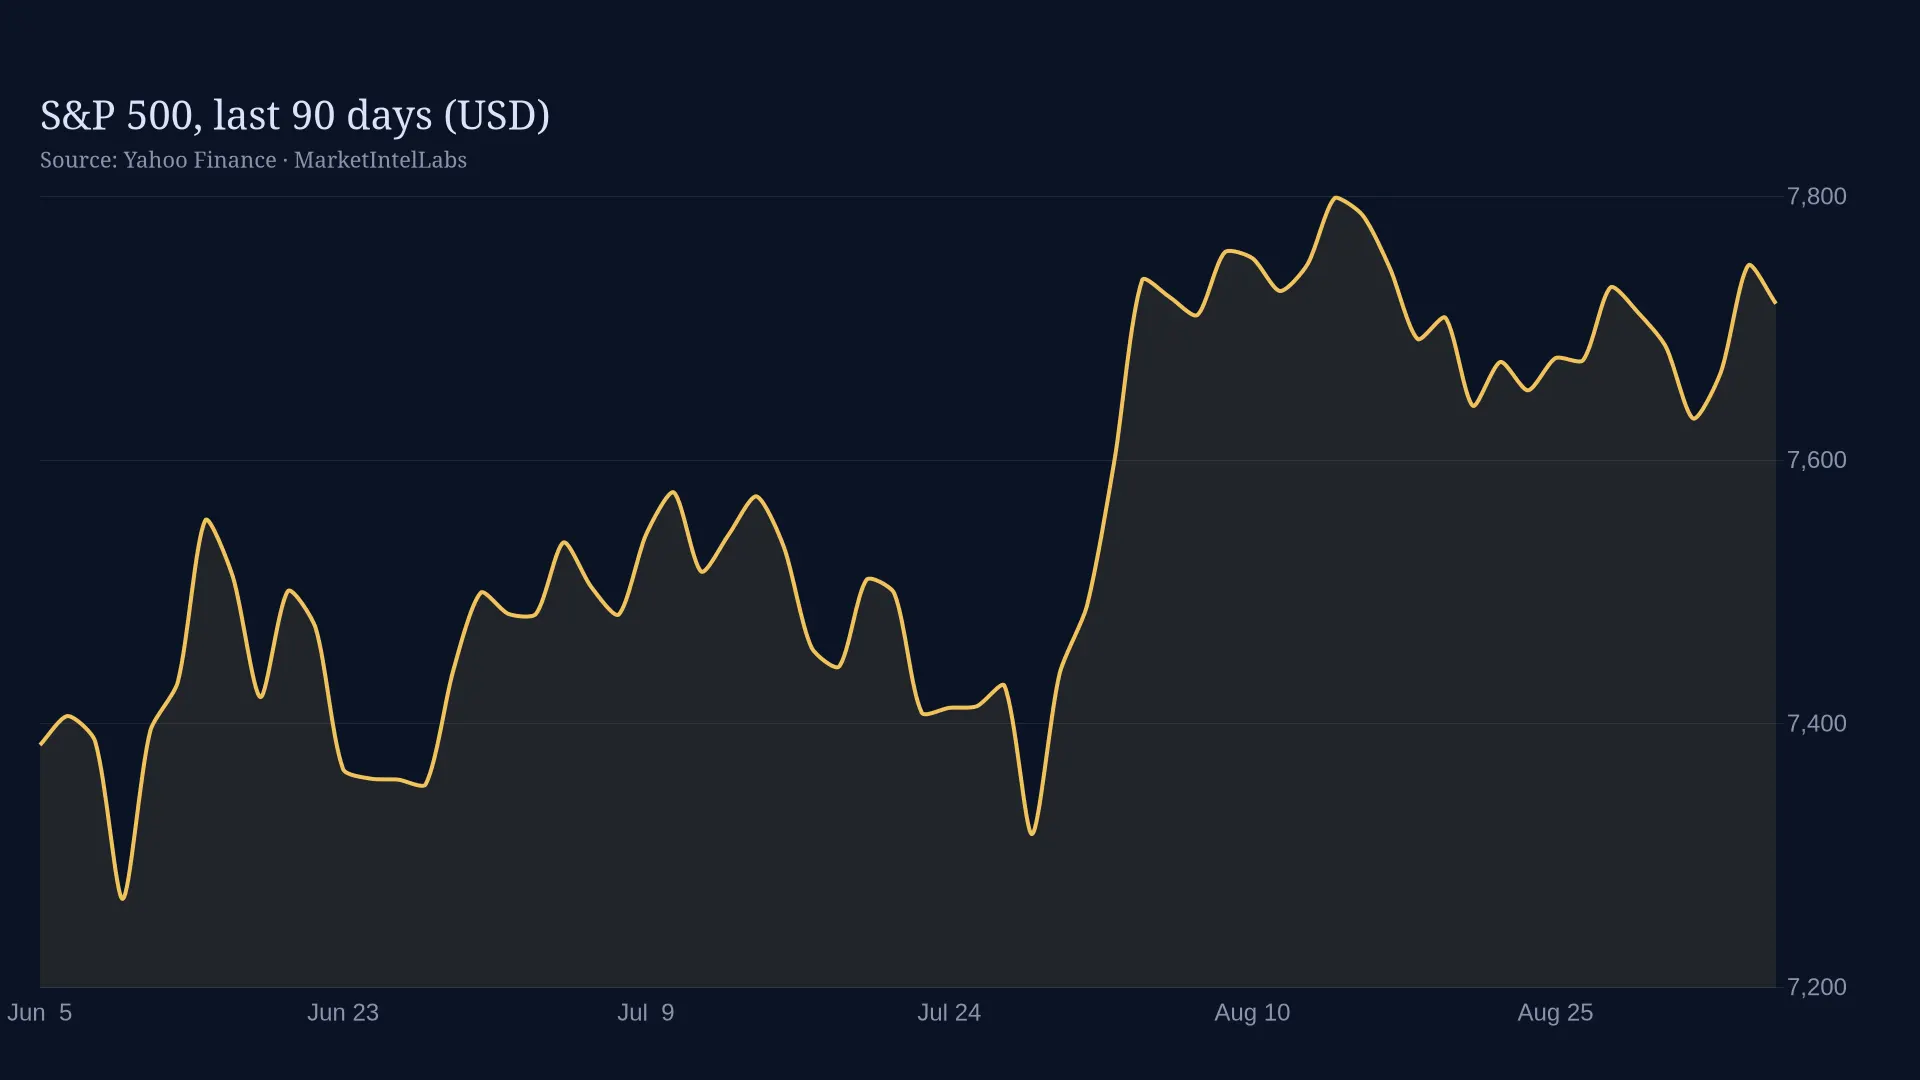
Technology and Industrials lead while Consumer Discretionary lags, signaling defensive positioning within a still-bullish tape. Small-cap outperformance suggests broadening participation beyond mega-caps.
Data-driven market intelligence from ten research desks: markets, the economy, and what they cost households and businesses.

Technology and Industrials lead while Consumer Discretionary lags, signaling defensive positioning within a still-bullish tape. Small-cap outperformance suggests broadening participation beyond mega-caps.

Executive Summary Equity markets are experiencing a classic rotation within an ongoing uptrend, with investors selectively rewarding growth while punishing more cyclical areas. The S&P 500 (SPY, u...

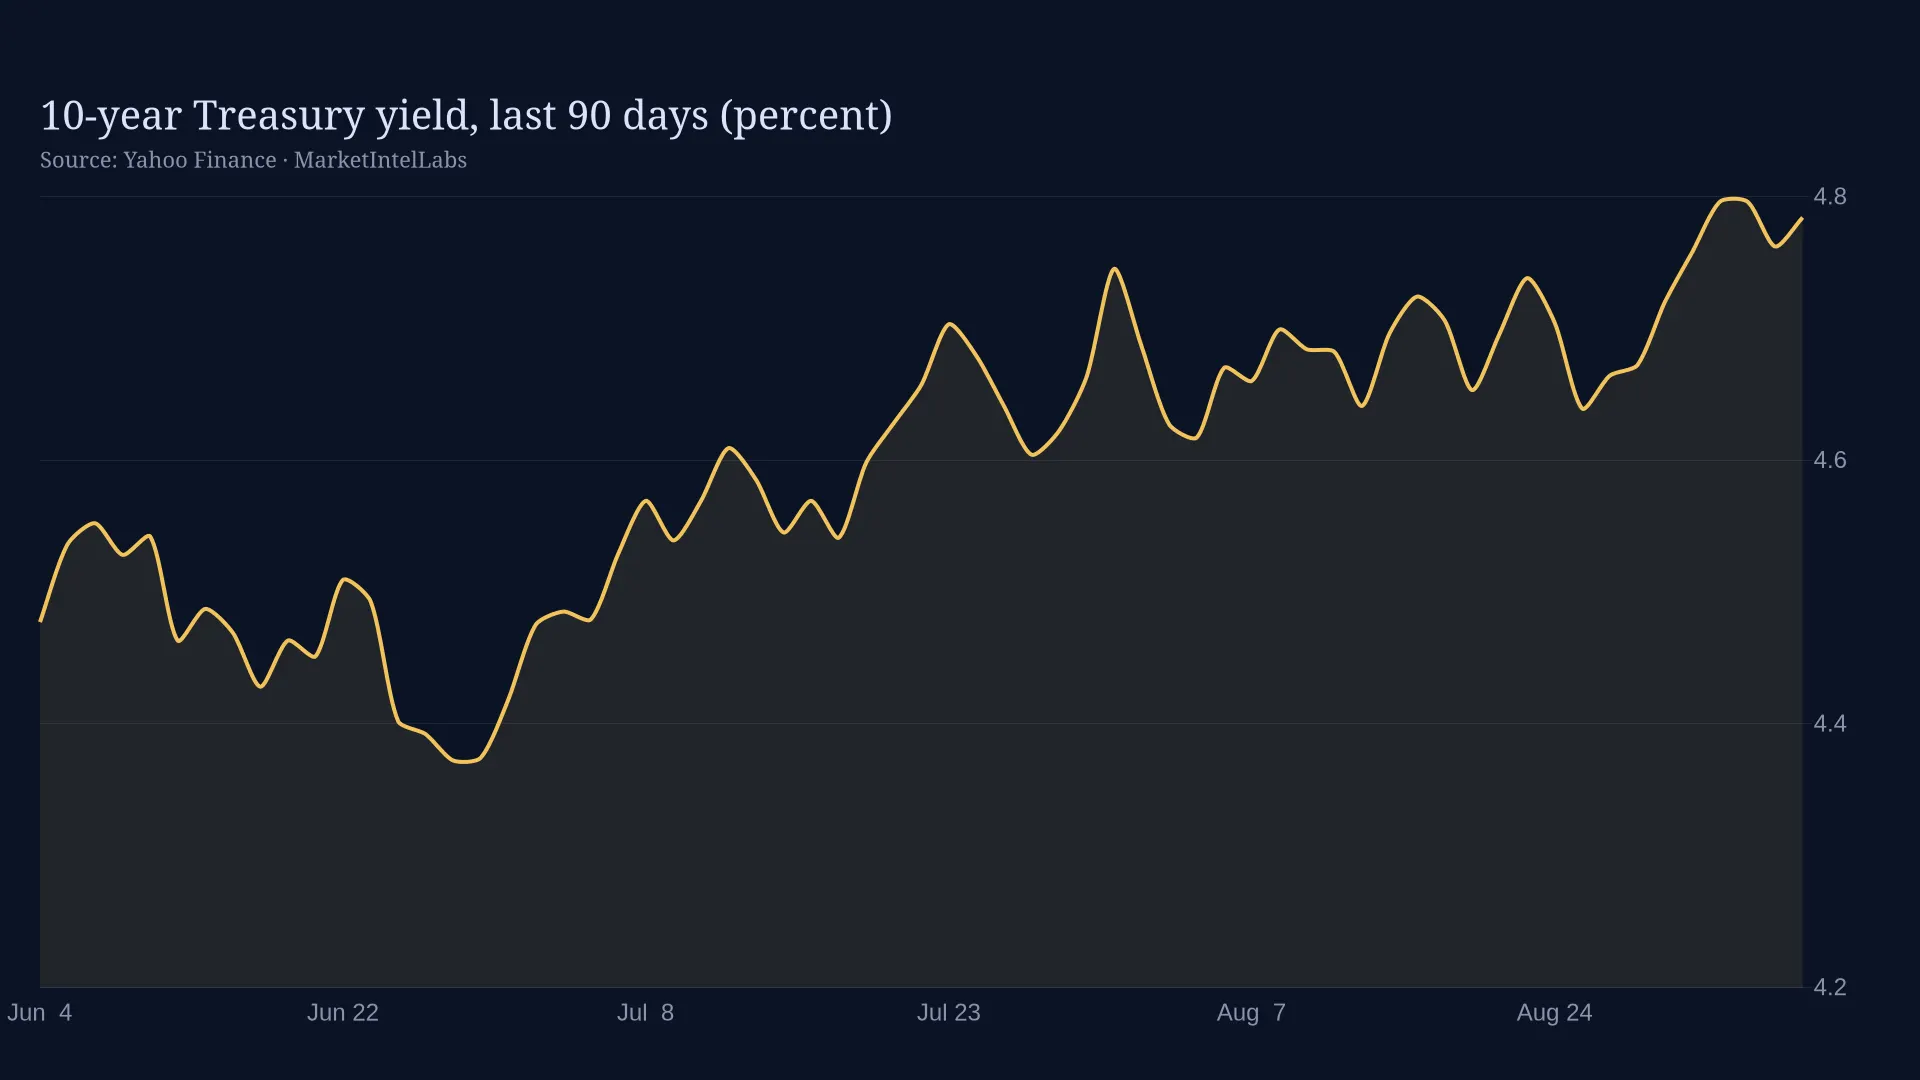
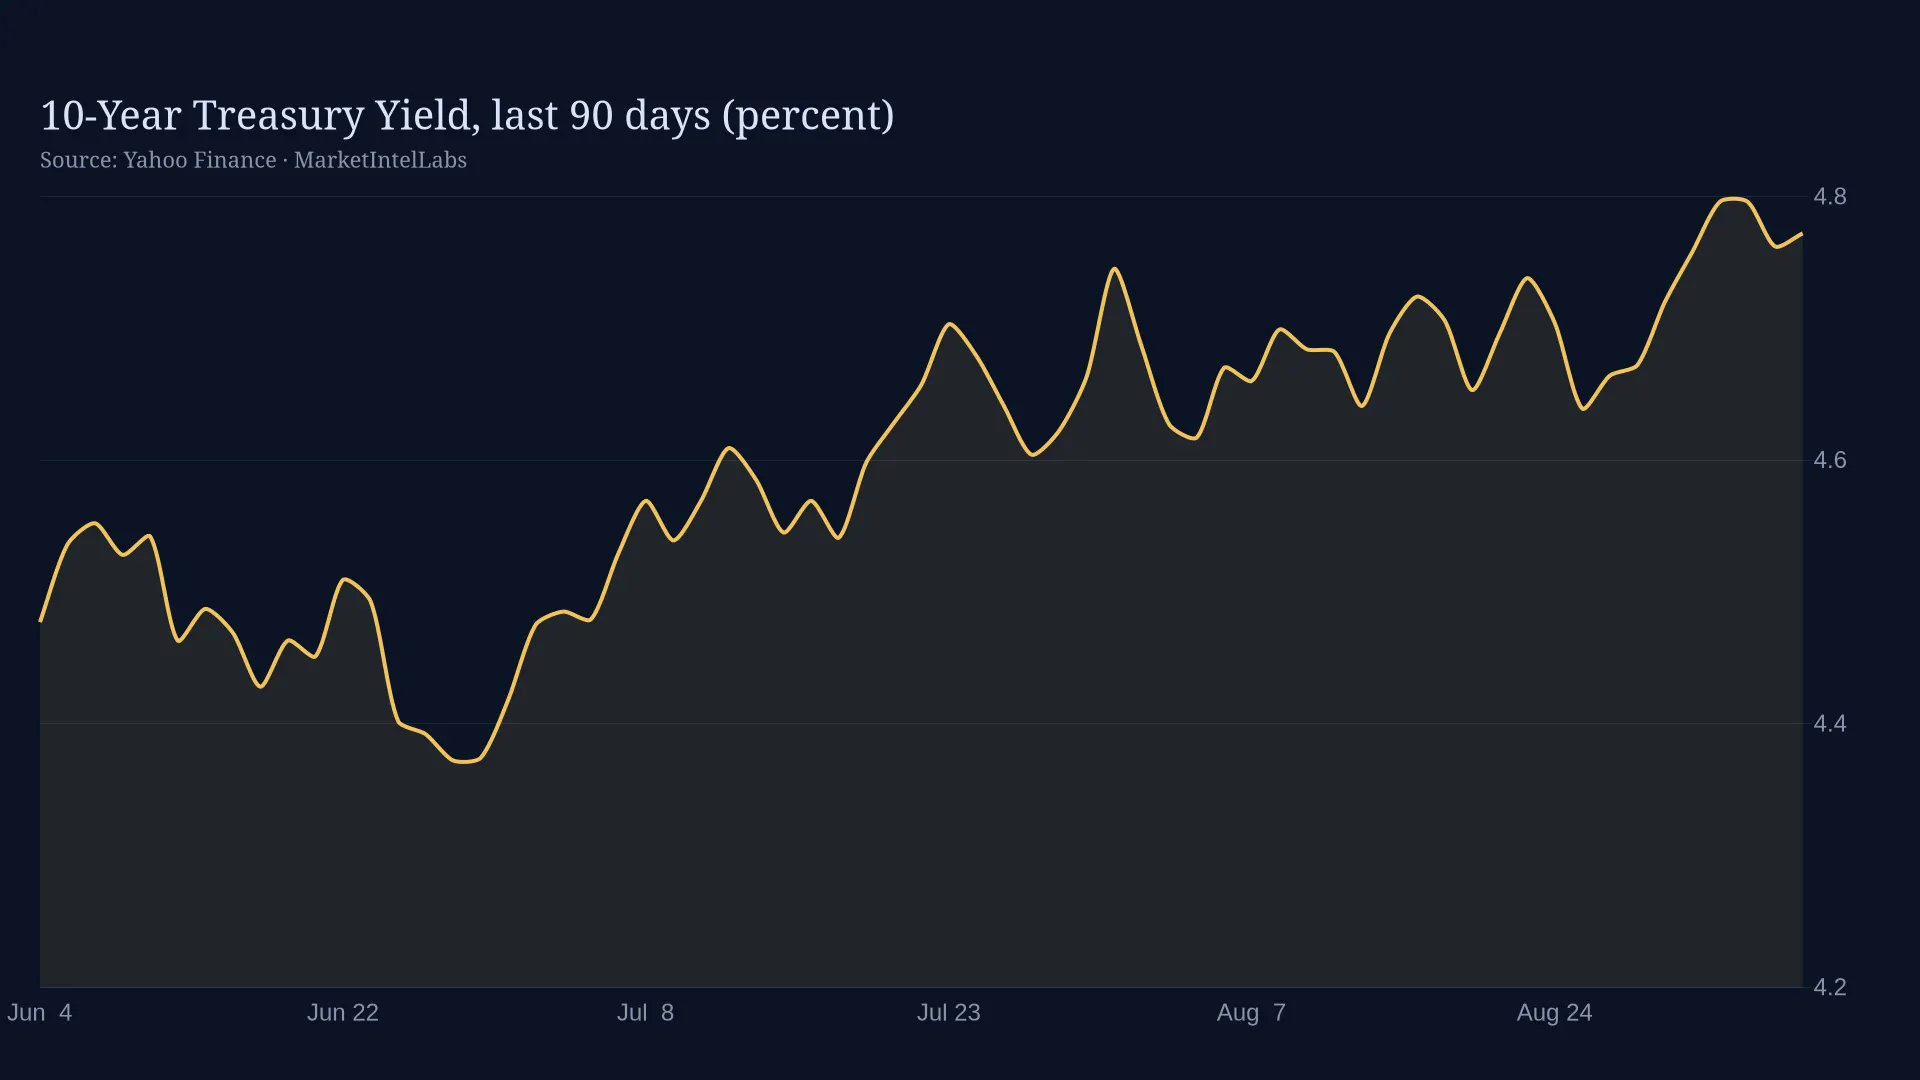
August jobs data and rising 10-year yields point to continued Fed tightening. We analyze the macro signals for September policy.

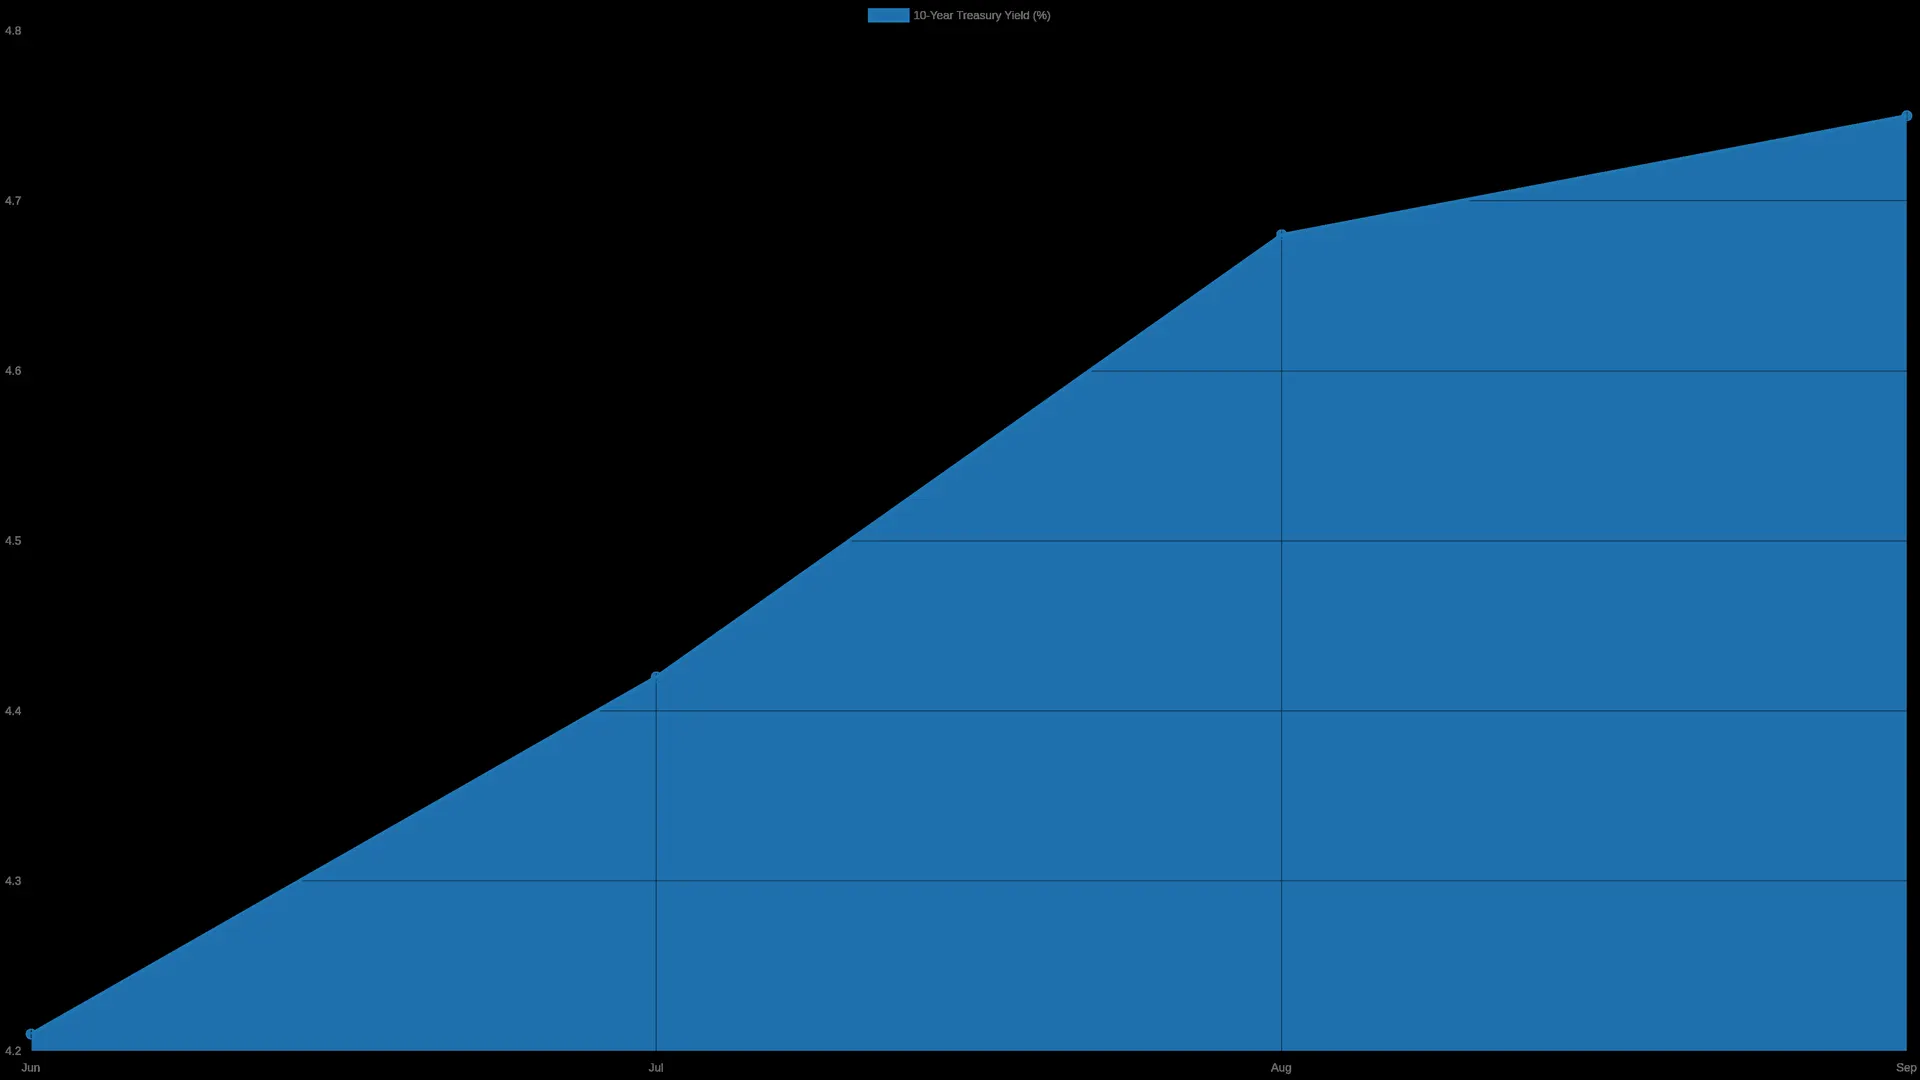
The 10-year Treasury yield climbed to 4.68% in August as markets priced in more Fed tightening. Here's how assets are reacting.

M2 growth and sticky inflation keep Fed tightening bias intact. Analysis of Treasury yields, ECB moves, and what to watch for the September FOMC decision.

On September 3, 2026, the Treasury Department's Office of Foreign Assets Control published a single recent-actions notice that did two structurally opposite things at once. It added five Cuban stat...

The September Employment Situation release showed a stronger-than-expected labor market, with nonfarm payrolls beating consensus and unemployment holding steady. Markets reacted with modest risk-off moves as wage growth accelerated, reinforcing the Fed's 'higher for longer' stance.

Hyperscaler spending collides with grid constraints as AI data center expansion faces physical bottlenecks in power transmission, water, and siting.

September jobs report showed 190k payrolls vs 180k expected, unemployment 3.8%, wage growth accelerated to 4.2% YoY. Markets priced in a 'higher for longer' Fed stance.

September payrolls added 190,000 jobs, beating expectations. Unemployment held at 3.8% while wage growth accelerated. What the data means for Fed policy and markets.

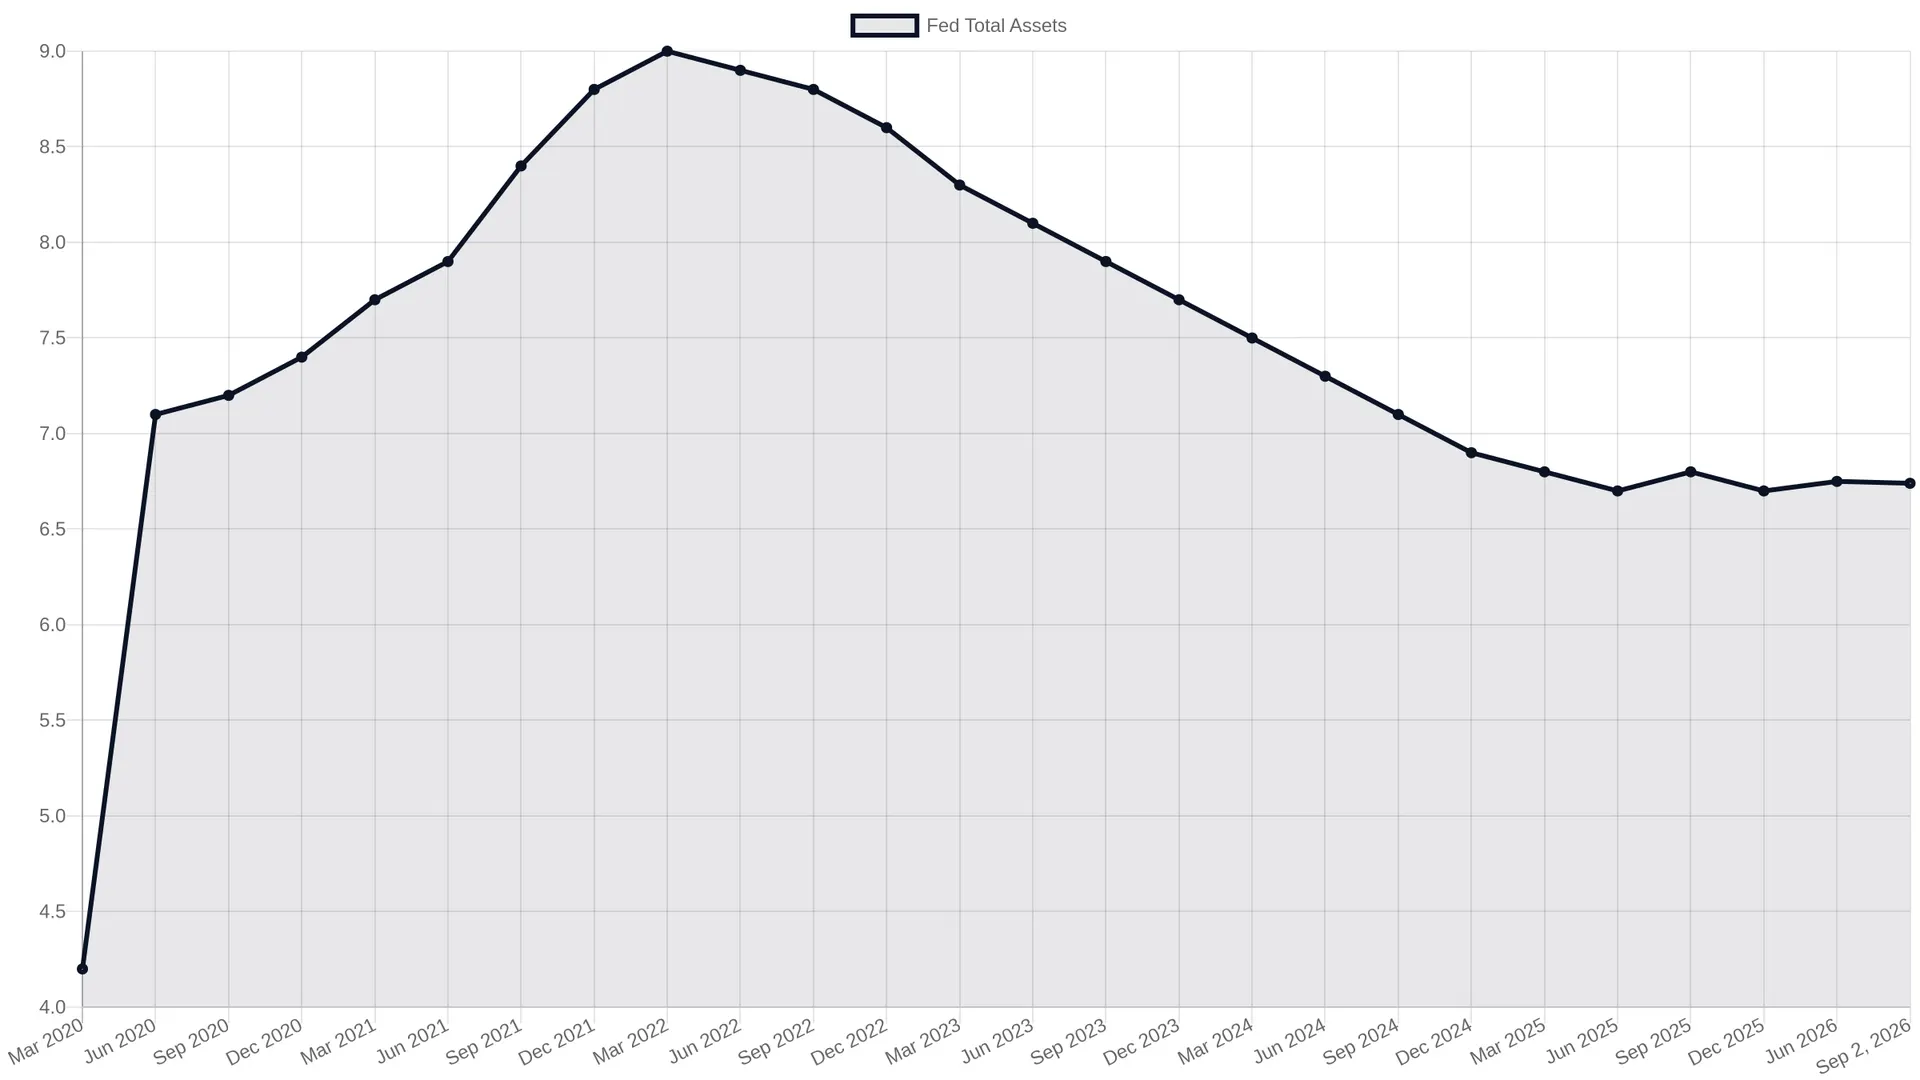
Fed balance sheet at $6.74 trillion as markets rally. SPY and QQQ gain over 1% while gold and silver surge. M2 growth moderates but remains positive.

Silver ETFs rose 2.5% Thursday as industrial demand strengthened, outperforming gold's 1.9% ETF gain despite futures weakness.