Week Ahead: Fed Minutes, Retail Earnings Set the Tone
The Fed's July minutes, four retailer earnings, and gold near key technical levels headline a data-light but decision-heavy week for markets.
Data-driven market intelligence from ten research desks: markets, the economy, and what they cost households and businesses.

The Fed's July minutes, four retailer earnings, and gold near key technical levels headline a data-light but decision-heavy week for markets.

Federal Reserve data show equipment investment climbing 31.6% year over year as Super Micro and Lumentum rally on capex-driven guidance beats, while Meta's stock fell 10% on capex growth that outpaced revenue.


July retail sales fell 0.6% to $763.6 billion and the control group missed consensus, the sharpest monthly slowdown in a year even as year-over-year spending held at 5.0%.

July CPI rose 3.30% y/y, below the 3.4% consensus. SPY and QQQ gained as Fed hike odds for September eased; GLD slipped on a firmer dollar.

Bitcoin holds near $63,300 as spot ETF flows swing to a four-session net outflow of $96.2 million, and Ethereum tracks BTC with no catalyst of its own this week.

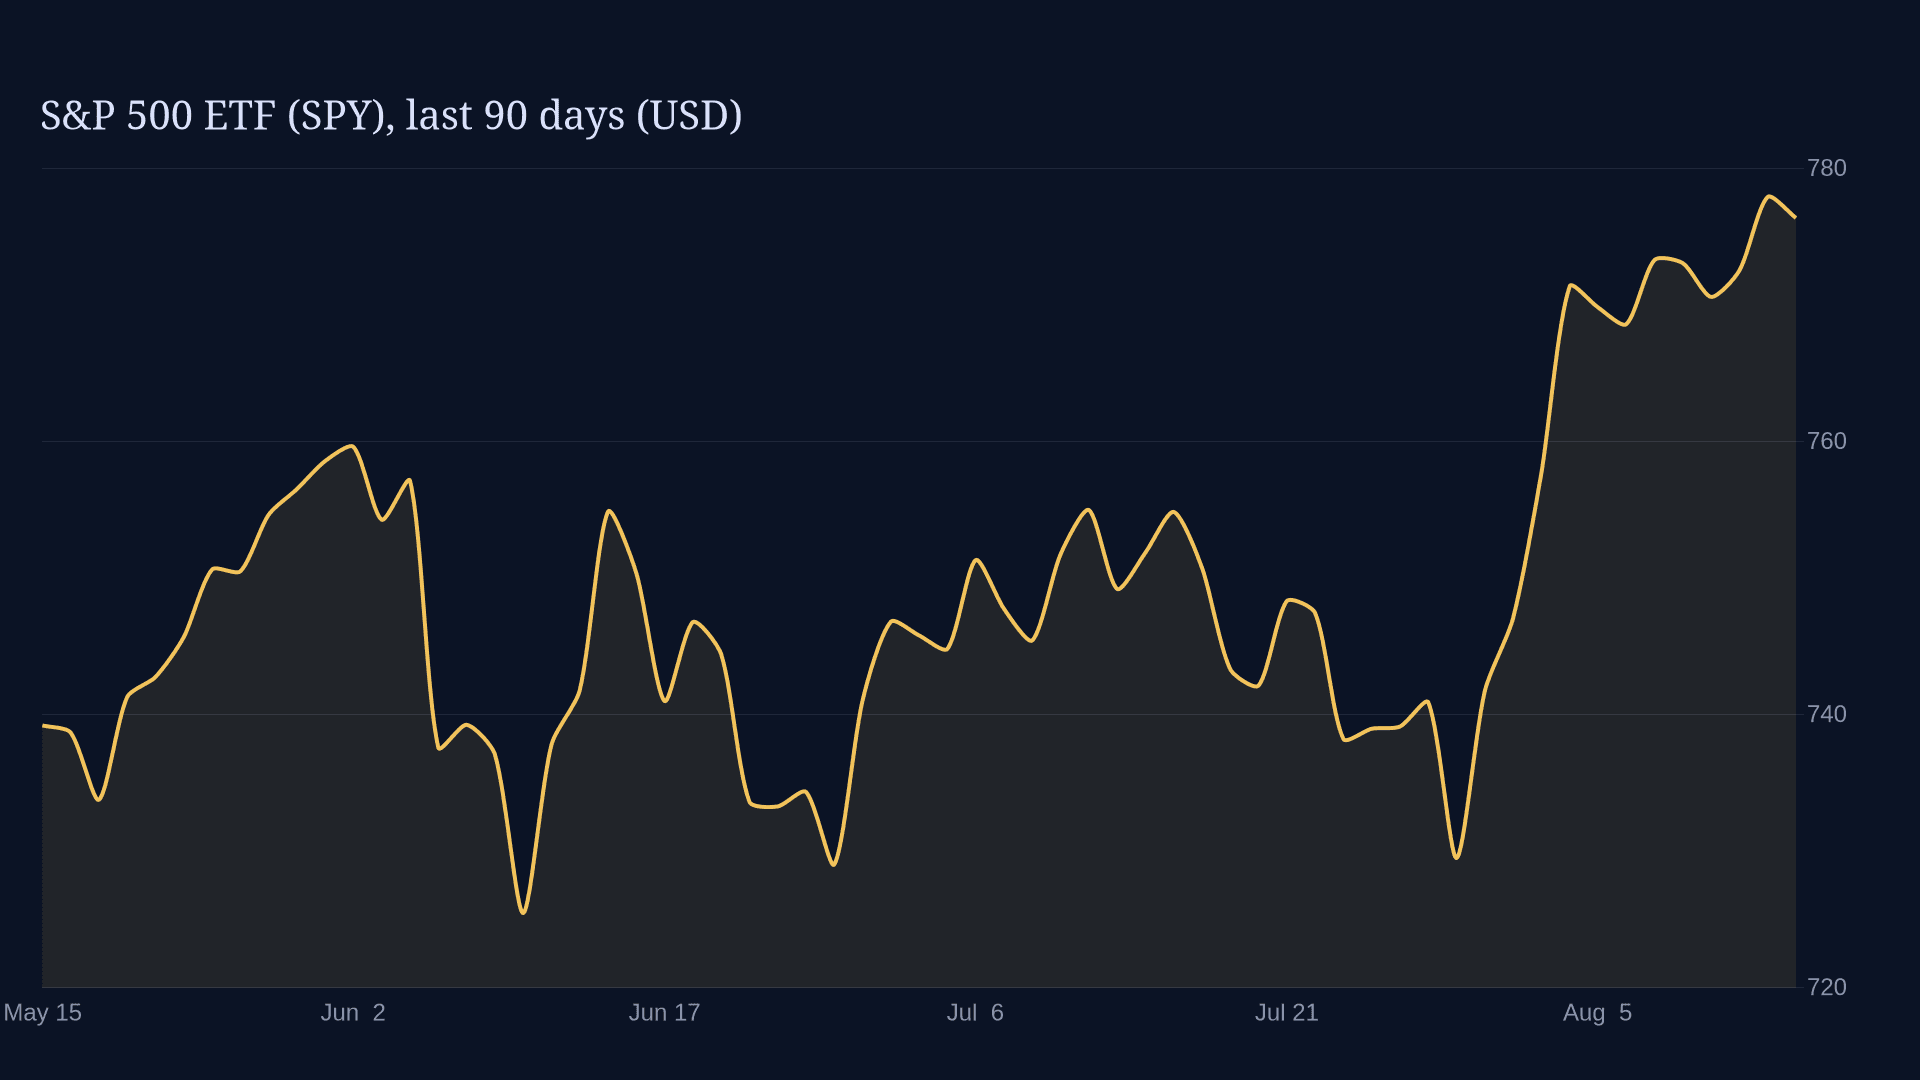
SPY and QQQ extended Thursday's record close into Friday trading, with the VIX near 14.6 and call-heavy options flow backing a tech and communication-services led tape.

Gold, silver, oil and copper all eased Friday as the dollar held near a one-week high, giving back part of Wednesday's CPI-driven rally.

July CPI and payrolls send conflicting signals into the September FOMC, but the sharper data point is plumbing: RRP near zero and M2 at 5.53% y/y.

US spot Bitcoin ETFs posted a net outflow of roughly $96.2 million over four sessions, reversing an early August inflow streak, as the SEC postponed its Reg Crypto meeting with no new date and Ethereum's DeFi TVL held structural leadership at $41.2 billion.

The S&P 500 hit a record 7,816.70 intraday on August 13 as tech (XLK +1.01%) and communication services (XLC +2.07%) led, backed by ~50% y/y Q2 earnings growth. But VIX at 14.63 and a call-heavy 0.59 put/call ratio leave the market with a thin hedging cushion, and today's Applied Materials report is the next test of the AI-capex thesis behind the rotation.

Record central-bank gold buying and a 21-month PBOC streak point to a structural floor even as CFTC data shows managed-money longs stretched after the CPI pop.