September Employment Situation: What It Means
September jobs report showed 190k payrolls vs 180k expected, unemployment 3.8%, wage growth accelerated to 4.2% YoY. Markets priced in a 'higher for longer' Fed stance.
Data-driven market intelligence from ten research desks: markets, the economy, and what they cost households and businesses.

September jobs report showed 190k payrolls vs 180k expected, unemployment 3.8%, wage growth accelerated to 4.2% YoY. Markets priced in a 'higher for longer' Fed stance.

September payrolls added 190,000 jobs, beating expectations. Unemployment held at 3.8% while wage growth accelerated. What the data means for Fed policy and markets.

This week's key economic indicators: ISM PMIs, jobless claims, and what the data means for markets amid Fed QT and modest M2 growth.

September jobs report preview: Consensus calls for 180,000 payrolls, 3.9% unemployment, and 0.3% wage growth. Here's what to watch and how markets might react.

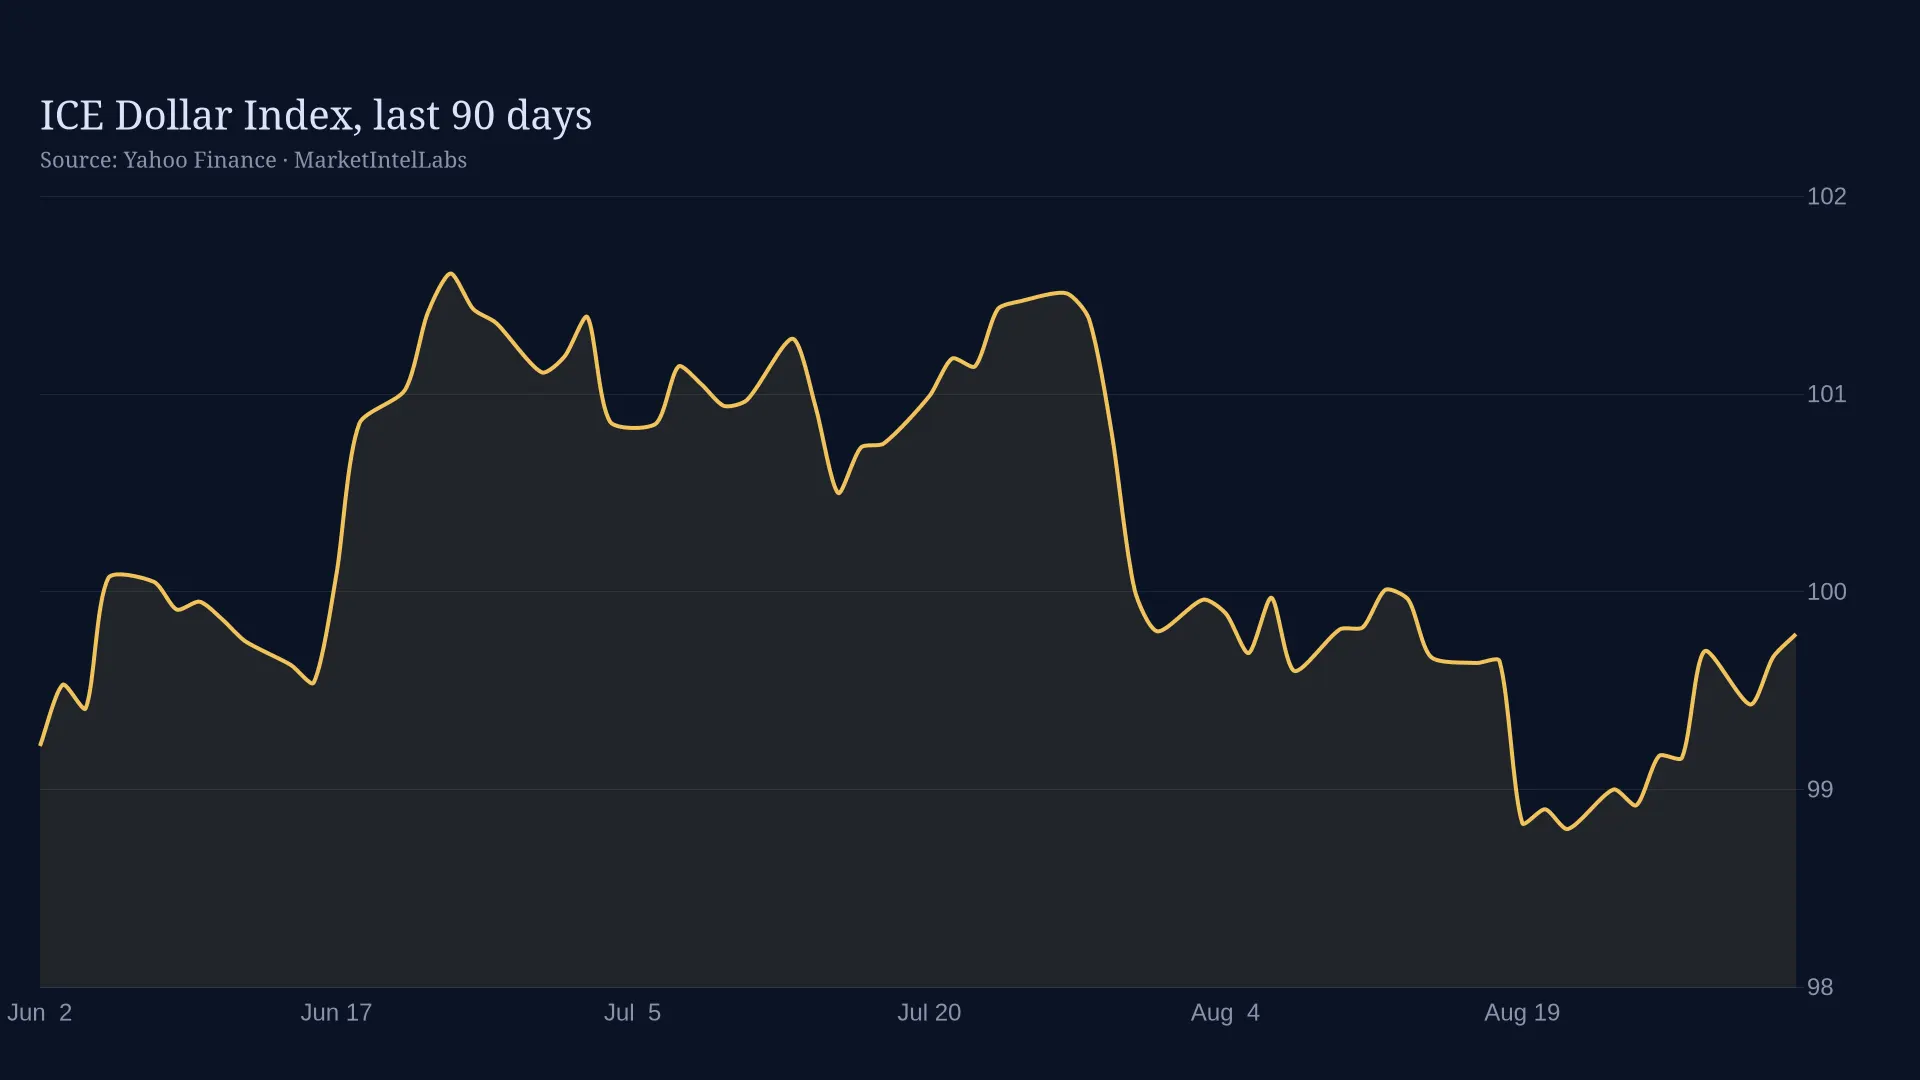
M2 money supply contracted 2.3% YoY while the dollar strengthened to 118.75, creating a liquidity squeeze that pressured equities, precious metals, and bonds in Wednesday's session.

July JOLTS job openings printed at 7.27 million, missing the 8.2 million consensus by 930,000. Combined with declining hires and quits, the data signals accelerating labor market weakness that strengthens the case for earlier Fed rate cuts.

Job openings fell to 7.3 million, missing the 8.2 million consensus. Hiring weakened and separations rose, signaling accelerating labor market deterioration.

JOLTS report shows job openings at 7.27M vs 8.2M expected, signaling labor market weakness and potentially earlier Fed rate cuts.

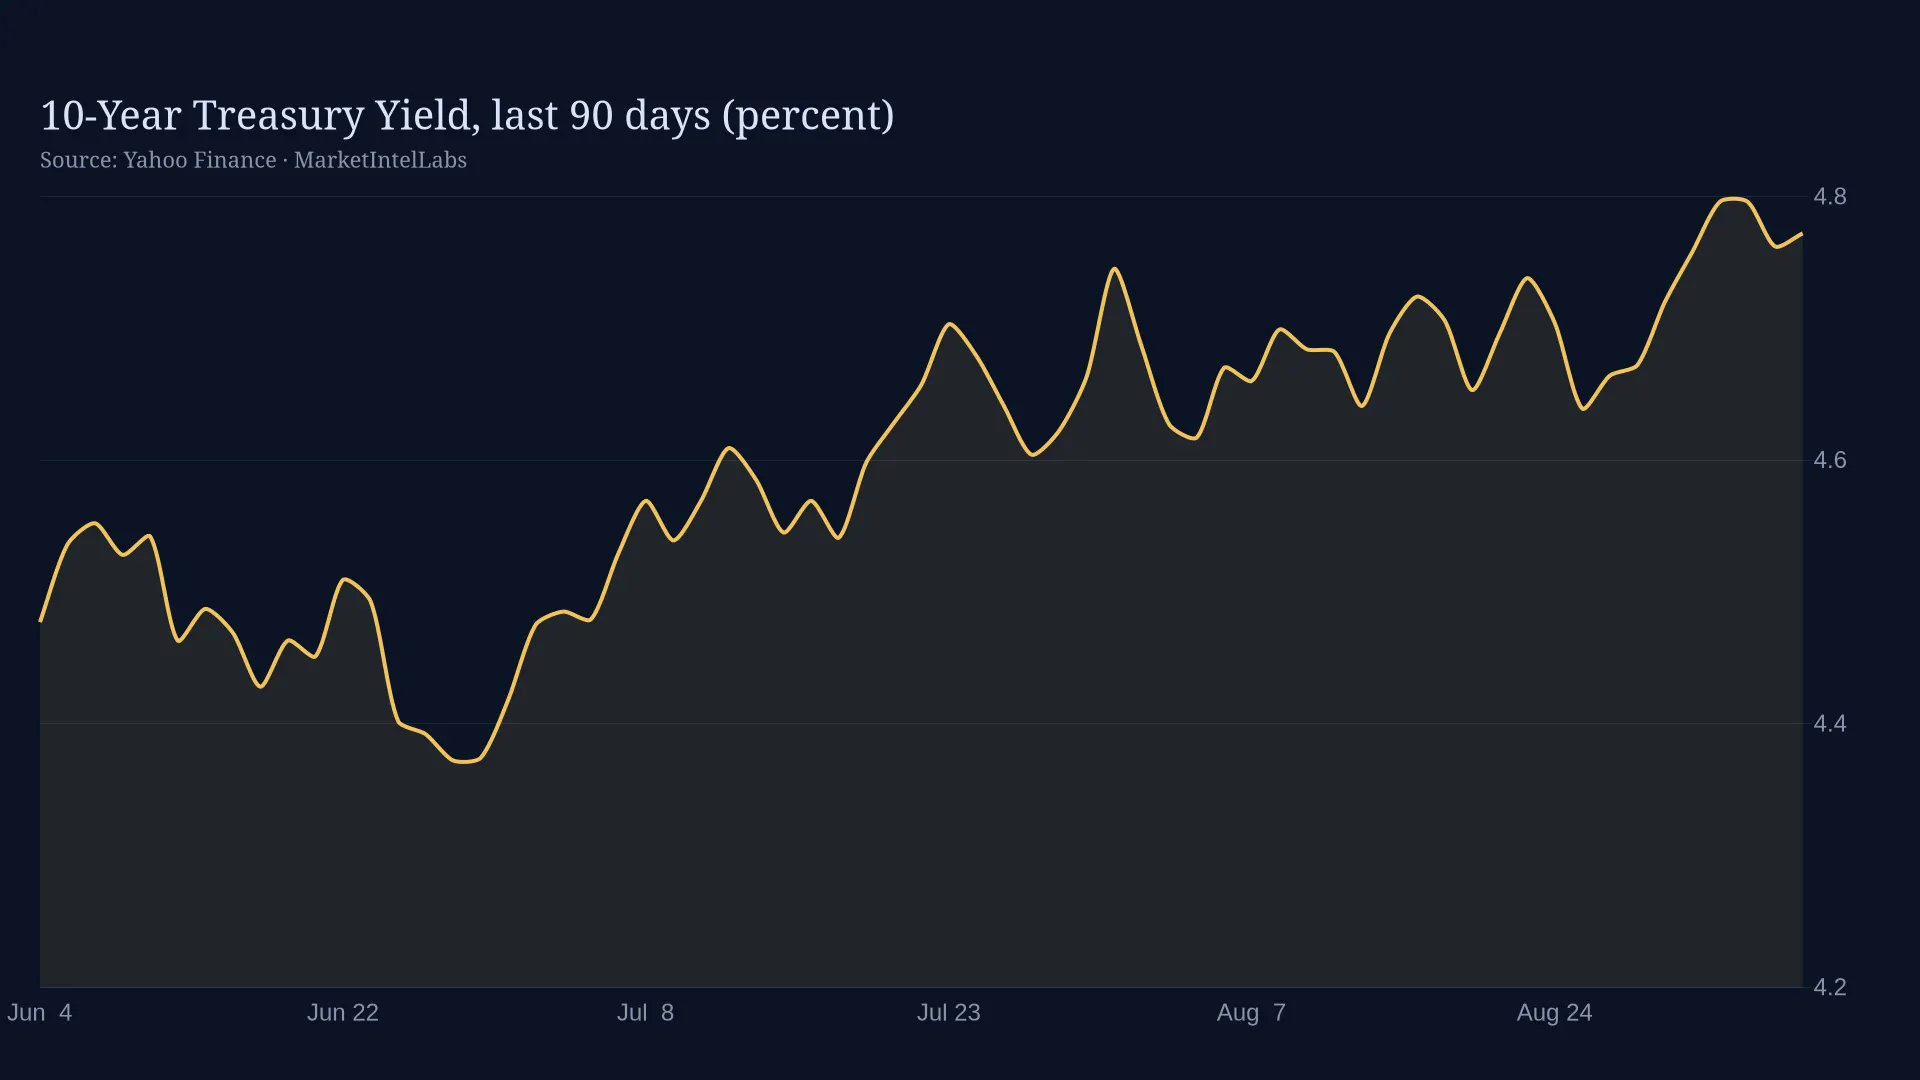
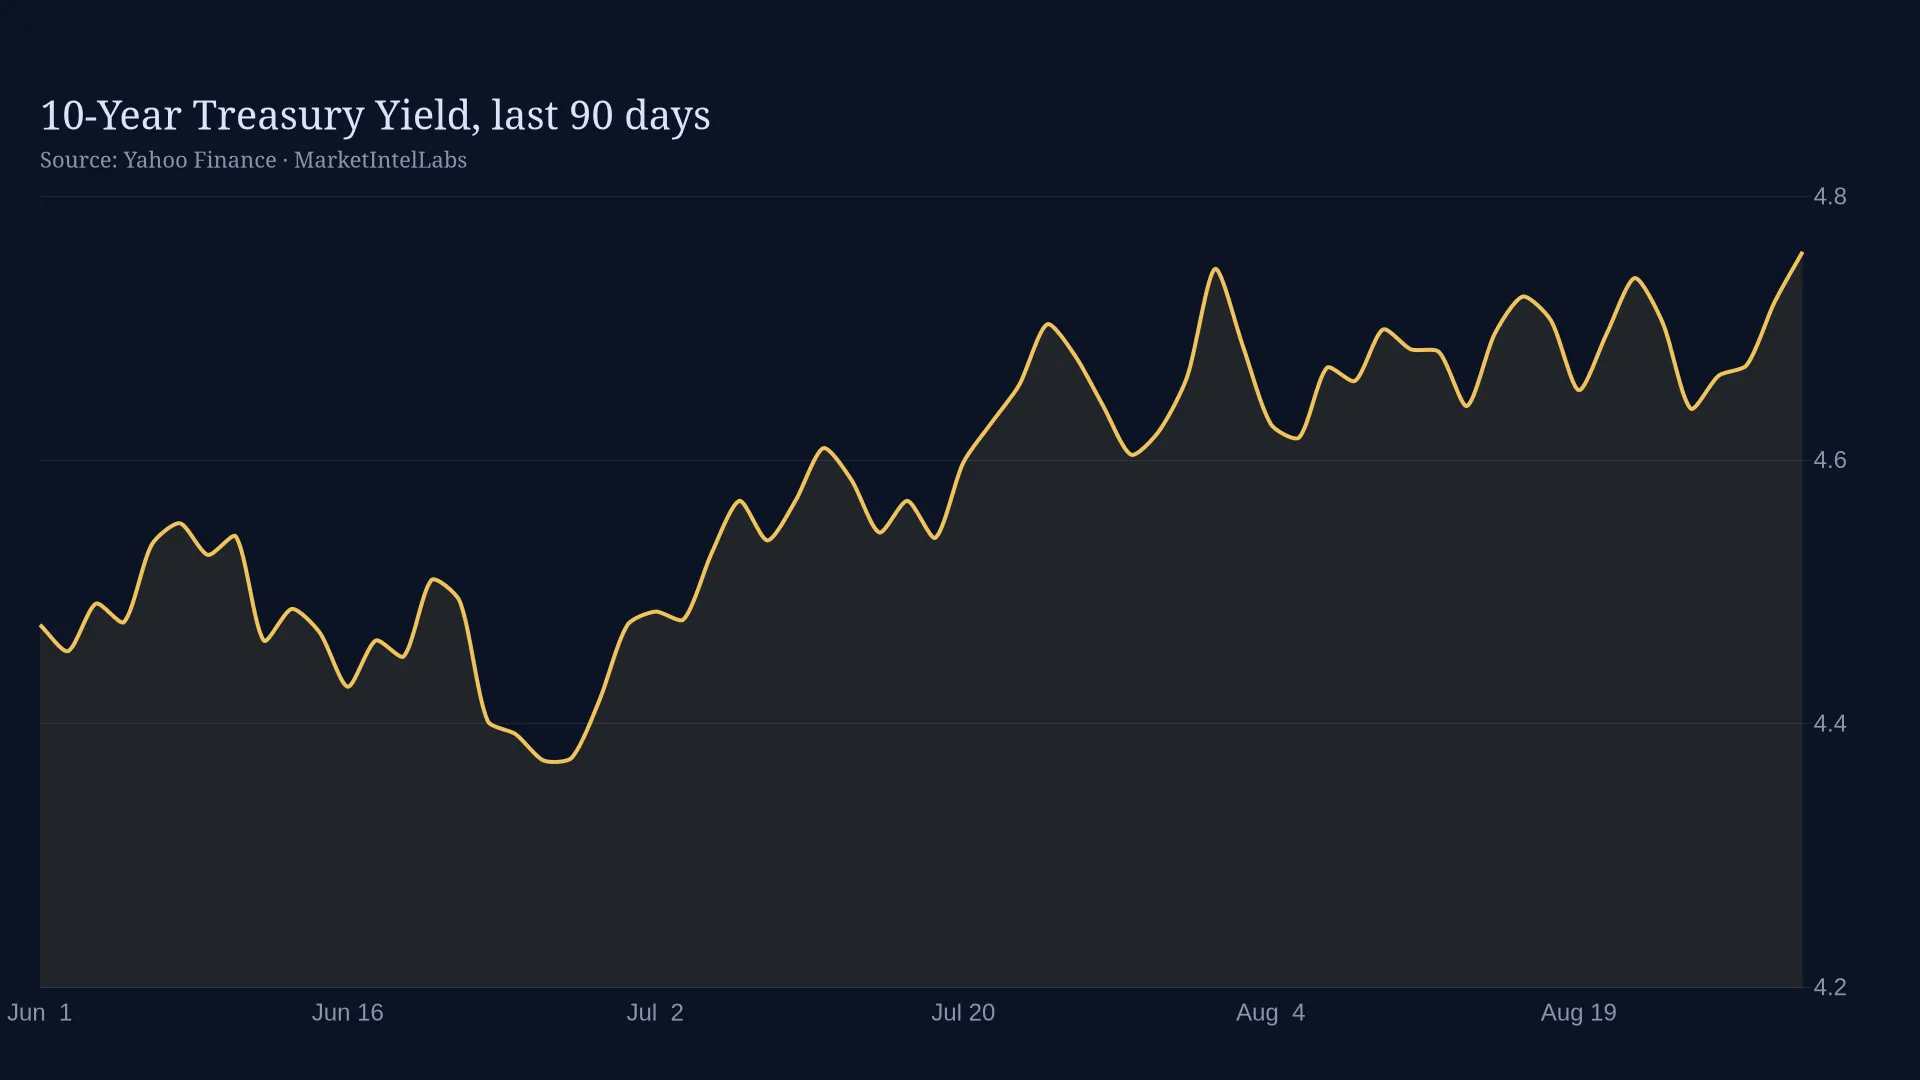
Treasury yields rise and the yield curve flattens to a 39 basis point spread. What the bond market is signaling about Fed policy and growth.

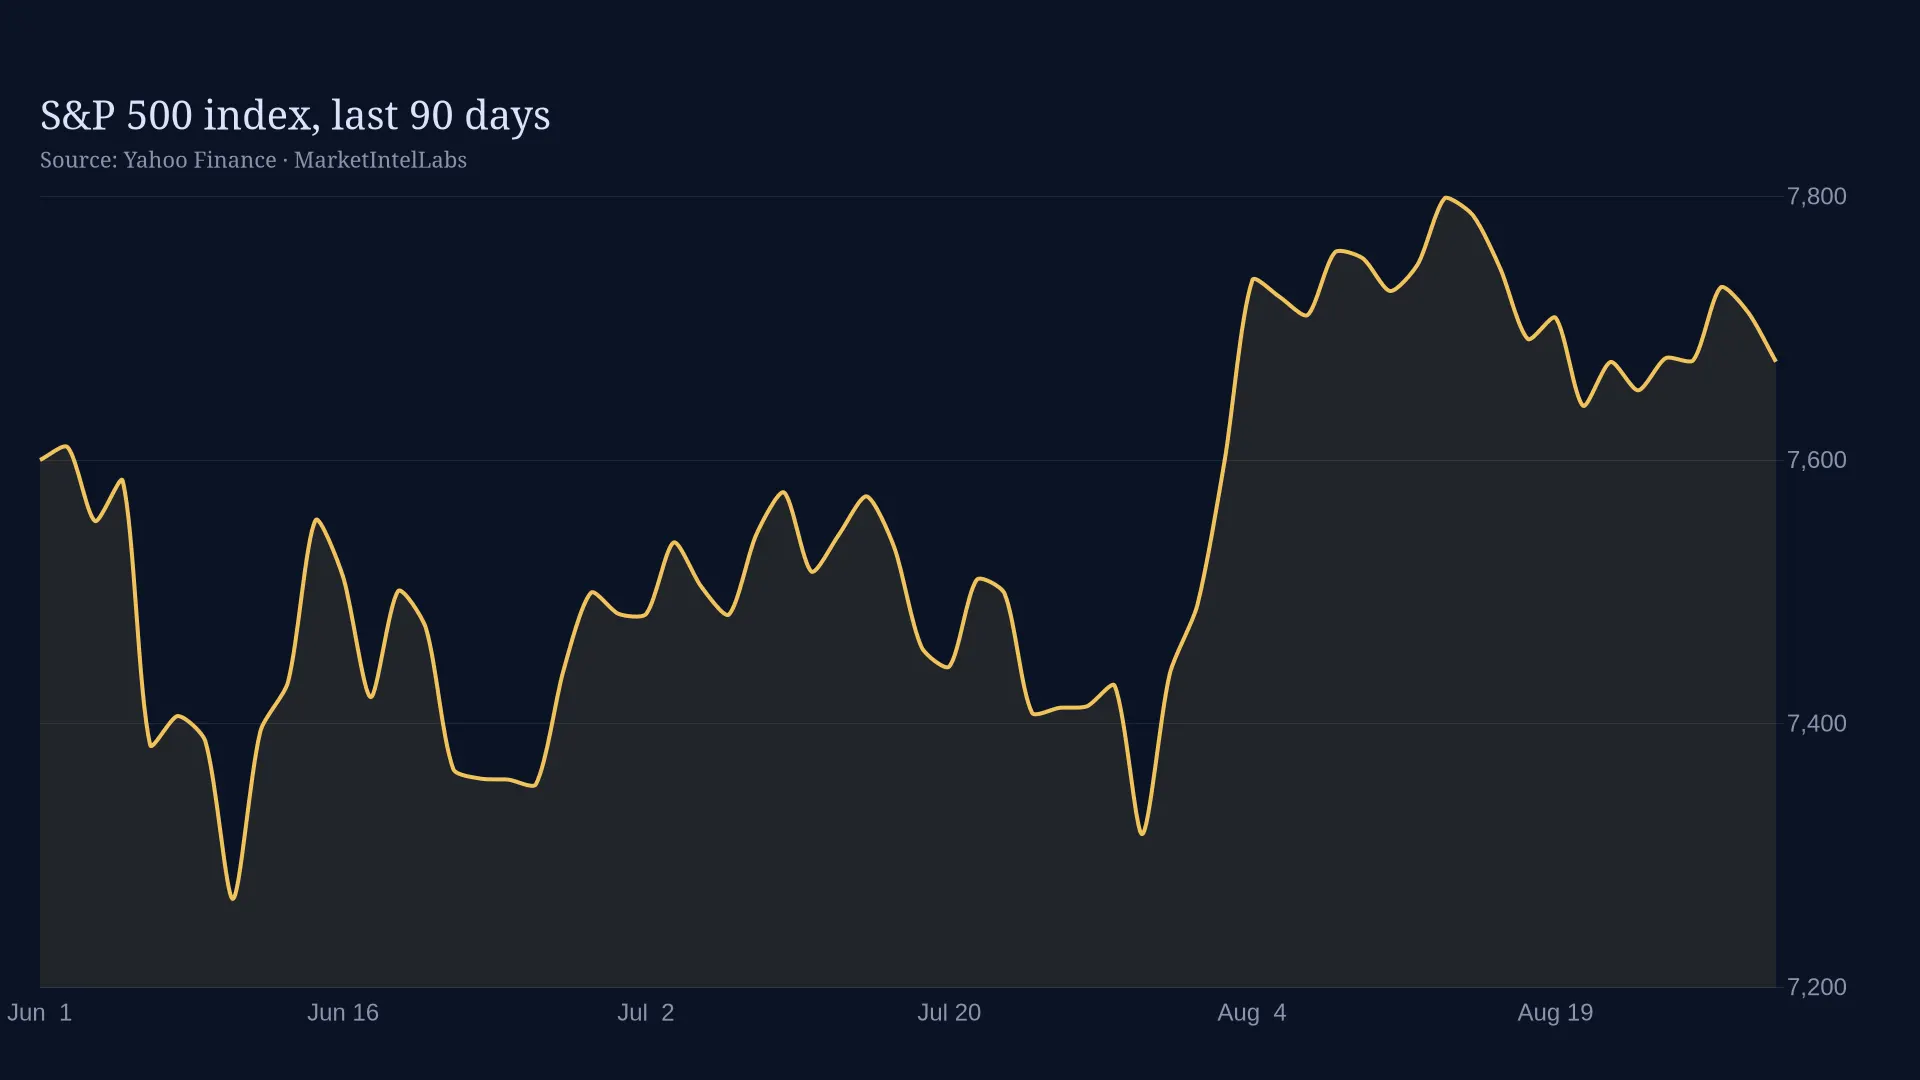
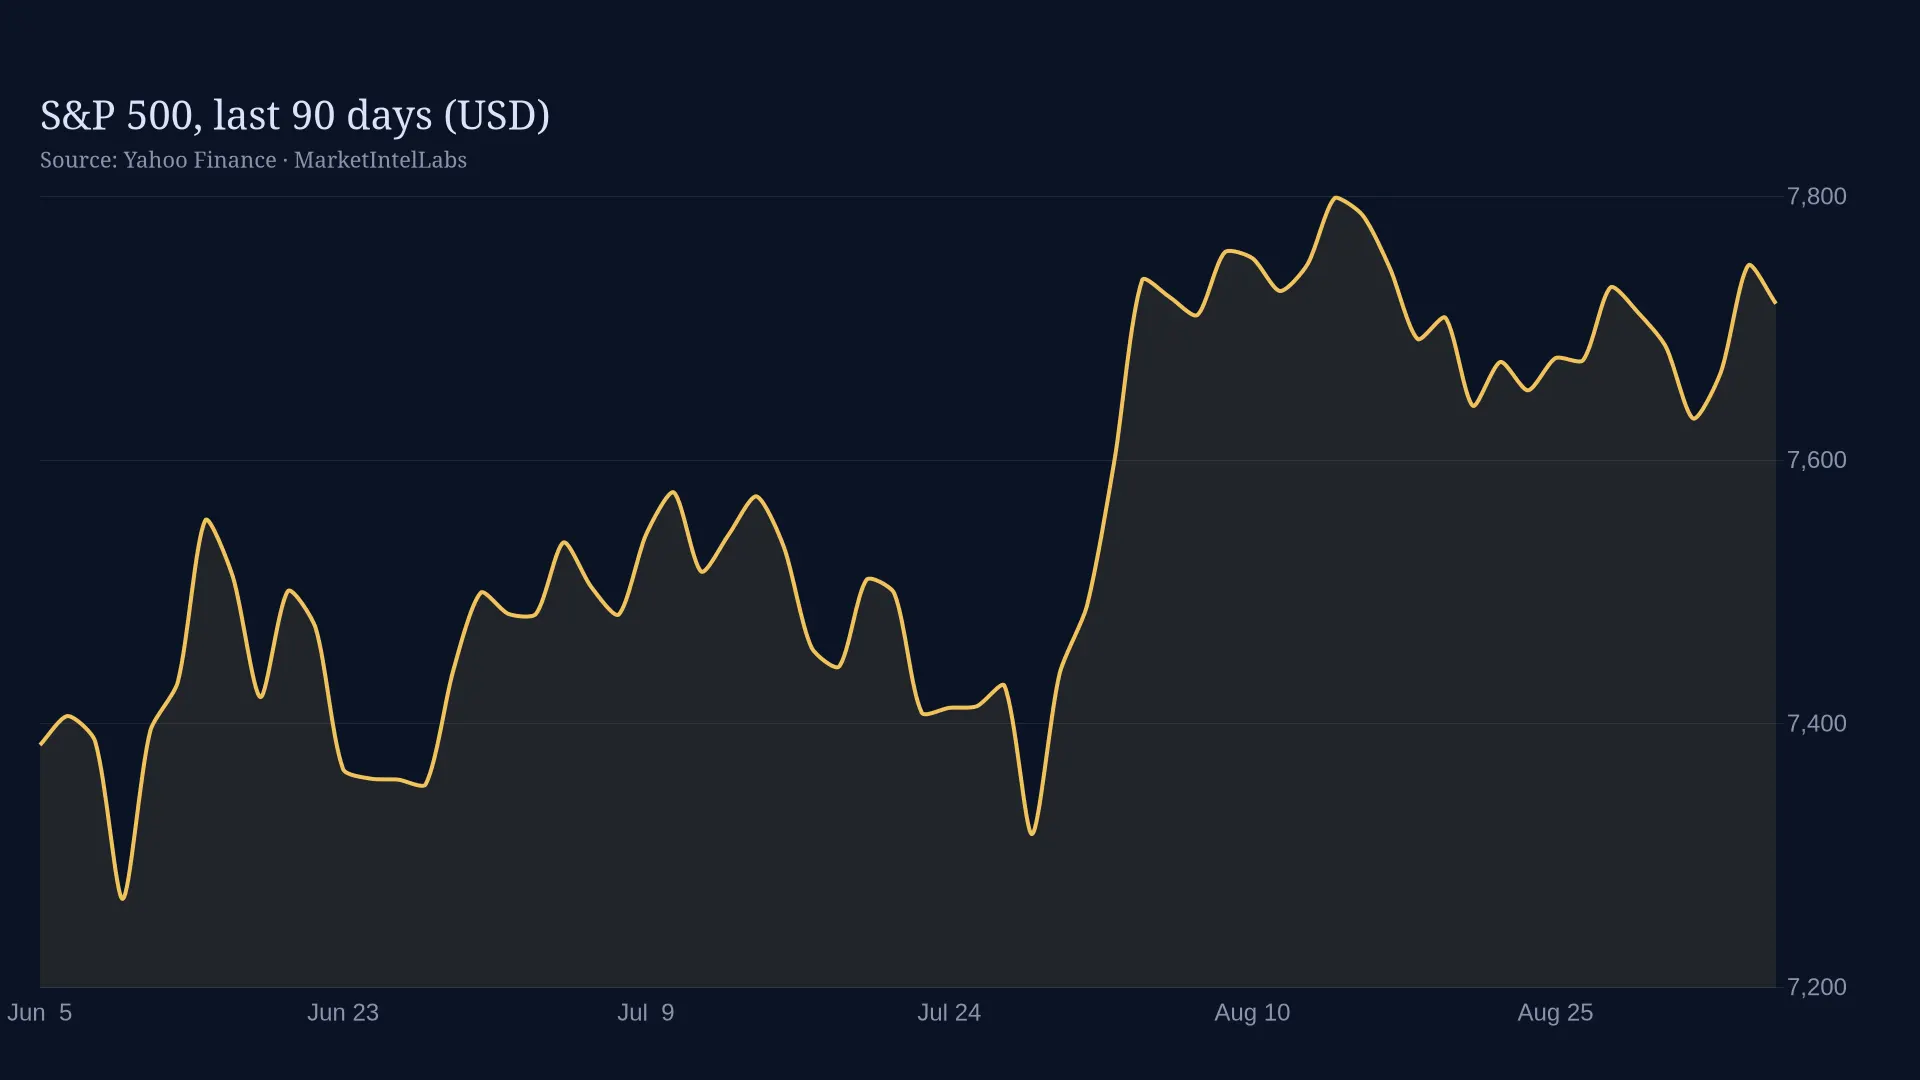
The S&P 500 and NASDAQ-100 are stuck in neutral as macro data signals a pause in the market's recent rally. Both indices closed essentially flat Monday with SPY down 0.23% to $769.35 and QQQ slipping 0.65% to $716.43.

July CPI rose just 0.07% month-over-month while unemployment dropped to 4.1%, pointing to contained price pressures and a resilient labor market. SPY and QQQ both rallied on the data.

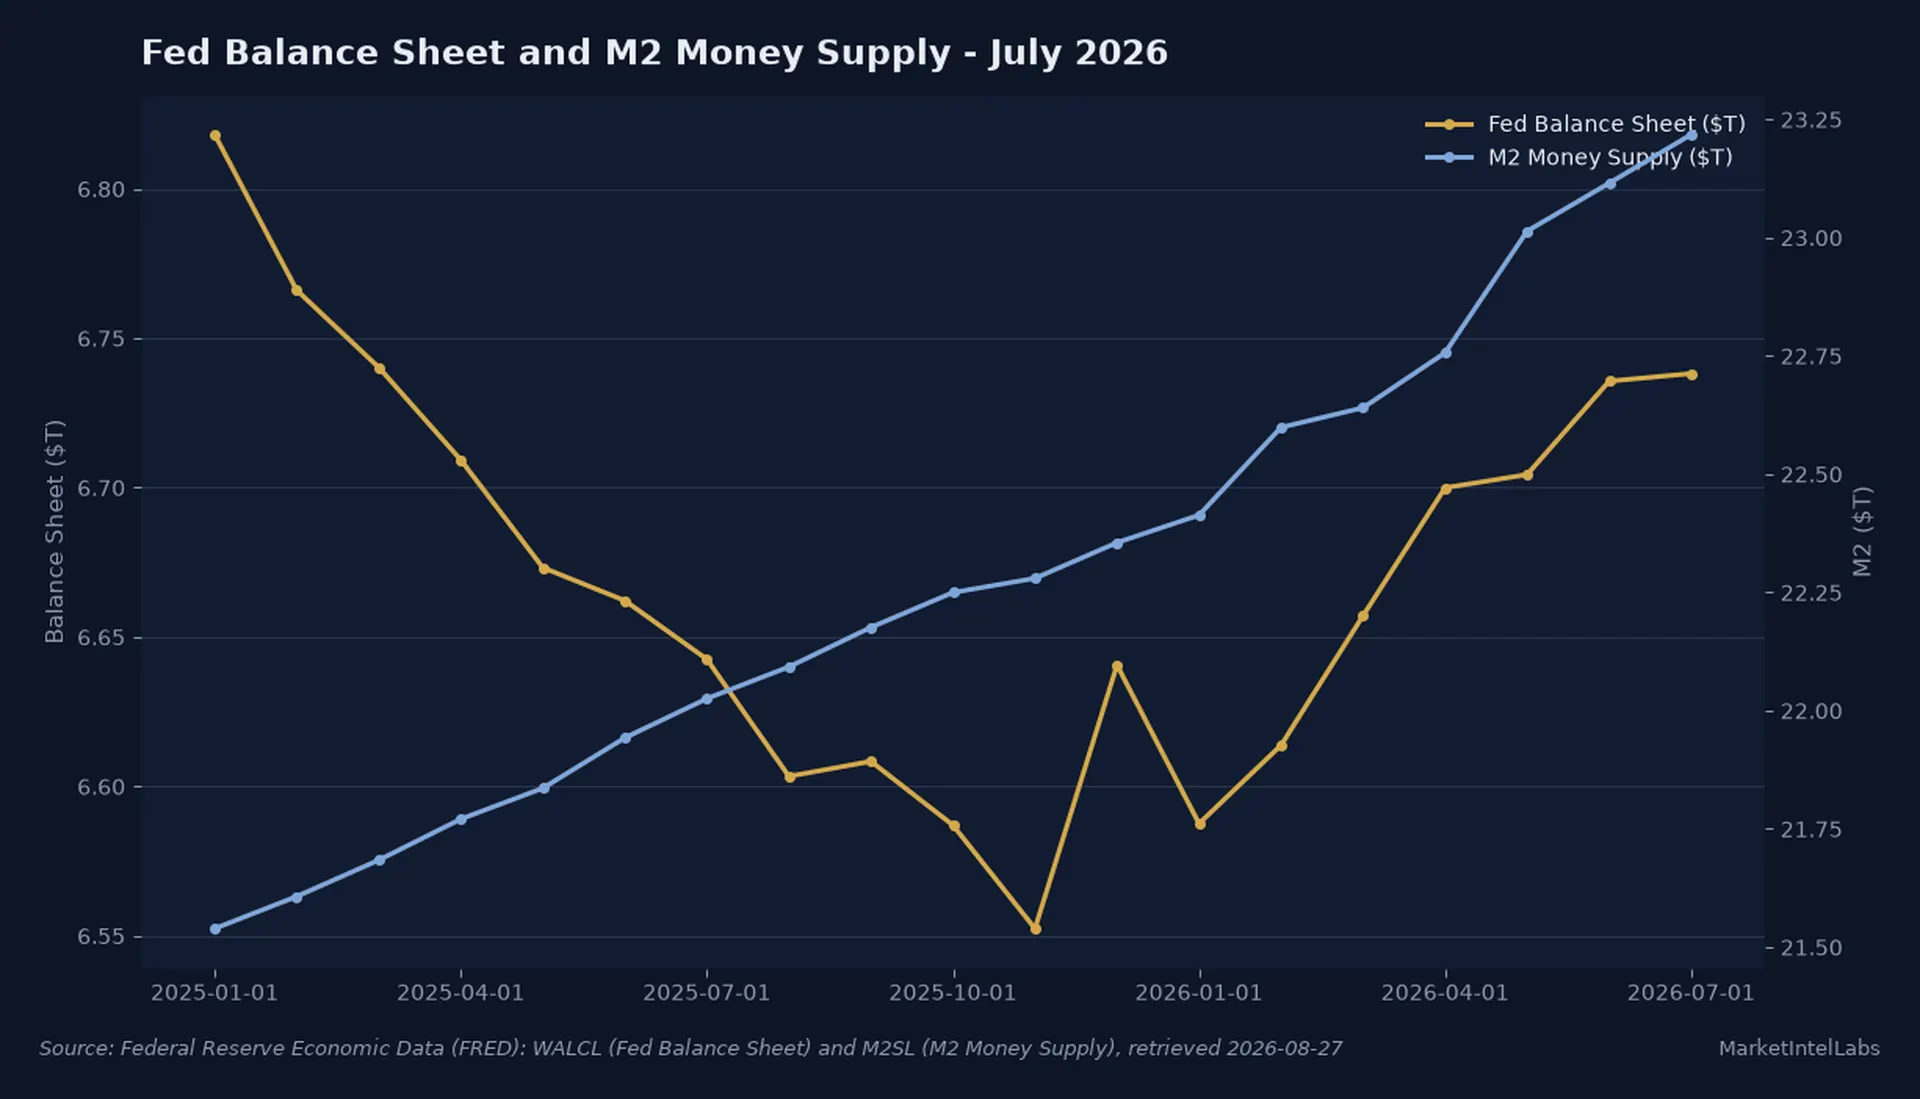
The Fed's balance sheet has been flat near $6.75 trillion since mid-July while core PCE runs at 3.34%. QT has quietly paused. This tension between hawkish dissents and liquidity constraints is what Jackson Hole 2026 is really about.