Hormuz Event Markets Settle No for the October 31 Blockade as the War Rolls On
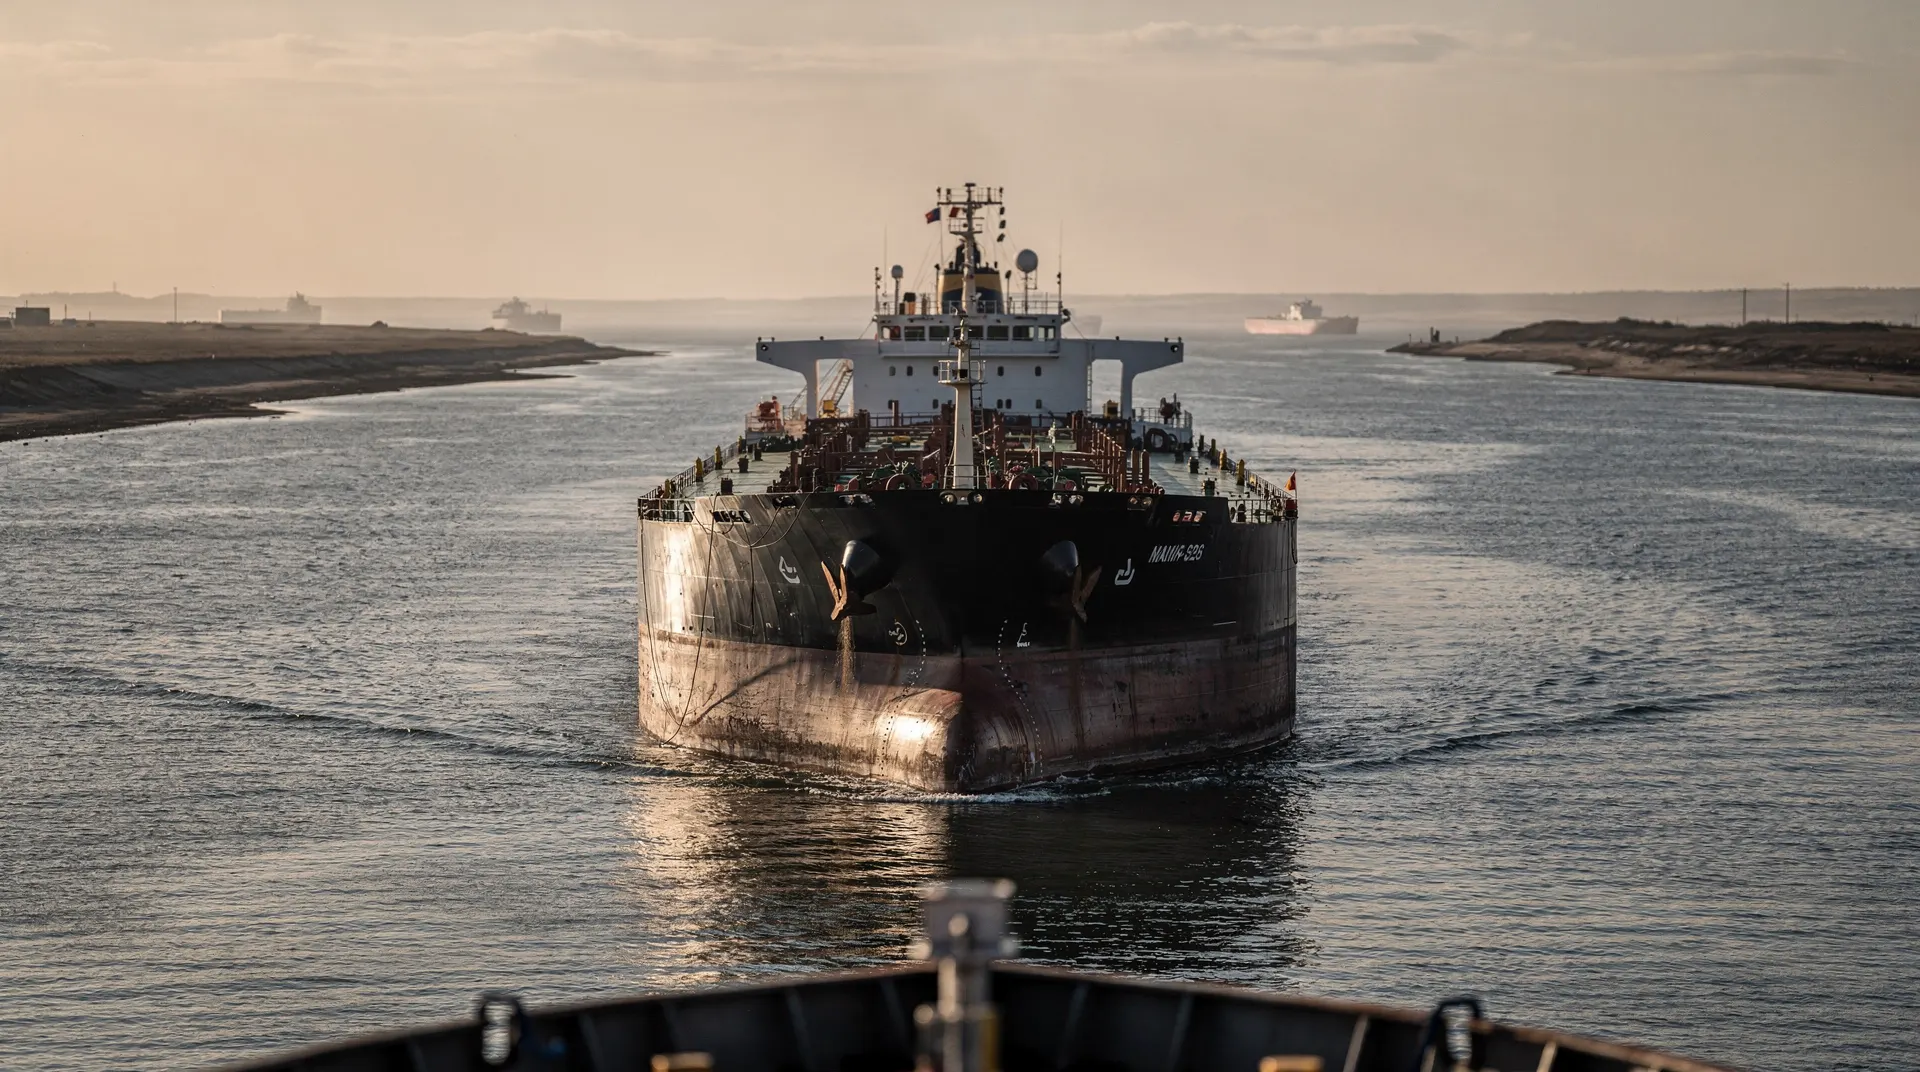
The market that moved most on this desk was not a single print but a deadline. The Strait of Hormuz contracts that reached their October 31 expiry have now graded, and the yes side lost on both of the ladder's axes: the political one, whether Washington would end its blockade, and the physical one, whether traffic through the strait would return to normal. Each settled no.
Polymarket's "US announces end of Iranian blockade by October 31, 2026" contract traded between 12.5% and 32% across the pieces on this desk through the month. The record is public: a US military update on October 31 said the blockade had redirected 144 ships, and officials said it would remain in full force. That last phrase is the market's entire problem. An announcement today was not an announcement this week, and the contract resolved no with no fair contest on the rules.
The companion "Strait of Hormuz traffic returns to normal by October 31" market, priced at 3% to 5% all October, settled no as well. Iran listed seven conditions before Hormuz could reopen, and tankers were still being hit in the strait into November 2, so the physical axis never normalised. The reopening was framed as a diplomatic bargain, not a mechanical return.
For the broader framework, see our Fed policy coverage.
Related reading: 2026 midterm odds: split Congress now 26.5 percent on Polymarket.
The one October deadline contract that reads the other way is the ceasefire itself. "US x Iran ceasefire continues through October 31" moved from 57.5% on October 1 to 84.5% by October 19 as this desk covered it, and it now reads near 99% yes as the venue works through settlement. Event contracts are not a year-over-year series the way a rates strip is; a ladder that expired October 31 did not exist on these boards a year ago and will not exist after close. The honest comparison is the month's trajectory, and it shows a market that kept buying the truce even as the interdiction campaign continued.
The larger pool of money this week sits on the November 3 midterms. Polymarket prices Democratic control of the Senate at 72% and of the House at 95%. Read these as expectations; they resolve on certified results, not on counting-night press. On the conventional-instrument side, Kalshi's December fed-funds ladder concentrated about 72% of the probability on the 4.00% rung, with the adjacent rungs near zero, a shape consistent with the futures strip looking for no change at the December meeting.
Related reading: Fed Rate Hike Odds Hit 83.5% for December as the 2-Year Backs the Move.
Thinner books printed the sharpest moves. The blockade-end contract traded on a modest notional, so a 144-ship update could lean on a thin ladder by whole probability points in an afternoon. That is structure worth stating plainly: volume decides how an event market absorbs a headline, and here it absorbed it on almost nothing. Where volume is the story, the midterm events are the exception, with Polymarket's congressional-control markets carrying the heaviest volume on the board this week, a real base of end users rather than the speculative tail on the Hormuz names.
Resolutions
"US x Iran ceasefire continues through October 31" priced 57.5% to 84.5% at coverage and resolves yes; the Islamabad-Memorandum truce held through the month and the venue reads near 99% yes. "US announces end of Iranian blockade by October 31" priced 12.5% to 32% and resolves no; the blockade stayed in force with 144 ships redirected by October 31. "Strait of Hormuz traffic returns to normal by October 31" priced 3% to 5% and resolves no; Iran made reopening conditional on seven demands and traffic did not normalise. "NATO x Russia military clash by October 31" priced 21.5% and resolves no; no NATO-Russia engagement was reported, the conflict record listing the US, Israel and Iran as belligerents. "SCOTUS accepts sports event contract case by October 31" priced 3.5% and resolves no; the venue settled no and the Court's October certiorari list carried no such grant.
Related reading: Fed October 2026 odds: Kalshi prices a 94% hold, December still sees a hike.
Election Day is November 3, with the House and Senate control contracts then riding to certified results. The November CPI print follows mid-month, and the December FOMC decision is the next rate resolution, its ladder already pricing the 4.00% rung near 72%. Those are the dated markers ahead.
The month that ended Friday left the diplomatic deadline behind and the military campaign in front. The next set of contracts on Strait of Hormuz reopening will price Iran's seven conditions, Washington's staying power under a new Congress, and whatever the certified midterm outcome does to the governing balance. That ladder, not the one that just settled, is where the week's signal sits.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.