Fed Rate Hike Odds Hit 83.5% for December as the 2-Year Backs the Move
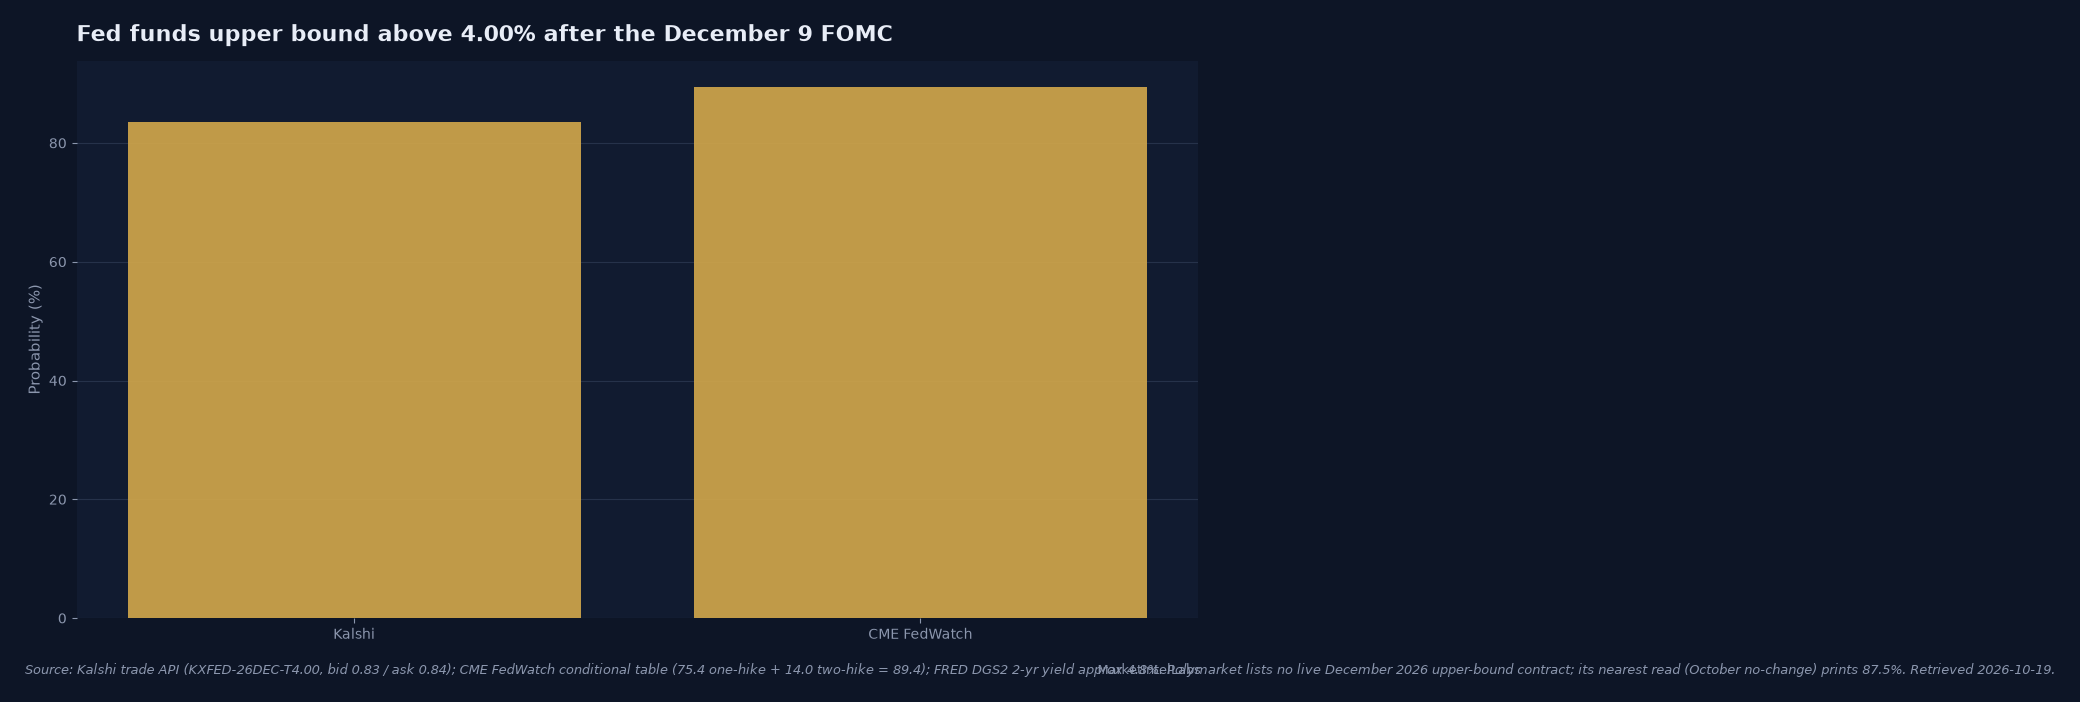
The week of October 19, the event markets have effectively split the Fed calendar in two. Prices on Kalshi and Polymarket say the October 28 meeting is a near-certain hold, with the upper bound on the federal funds rate staying at 4.00 percent roughly 88 percent of the time. The December 9 meeting is where the market now leans toward a move: Kalshi prices an 83.5 percent chance that the upper bound ends above 4.00 percent after that decision.
September CPI is the print that moved the rate path this week. The Bureau of Labor Statistics reported on October 14 that the all-items index rose 0.6 percent on a seasonally adjusted basis for the month and 3.7 percent over the trailing twelve months, a step up from August's 3.4 percent and above the 3.6 percent economists expected. Core inflation ran 2.6 percent year over year, also ahead of the 2.5 percent consensus, and 0.3 percent on the month. Energy did most of the work, with gasoline up 9.1 percent in September and the energy index up 20.4 percent from a year earlier, but the three-tenths core print means the report was not a purely transitory story.
Related reading: Fed Rate Markets Price 84.5% October Hold.
What the Fed market prices across the calendar
Read the Kalshi federal funds series as a decision tree. It asks, for each meeting, whether the upper bound of the target range will be above a given level when that meeting ends. On the morning of October 19, the October contract pricing the bound above 4.00 percent sat at a 12 percent midpoint, with a 0.11 bid and 0.13 ask, down from a 0.16 previous print. The contract pricing the bound above 3.75 percent was at 99.5 percent. Together those imply a roughly 88 percent hold at 4.00 percent and a low-double-digit chance the Committee hikes 25 basis points to target the 4.25 percent upper bound.
Polymarket's October meeting market agrees. It prices no change at 87.5 percent, a 25 basis point increase at 11.5 percent, and a 50 basis point increase at 0.35 percent. The conventional strip lines up as well. CME FedWatch on October 19 put an 84 percent probability on no change at October's meeting and 16 percent on a hike, with the implied fed funds range sitting at 375 to 400 basis points, which is an upper bound of 4.00 percent.
For the broader framework, see our Fed policy coverage.
Related reading: October Fed Ladder Priced Near a Coin Flip While the CPI Strip Quietly Reprices.
The longer-dated Fed contracts are where the calendar splits. Kalshi's December 9 contract pricing the upper bound above 4.00 percent carried an 83.5 percent midpoint on October 19 (bid 0.83, ask 0.84), and the contract above 4.25 percent sat at 14.5 percent. That is a market pricing more than an 80 percent chance that the target range has moved up at least 25 basis points by the final meeting of the year, with a small tail of a deeper move to the 4.50 percent upper bound.
CME's conditional December table reads the same way: 75.4 percent at a 400 to 425 basis point range (one hike) and 14.0 percent at 425 to 450 (two hikes), against a 10.6 percent chance of still holding at 375 to 400. Both venues concentrate the tightening on December rather than October, which is the cleaner read of this week's data.
Related reading: Event markets moved to a 56 percent October hike after Warsh's first raise. The 2-year Treasury moved with them..
The conventional cross-check
The bond market is not leaning against the event contracts. The 2-year Treasury yield traded near 4.8 percent through mid-October, roughly 80 basis points above the current 4.00 percent upper bound, which implies the front end has priced in further tightening. The 5-year inflation breakeven sat near 2.37 percent after the CPI release, a shade above where it traded before the print, telling the same sticky-inflation story the report itself showed. There is a modest venue divergence worth noting with the numbers attached: CME prices an October hike at 16 percent while Kalshi carries 12 percent and Polymarket 11.5 percent, and on December CME implies just under 90 percent odds of at least one hike while Kalshi reads 83.5 percent. That is a small gap, not a disagreement between markets about direction.
Resolutions and what is dated next
The September federal funds market settled with the upper bound resolving at 4.00 percent, in line with the FOMC's September statement and the 375 to 400 basis point range priced throughout the cycle. No previously covered market on this desk came due for resolution between last week's briefing and this one.
Related reading: RBI Rate Hike Odds Resolve YES After October 7 Decision.
The Federal Open Market Committee meets October 28, the next event on the immediate calendar. The October CPI release lands November 10, and the final 2026 FOMC decision is December 9, which is the meeting that carries the pricing weight the event markets are currently showing. The November inflation print is the data dependency that will decide whether the December move the market currently prices holds or fades.
Sources: BLS Consumer Price Index Summary, September 2026, Kalshi federal funds rate markets, Polymarket Gamma API, CME FedWatch Tool, FRED DGS2 / T5YIE.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.