2007-style repricing hits equities: yields and the ceiling
The 10-year closed at 5.24%, highest since 2007, and repriced the S&P 500. Why the discount-rate move caps the index near 7,850 until PCE and payrolls.
Daily coverage · James Nakamura
Earnings, sector rotation and what the index is really pricing.

The 10-year closed at 5.24%, highest since 2007, and repriced the S&P 500. Why the discount-rate move caps the index near 7,850 until PCE and payrolls.

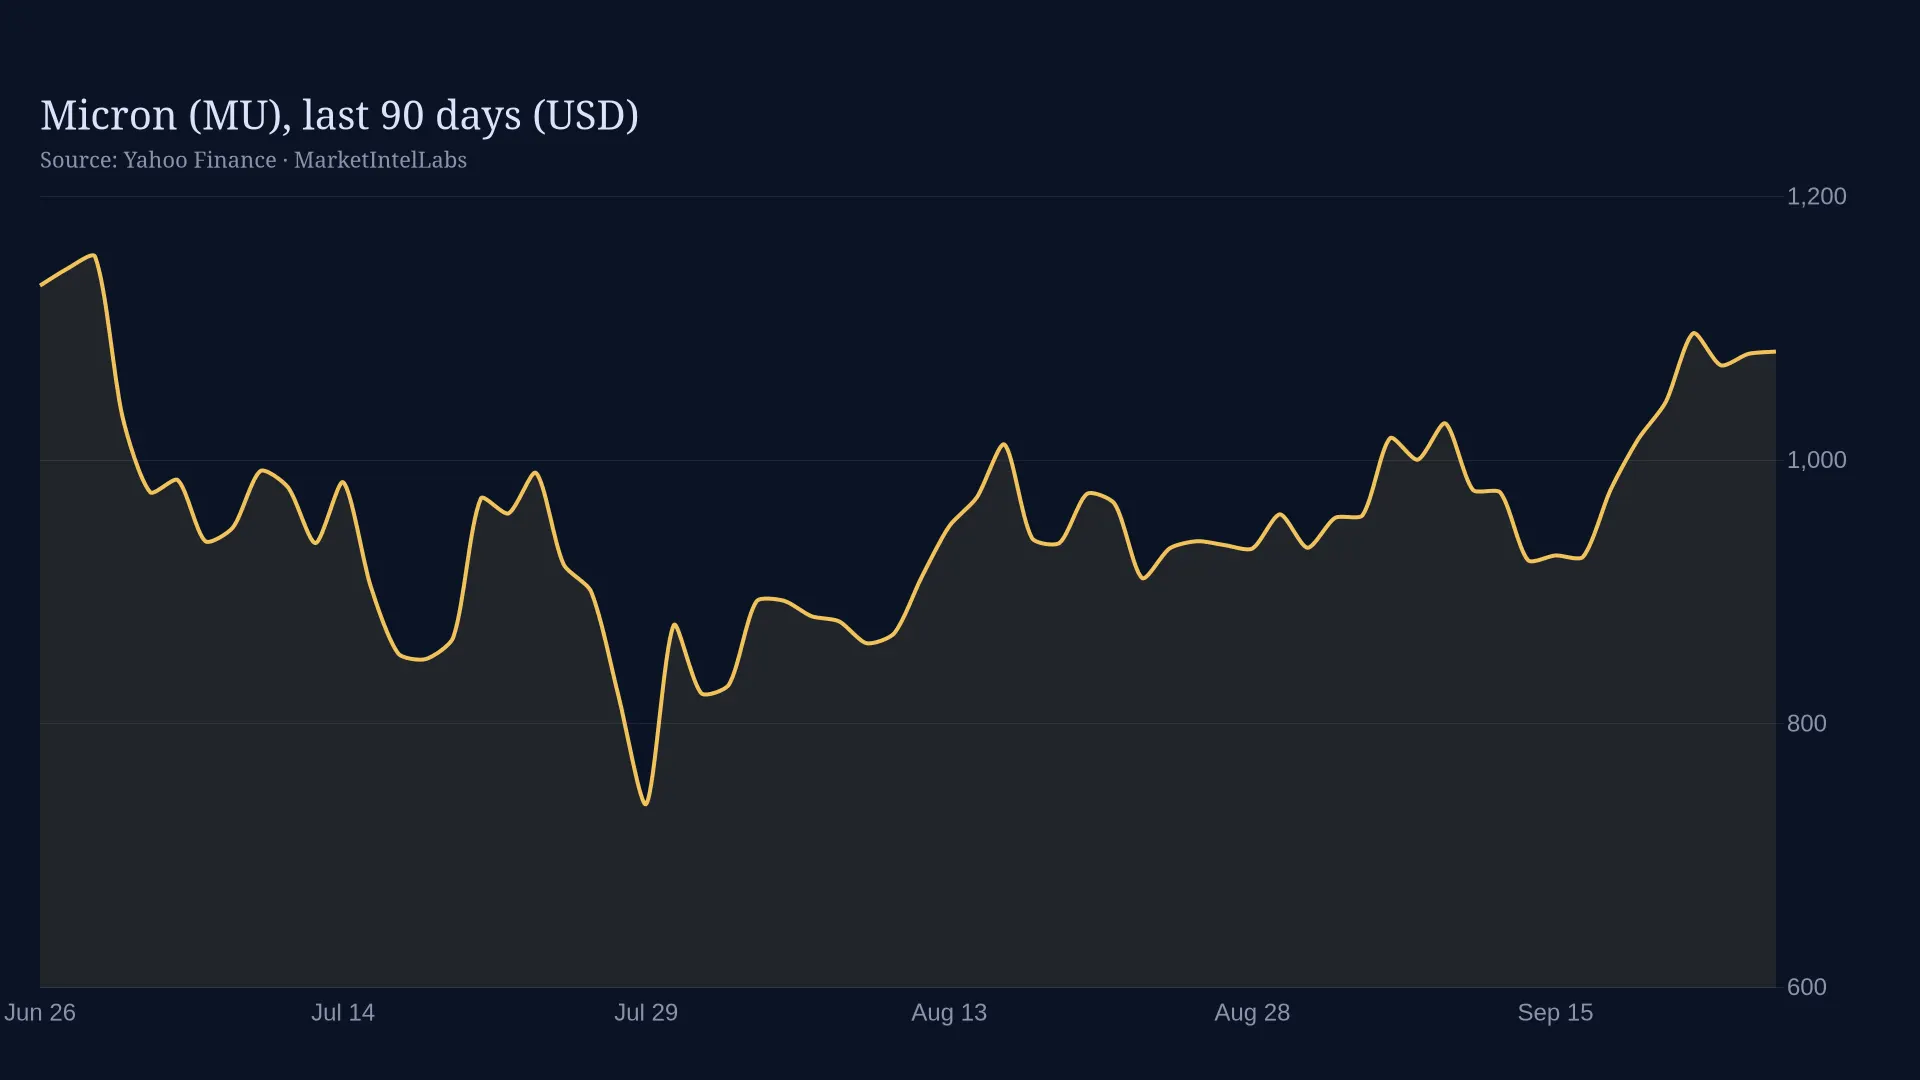
Earnings season opens with Micron, the highest-signal read on the AI memory cycle, as consensus calls for EPS of $31.16 on revenue near $50.45 billion. Nike is the discretionary test and Accenture the services read, framed against PCE, payrolls and 22 Fed speakers.

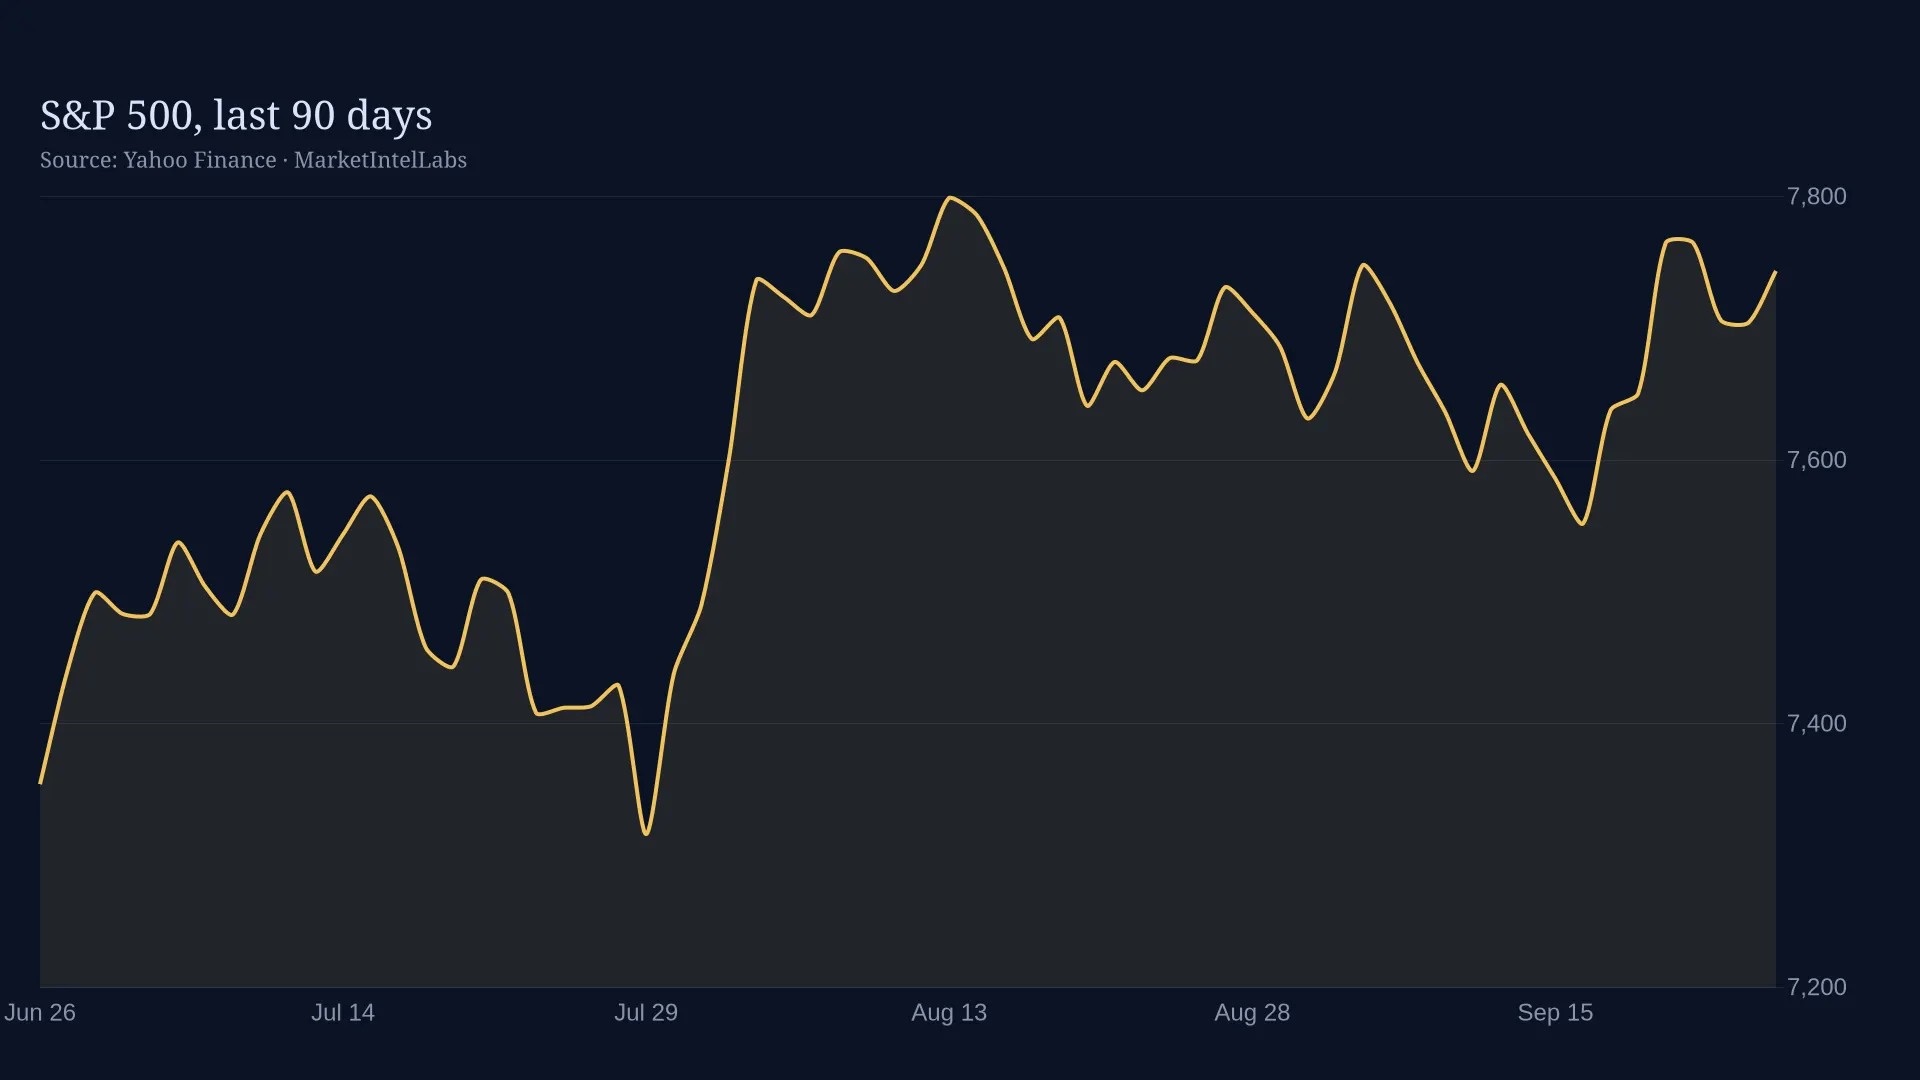
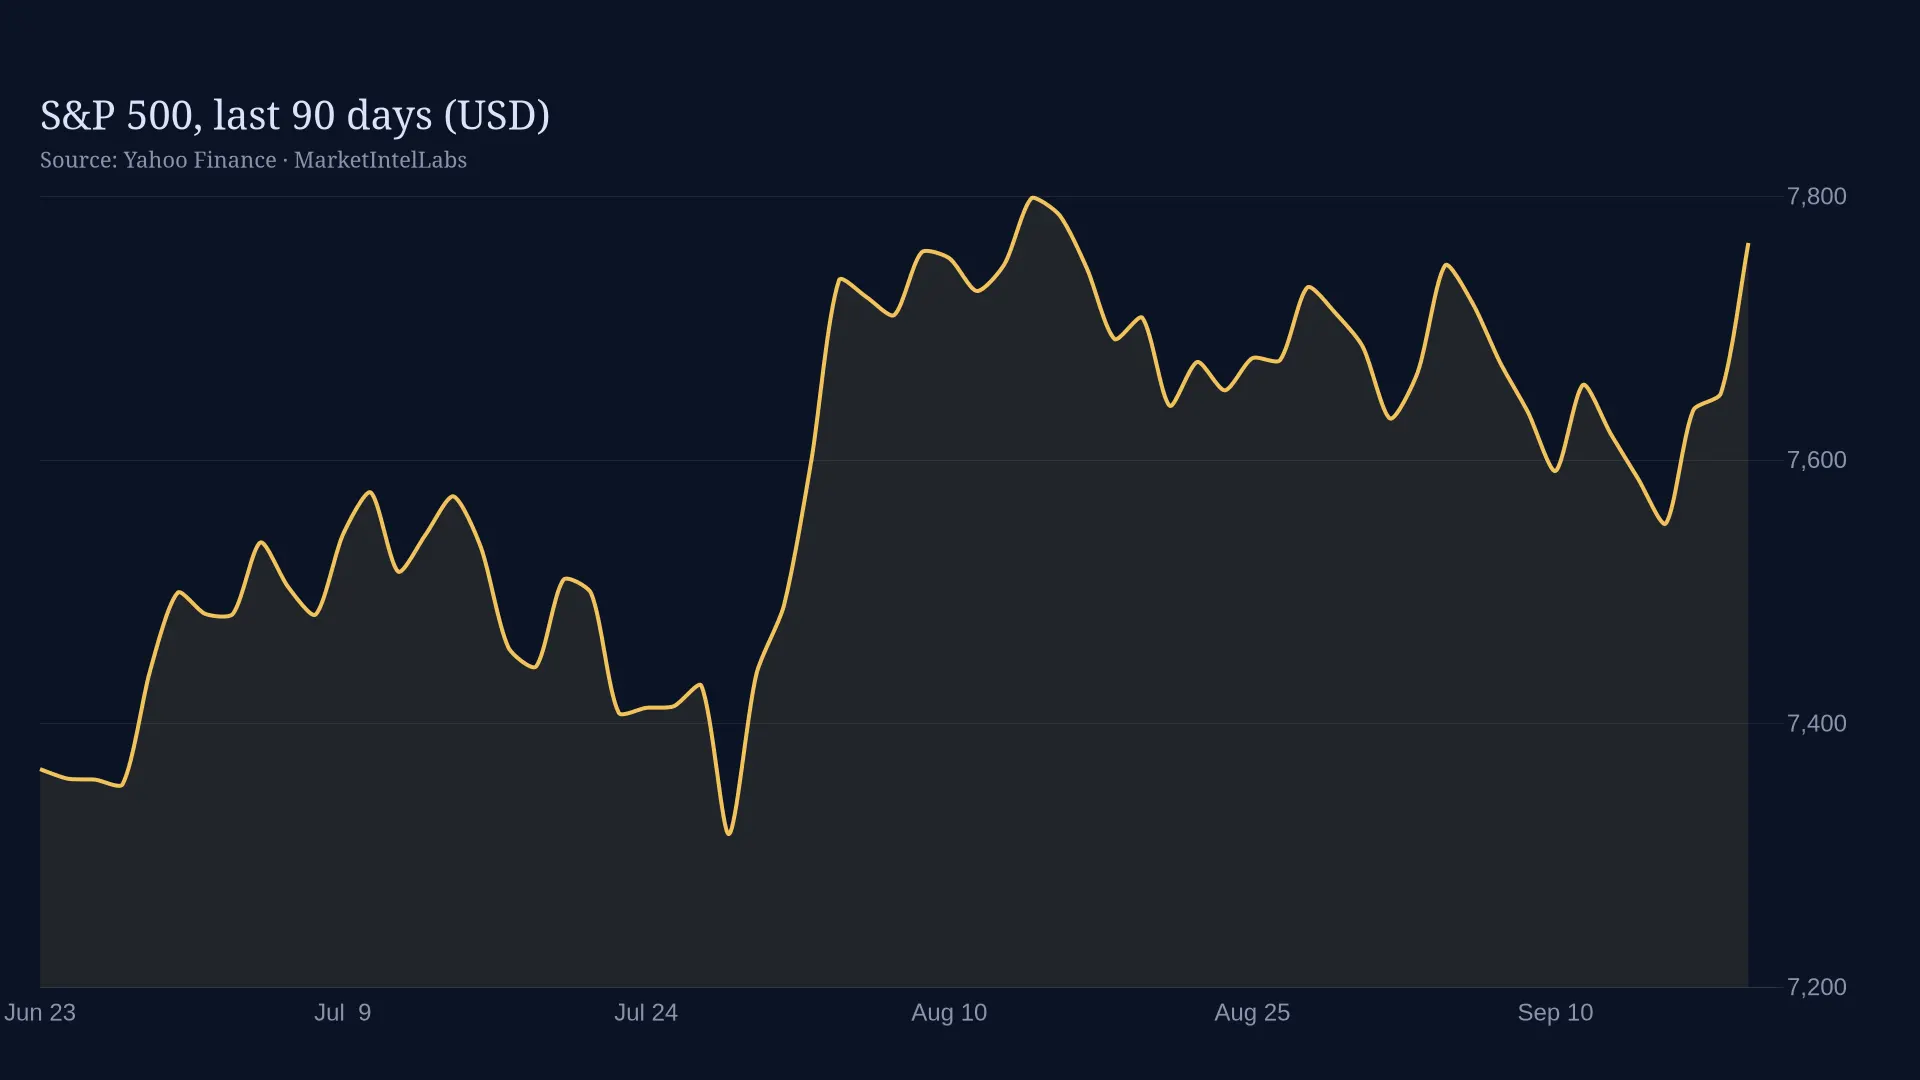
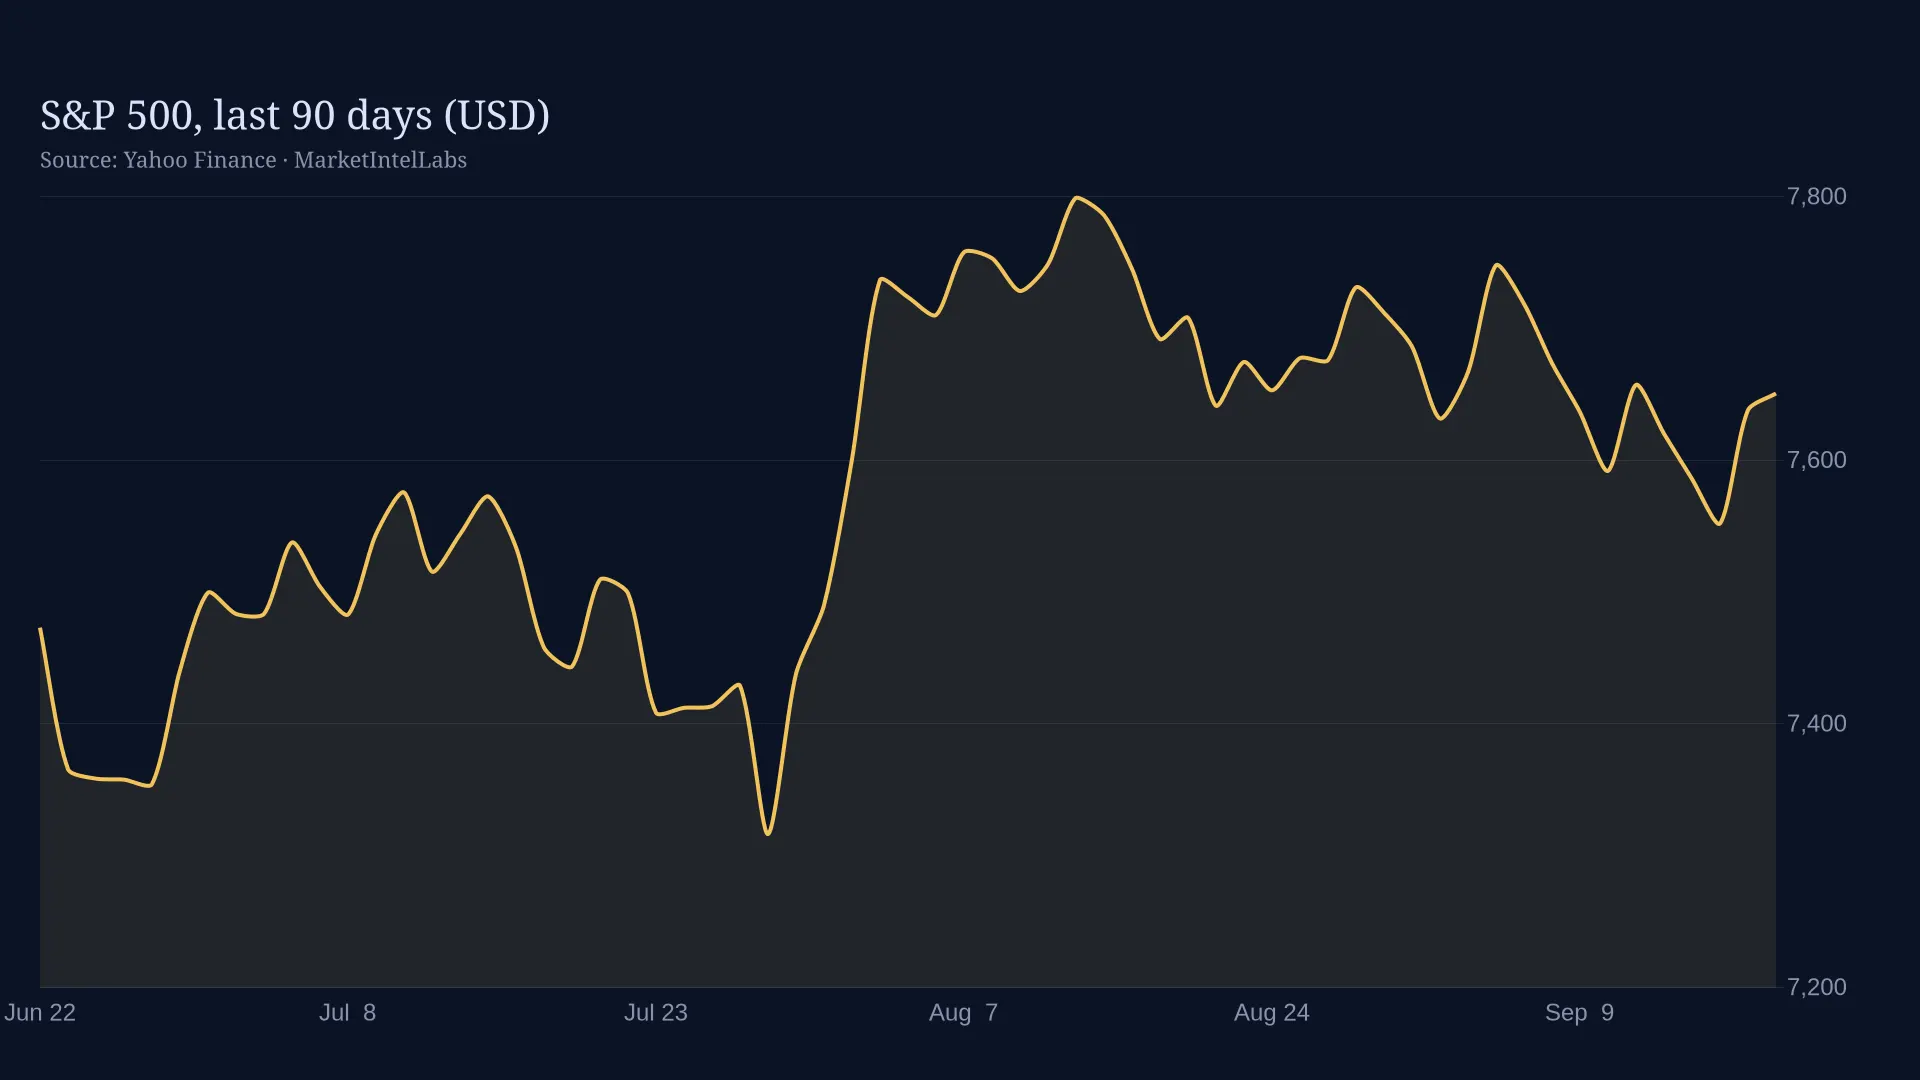
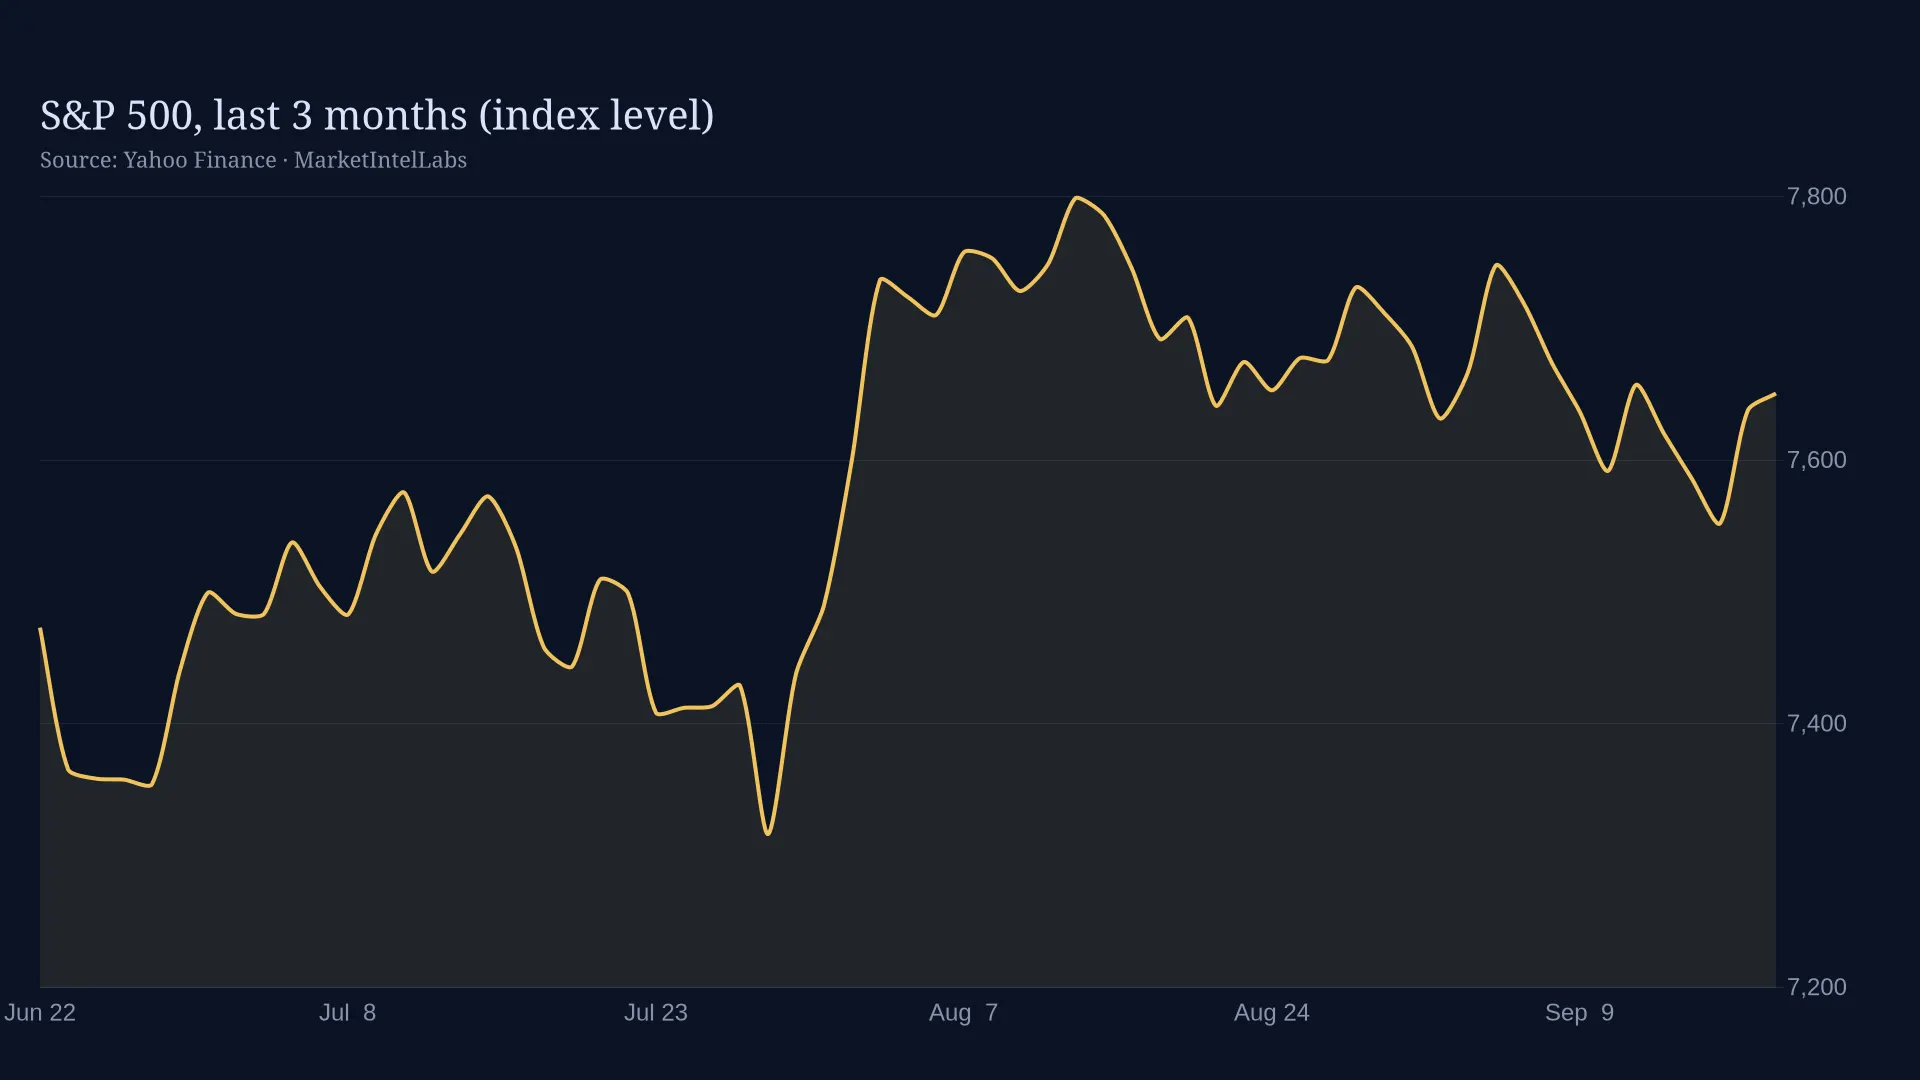
The S&P 500 closed Friday 0.54% higher at 7,743.41, within 1.0% of its record, but the Russell 2000 gained just 0.11% and sits 7.6% below its high: a quality-led advance into August PCE Wednesday and September payrolls Friday, with 22 Fed speakers in between.

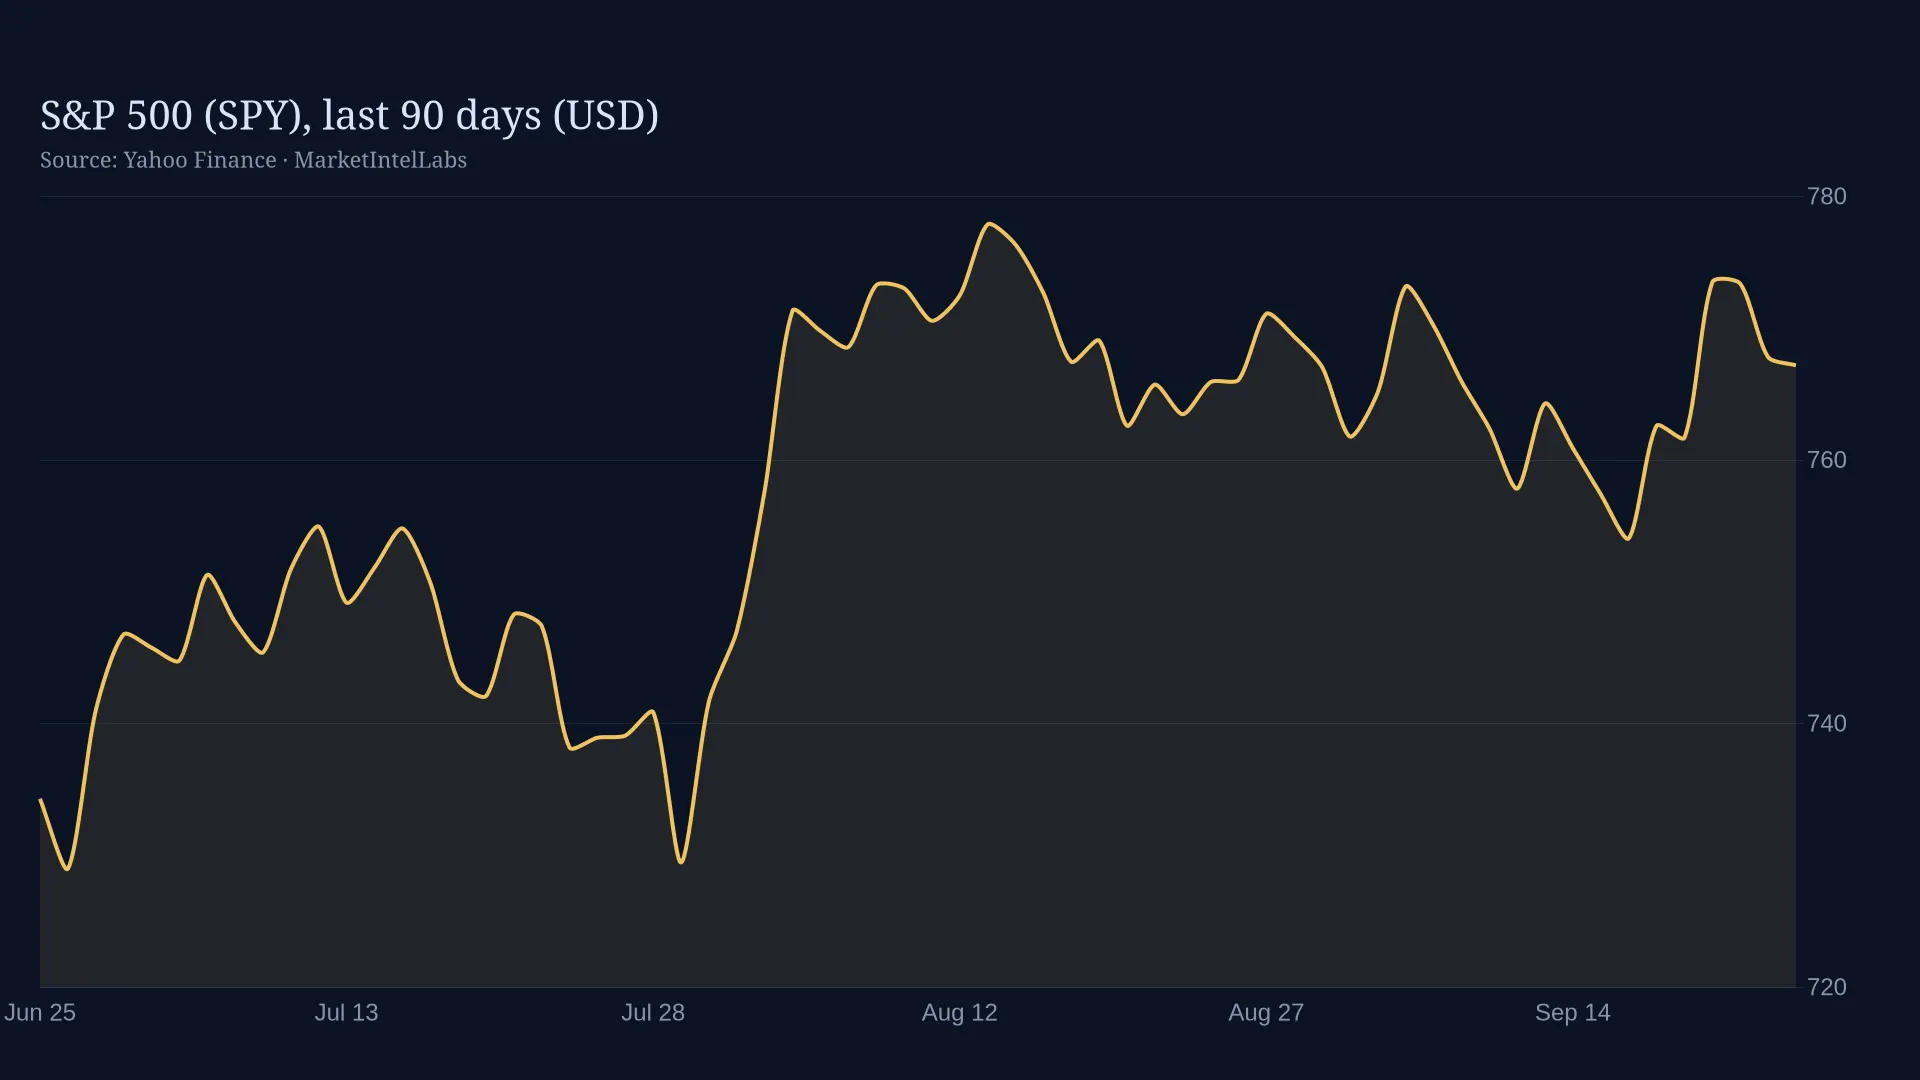
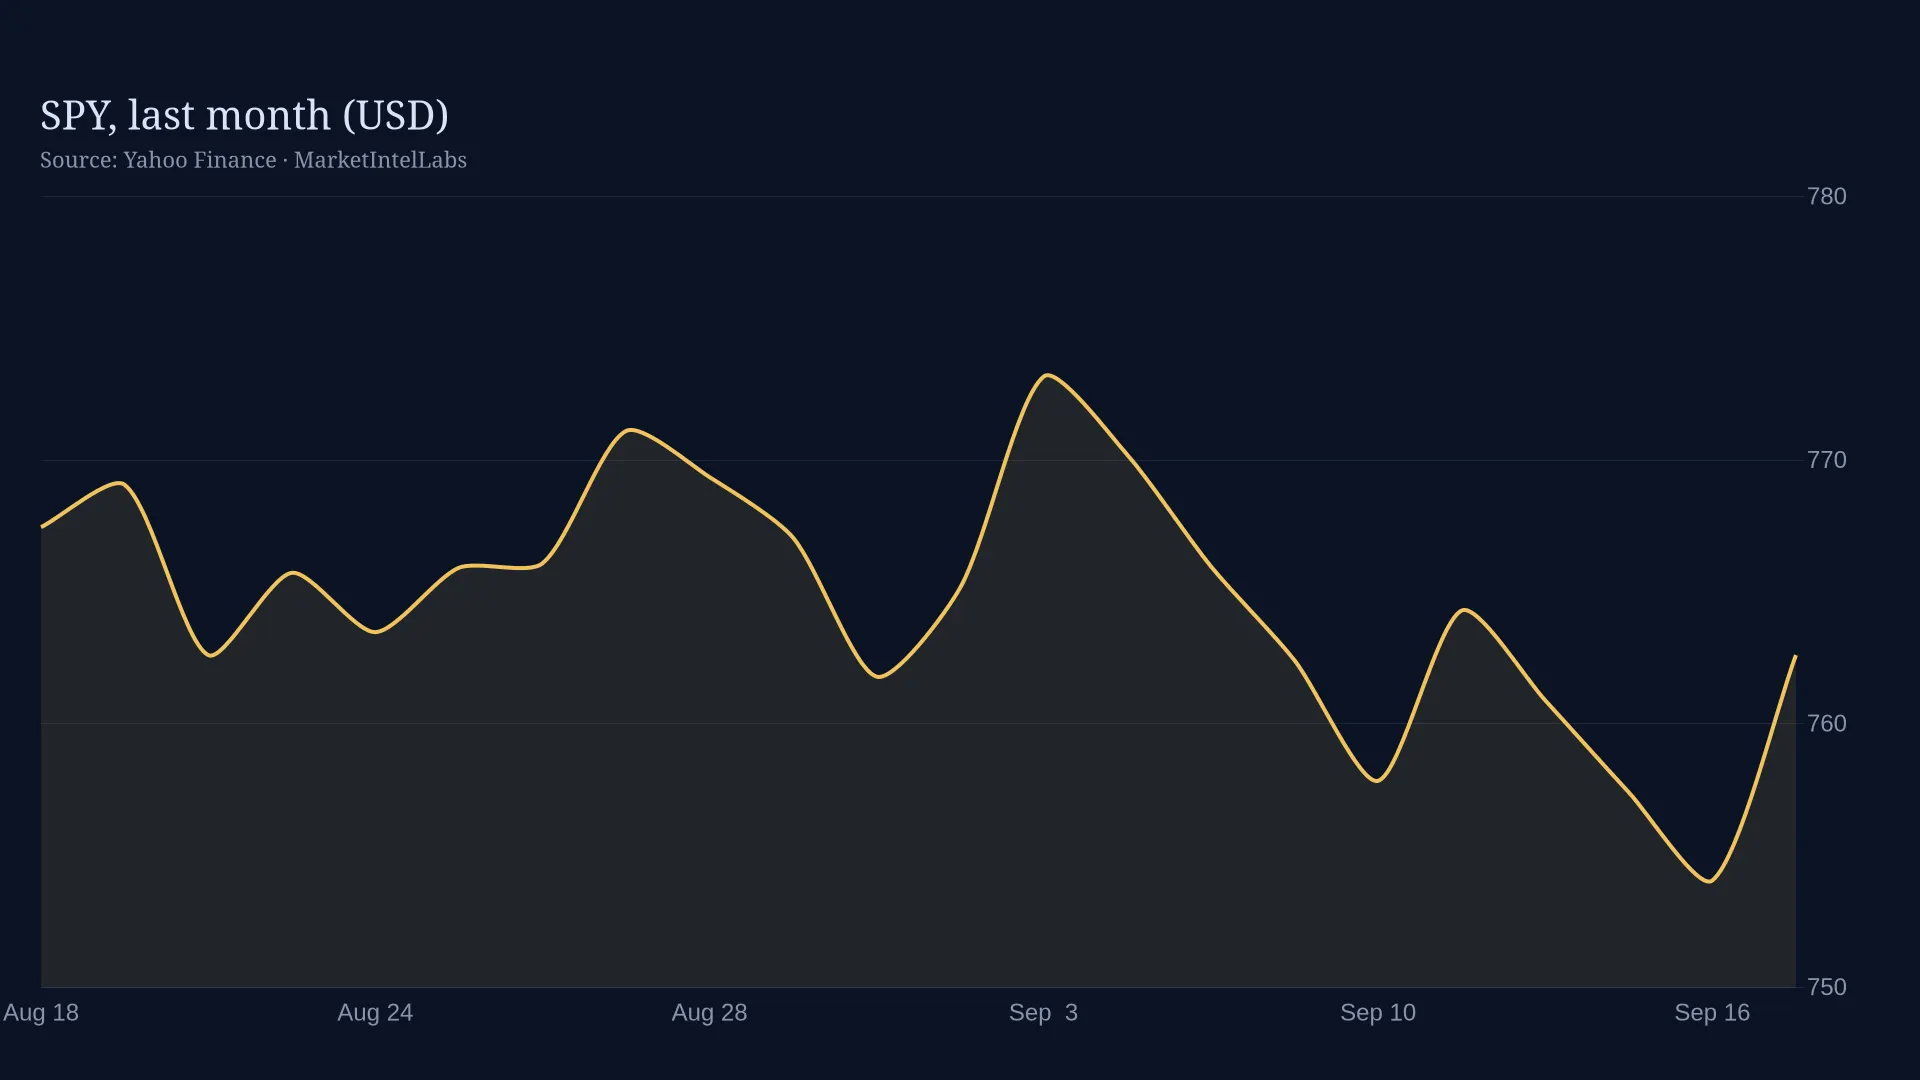
SPY closed Thursday up 0.72% at 767.18, but a 5% 10-year yield drove a rate-shock rotation under thin breadth ahead of the Sept 30 core PCE print.

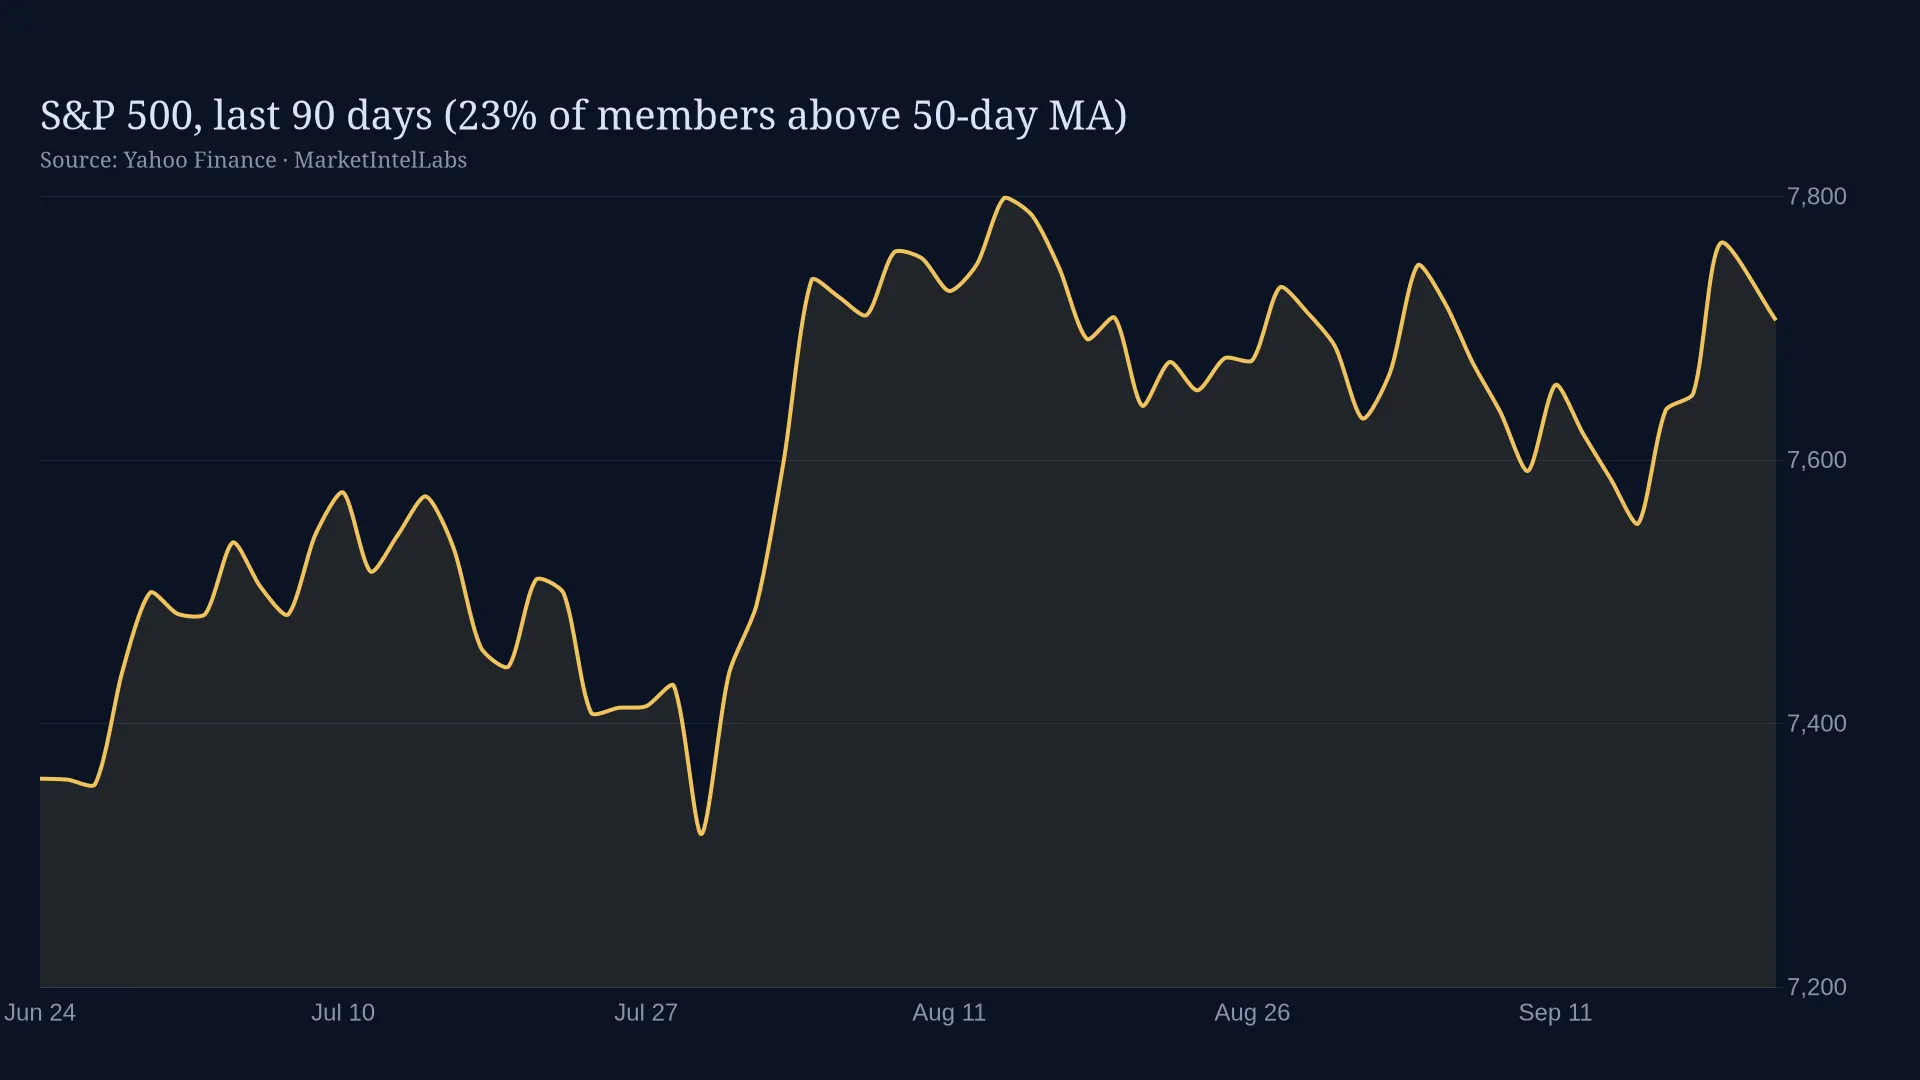
SPY fell 0.72% to 767.81 as advance share broke to 23%, a thin tape under a resilient index. Small caps and utilities led the decline while energy rose.

Initial claims Thursday, then Sept 30 core PCE, GDP and Micron Q4 decide a narrow market trading with VIX at 14.21. What the three prints mean for equities.

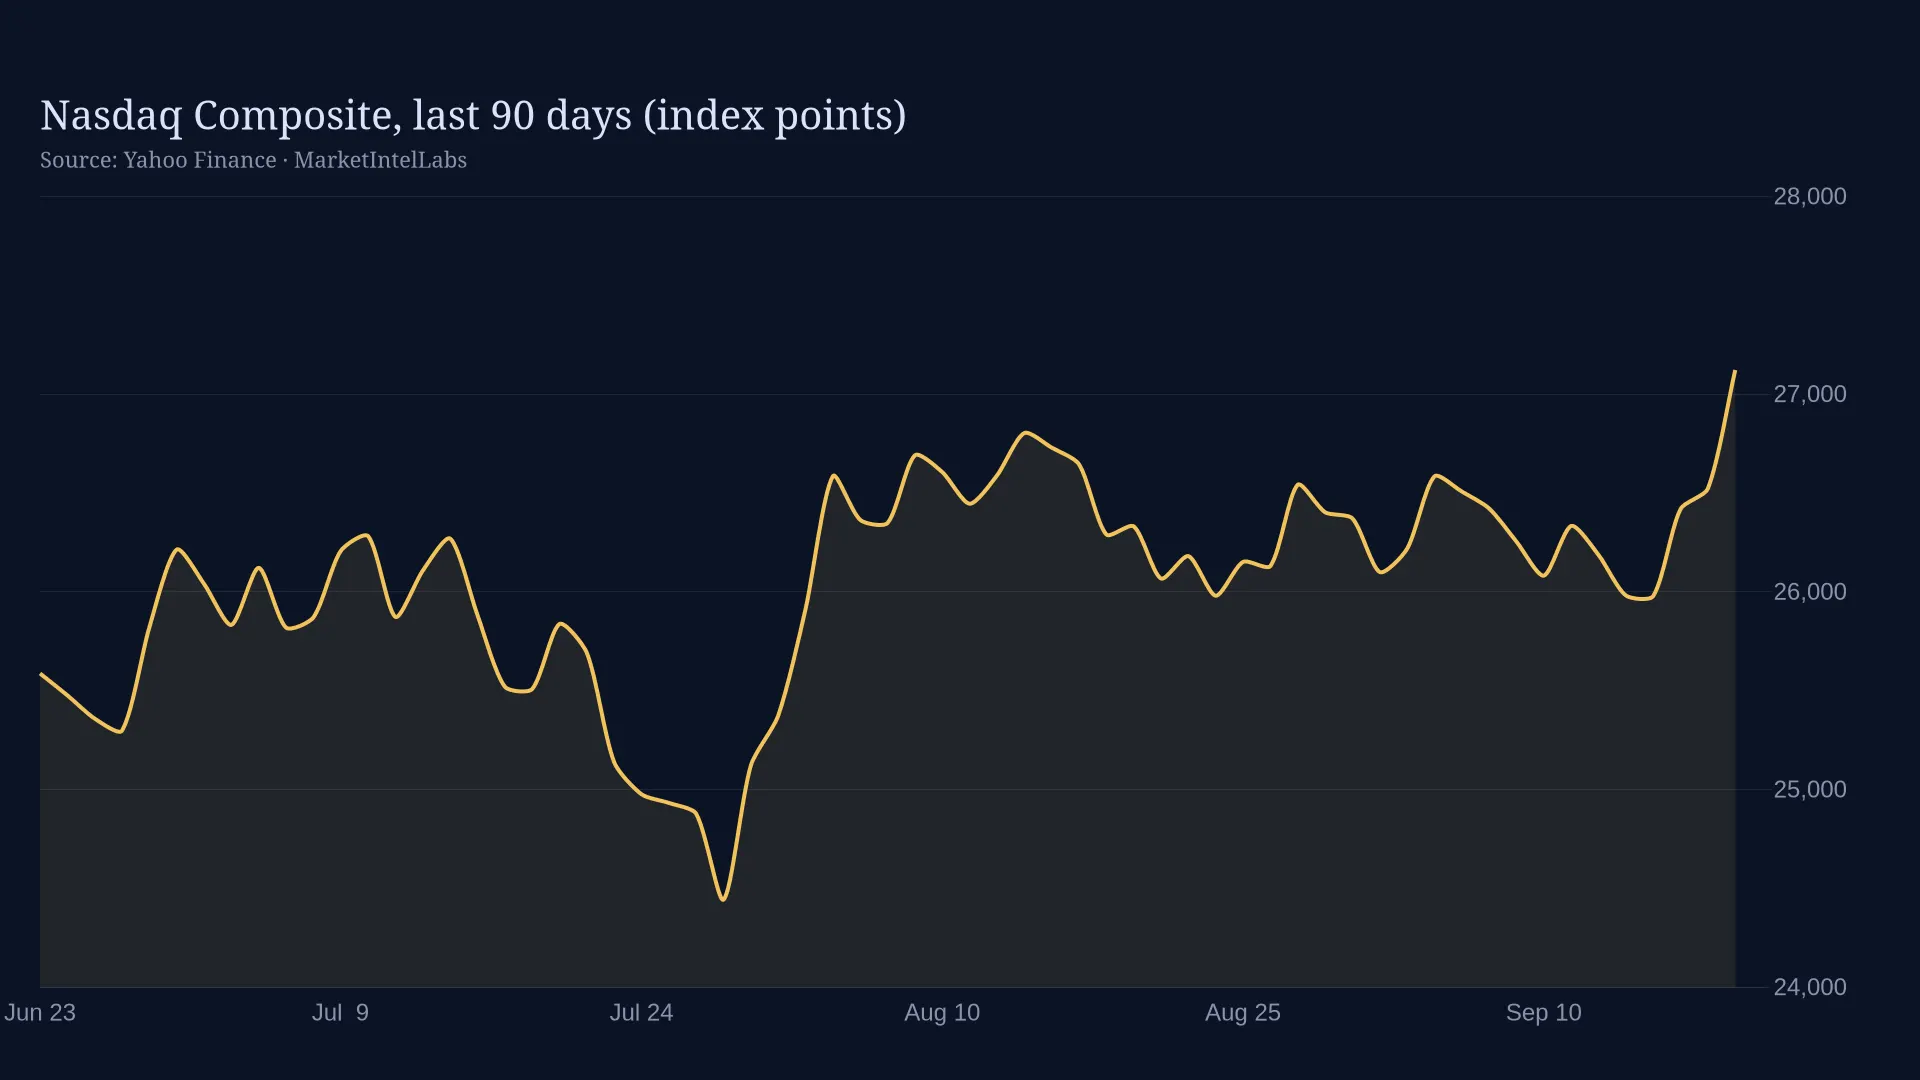
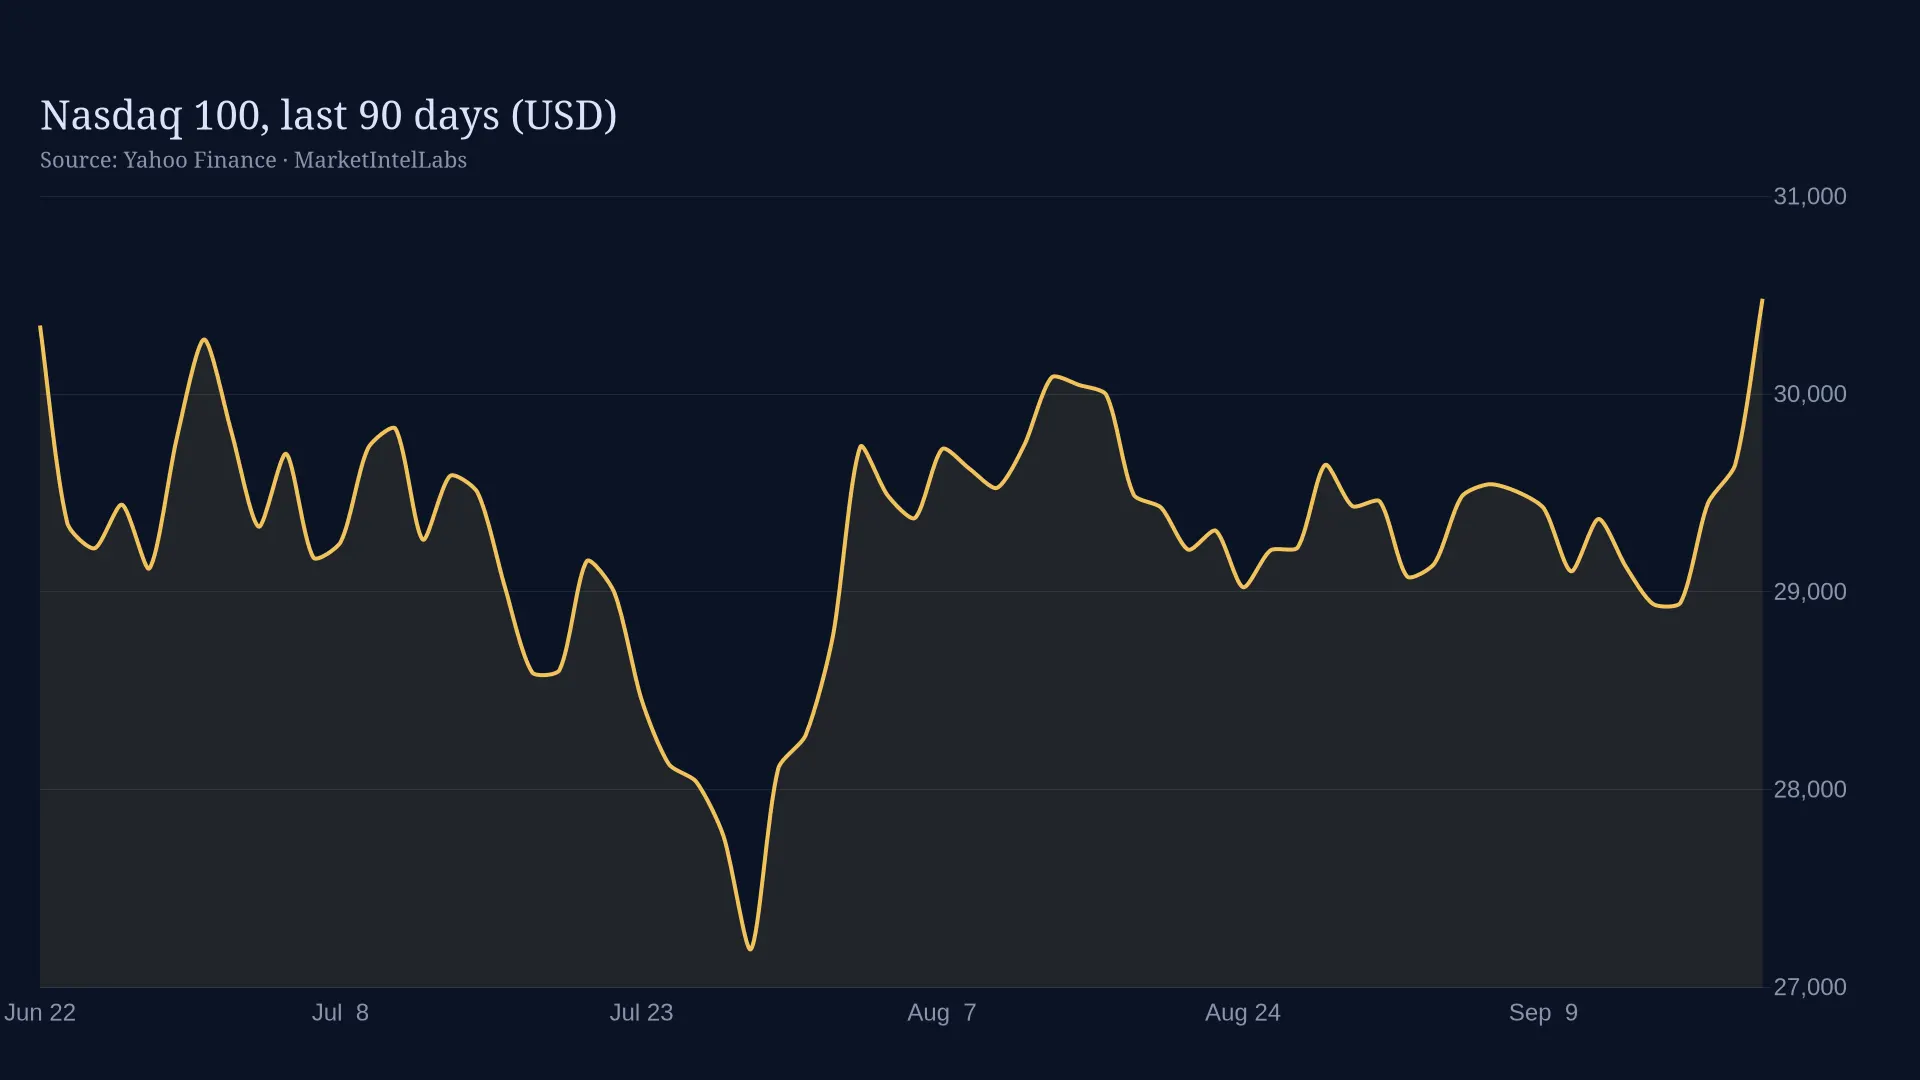
The Nasdaq 100 hit a record 30,732.40 while the S&P 500 closed flat at 7,764.64. Thin, chip-led market breadth: why narrow records are the real tension.

SPY hit $773.50, within 0.75% of its high, yet small caps and defensives lagged as the VIX near 15 left a narrow Nasdaq-led tape exposed to this week's data.

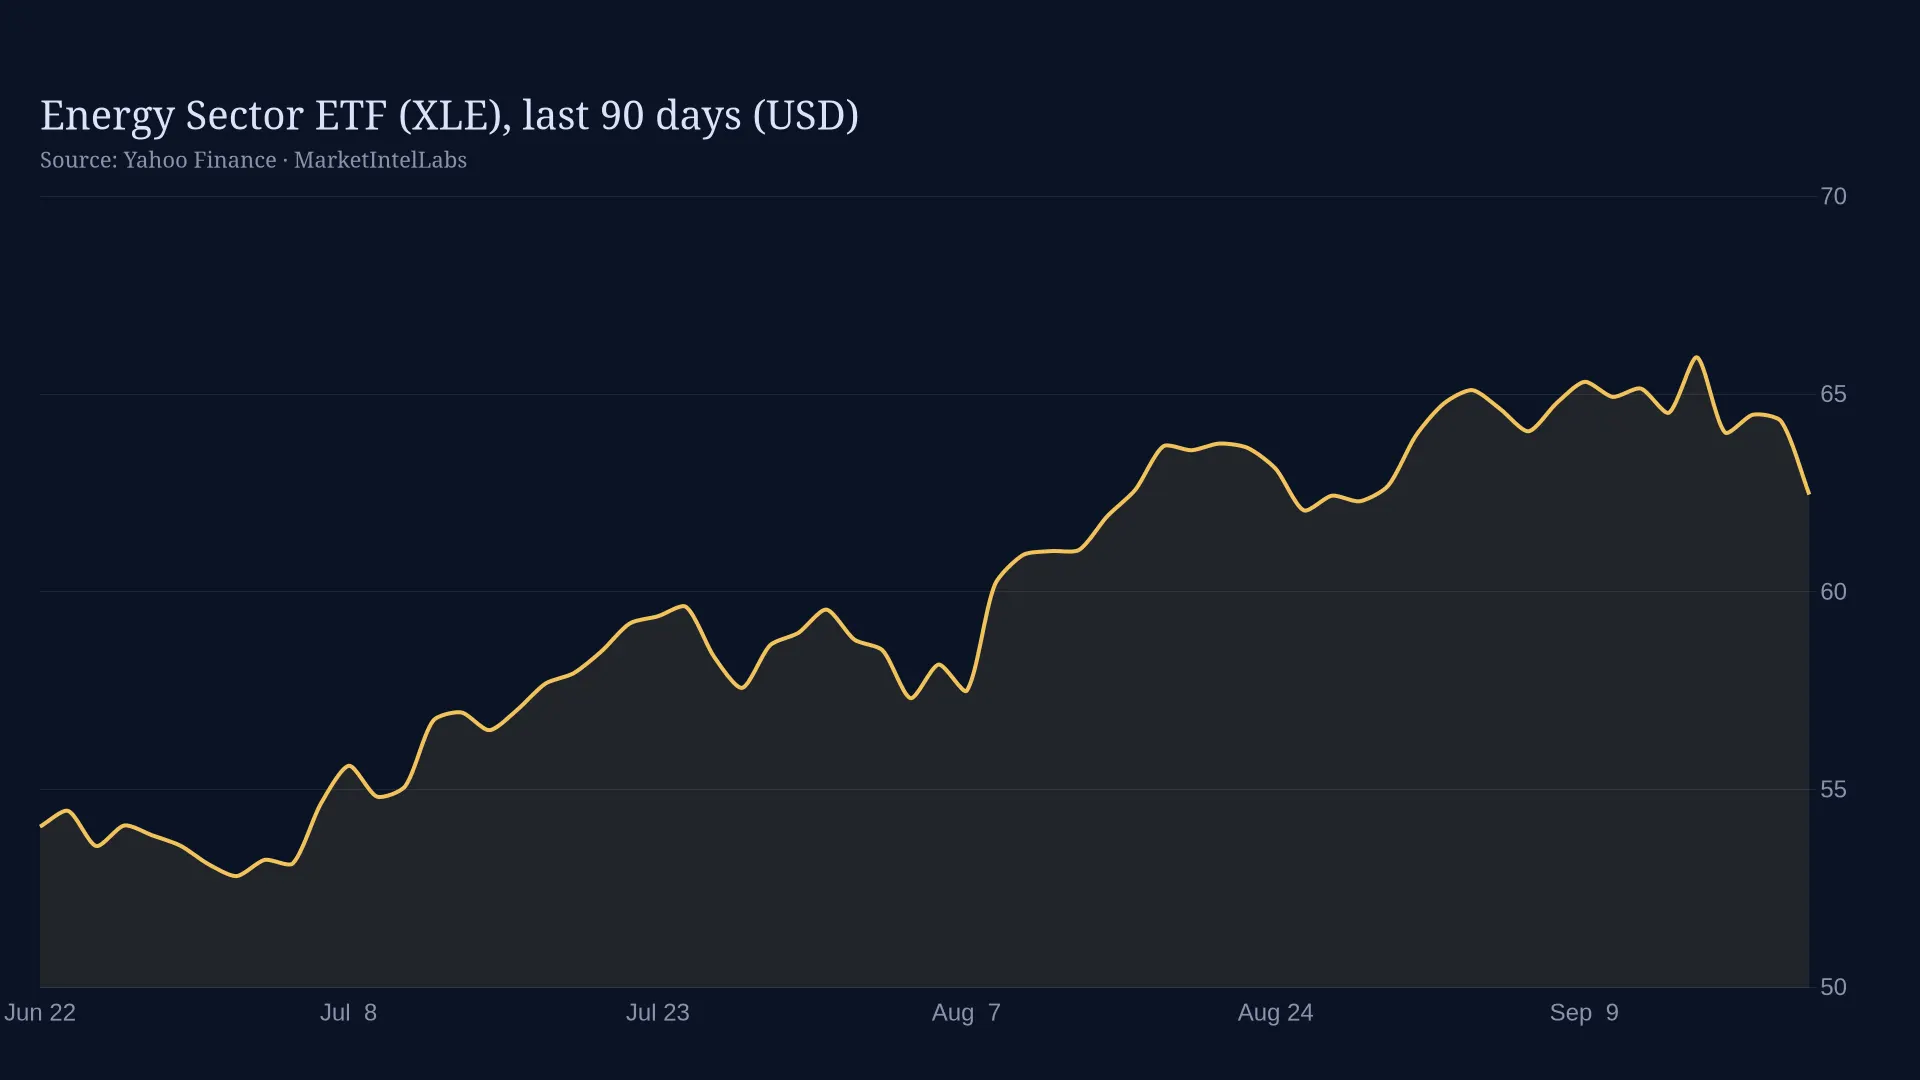
XLE, the energy sector ETF, fell 2.30% to $62.46 even as SPY and QQQ rallied, while gold, silver, bitcoin and ether eased. A growth-concentrated rotation, not broad risk-on.

The S&P 500 closed near a recent high (7,650.5) after the Fed's hike, but only ~31% of its members hold the 50-day. Narrow participation tests whether this rally is built to last.

Costco, Darden and KB Home earnings test post-Fed consumer and housing demand as S&P 500 breadth thins. See the numbers and what Thursday's prints could signal.

SPY closed Thursday flat for the week at $762.60, but the tape was defensive: healthcare and staples led while financials and industrials fell. What the rotation signals next.