Micron leads earnings season as the AI memory trade's tell

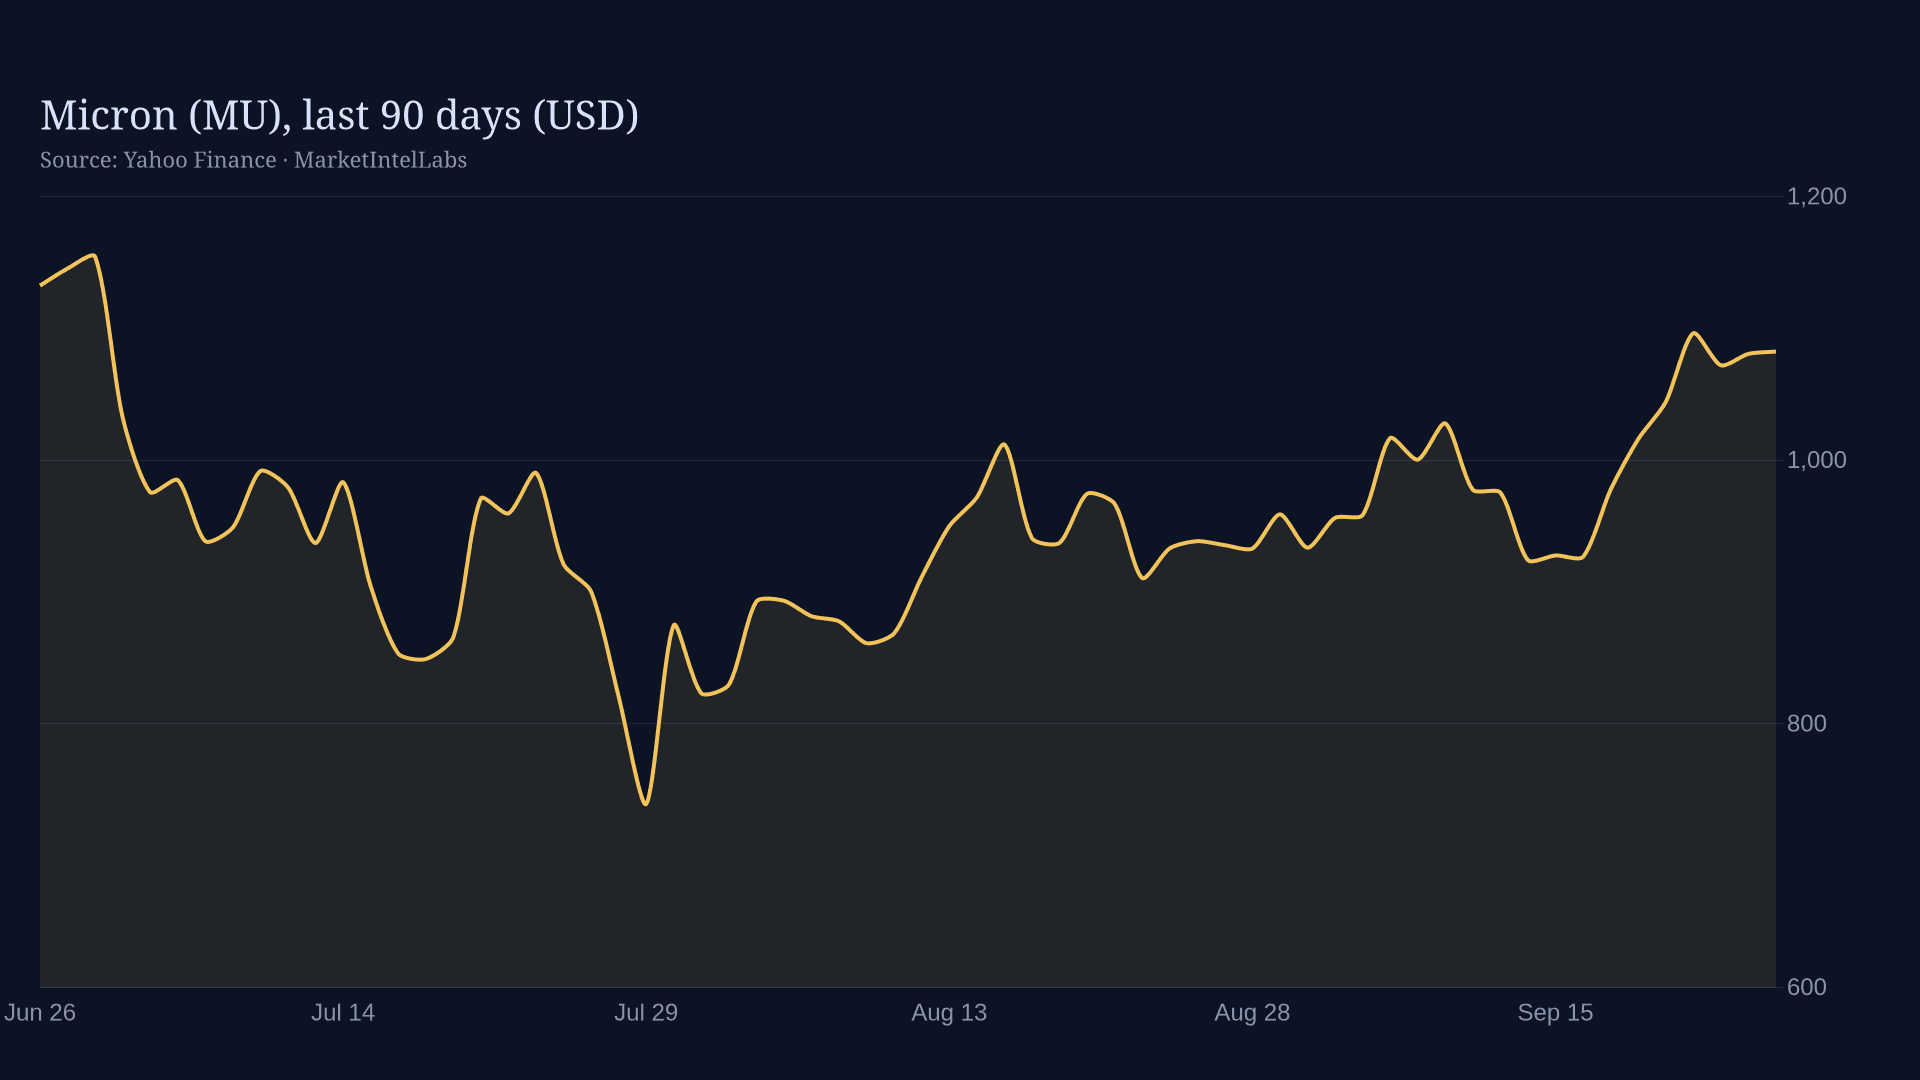
Earnings season opens today with a report that tells us more about where this market is headed than any macro print on the calendar: Micron. The memory maker is the single highest-signal read on the AI infrastructure cycle, and tonight's number, with consensus calling for EPS of $31.16 on revenue near $50.45 billion, is the cleanest test yet of whether the trade that is carrying the S&P 500 to within a percent of its all-time high still has fuel.
Start with what Friday actually did, because the headline index number hides the tension. The Dow added 0.94% and industrials were the strongest sector at 0.95%, with technology close behind at 0.80%. Financials, health care and staples all cleared the index, while small caps managed just 0.11% and energy fell 0.89% with communication services dropping 0.90%. The VIX fell 5.11% to 14.87, the lowest reading of the recent stretch.
When blue chips lead by nearly a full point and the Russell 2000 sits flat, the rotation is not speculative appetite. It is a quality-seeking market expressing confidence in the stronger, more liquid part of the economy and reaching for yield instead of chasing the credit-sensitive laggards. A VIX that low, given what sits ahead, reads as complacency rather than resolution.
That is the near-record posture the week is entering. The Fed hiked 25 basis points in September and signaled at least one more, while core PCE runs at 3.3% against a 2% target. August PCE lands Wednesday with consensus at 0.4% month over month on the headline and 0.3% on the core, both accelerating from July's 0.2%.
The September employment report follows Friday, with consensus at 100,000 new jobs, a sharp step down from August's 162,000, and unemployment expected to tick up to 4.2% from 4.1%. Between the two sits a stretch of 22 Fed speakers with plenty to say about a terminal rate that markets are still groping for. Long-dated Treasuries near their 52-week low capture the bind, where yields near multi-decade highs are the principal pressure on equity multiples and any upside surprise on inflation or jobs reprices that pressure higher.
Which brings us to why Micron is the highest-signal event of the session, not merely the most heavily watched. The memory cycle is the axis on which the entire AI capex trade turns, and Micron does not just report its own quarter; it reports the state of the demand that has been underwriting the AI infrastructure buildout, the strongest argument for the technology leadership carrying the index. A print that delivers on revenue near $50.45 billion and EPS near $31.16 extends the AI infrastructure narrative and gives the tech complex a fundamental reason to hold its premium into a hostile data week. A miss, on the other hand, lands in a market already stretched close to record highs with the calendar turning harder, and that is a poor combination for a sector trading on growth assumptions.
The rest of today's reporters fill in the edges of the same picture. Nike is the consumer discretionary read that matters most, a test of how much spending power still exists beneath the surface of a resilience-driven tape. Accenture adds a services-demand signal, a look at whether the enterprise spending that feeds the broad index is still holding up. Carnival and CarMax round out the day on the consumer credit and leisure demand side of that same story, reading across the softer end of discretionary spend where rates bite first.
The risk case for the week is easy to construct. A hot PCE print Wednesday, a strong payrolls number Friday, and a hawkish Fed speaker in between would together push the terminal rate higher and hit the duration-sensitive and rate-sensitive sectors hardest. That is the scenario in which the low VIX reads as misplaced certainty about an unresolved rate path. The bull case is just as direct: if inflation lands at or below forecast and payrolls cool as expected, a Fed that has already signaled its next move is a known quantity, and equities have room to extend from levels that are strong but not stretched on a sector basis.
So the week resolves on the two prints and the speaker tour, but today it resolves on the memory maker first. QQQ sits 0.6% below its high with technology the second-strongest sector Friday, and Micron is the near-term catalyst that tells you whether that leadership earns its keep. Watch the print tonight, then watch Wednesday's PCE and Friday's payrolls with the same eye on the breadth that has refused to confirm the record. If the data cooperates, the market holds; if it does not, the narrowness that has been the advance's quiet weakness becomes its exposed flank.
Related coverage: See A near-record close that isn't broadening: what the S&P 500's narrow advance is really saying, Goldman Puts 2027 AI Capex at $1.4 Trillion, and $400 Billion of It Will Be Borrowed, and Growth led, then the 5% 10-year took the floor: a rate-shock rotation under thin breadth for the internals behind this earnings-season setup.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.Sources: Yahoo Finance market data retrieved September 28, 2026; Trading Economics week-ahead forecasts; Investing.com earnings calendar.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.