Claims, PCE and Micron: Three Prints That Decide the Week

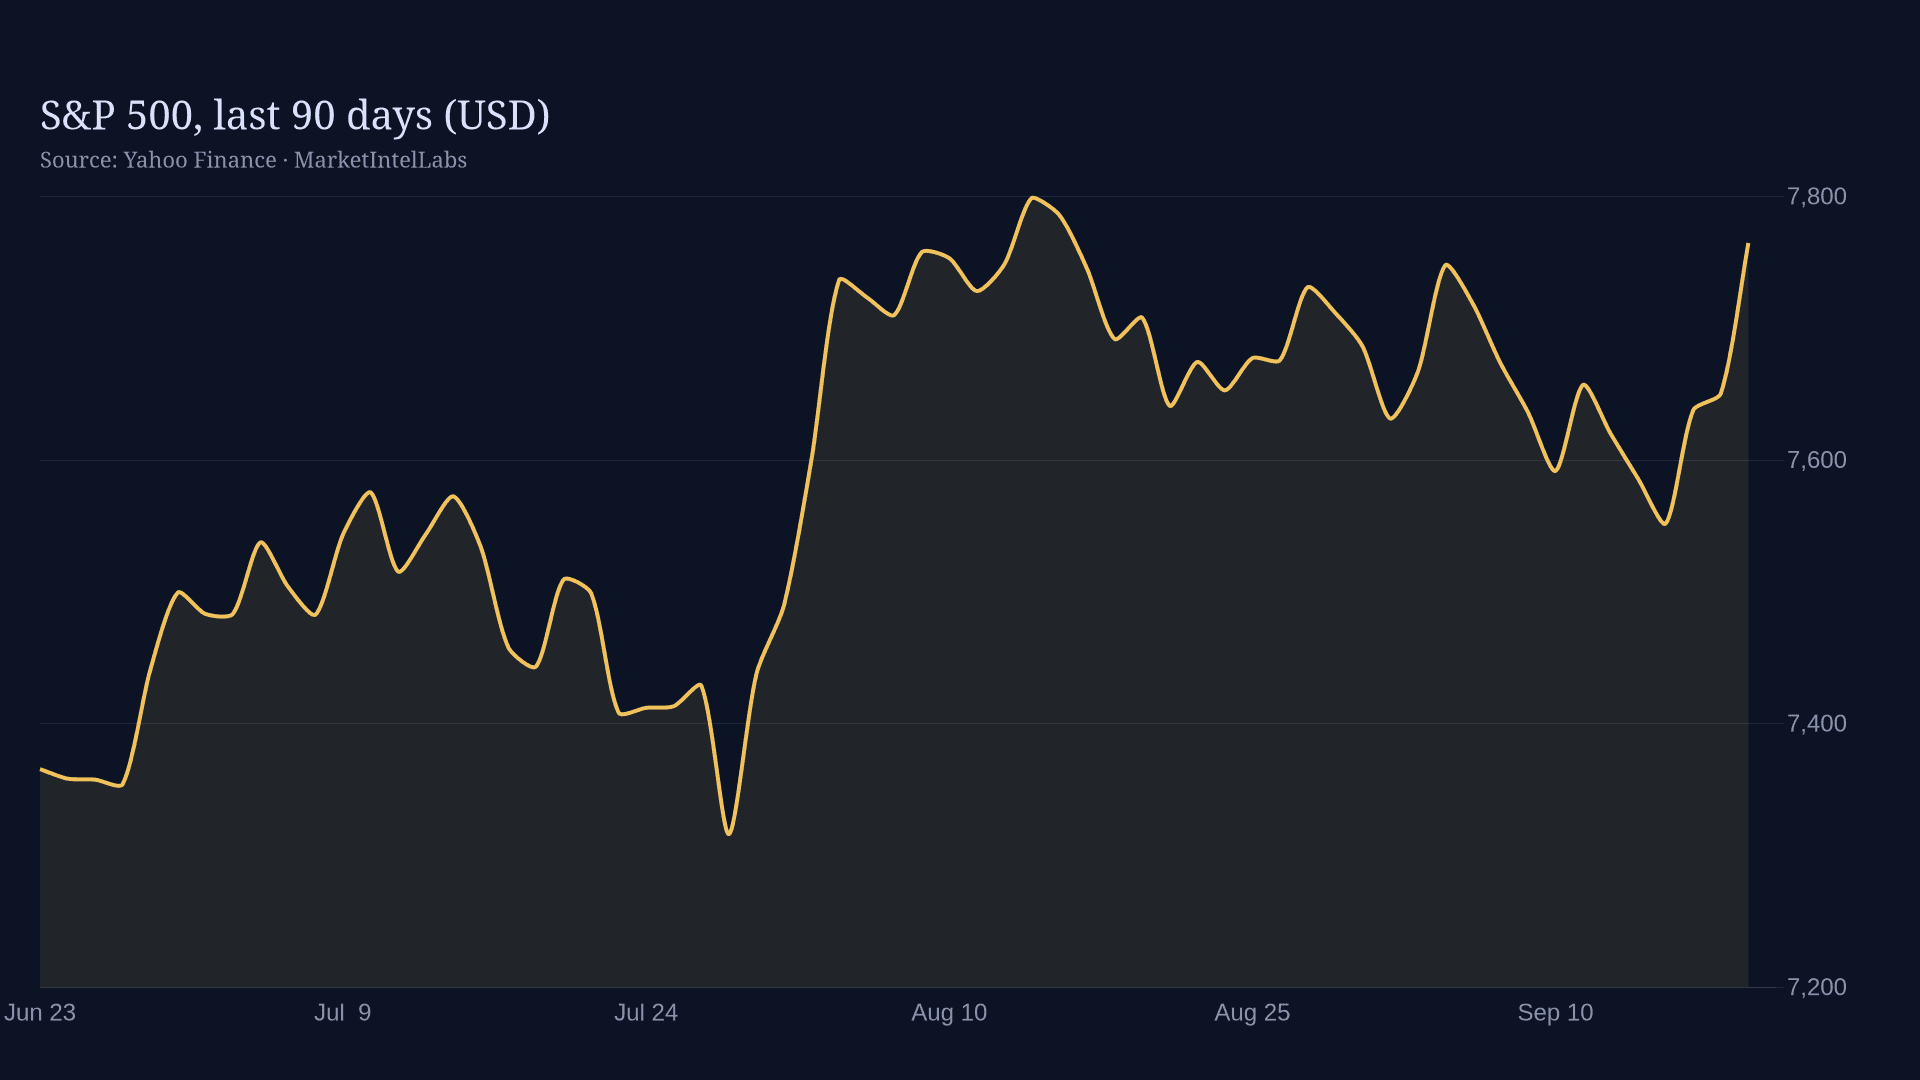
A tape this narrow does not need much to crack. On Tuesday the S&P 500 closed flat at 7,764.64 while the Nasdaq 100 set a record at 30,732.40, up 0.82% on a semiconductor-led bid in which Micron jumped 5.00% and the SMH fund rose 1.92%. The equal-weighted S&P gained just 0.04%, which is the real read: a handful of growth names are carrying an index that few other stocks are helping. With the VIX compressed to 14.21, down 4.44%, the setup going into the next six days resembles the narrow-tape setup I flagged Monday, the same kind that tends to end quietly or violently, depending on the numbers that land.
Thursday morning brings the first catalyst. Initial jobless claims for the week ended September 12 came in at 196,000, below consensus, per Reuters, extending the payrolls-survey-week claims read we covered in depth. A repeat in that range keeps the labor market out of the rate conversation. A hot surprise would push short-dated rate expectations higher and pressure a market already facing a 10-year yield that has probed 5.0% and a Fed that hiked to a 3.75%-4.00% target on September 16, with 16 of 18 officials projecting at least one more move by year-end and October’s Fed meeting is a coin toss on the autumn path.
September 30 stacks three events on top of each other. That morning brings the BEA's third estimate of Q2 GDP and August PCE, both at 8:30 ET. Core PCE consensus runs around 3.3% to 3.4% year over year, based on the prior reading from August 26. The Fed targets PCE, so a number above that range re-raises expectations for another hike and would sting the yield-sensitive and rate-sensitive corners of the tape that already lagged on Tuesday. These prints are forecasts until their release time passes; nothing here is confirmed until the data is out.
Micron also reports fiscal Q4 on September 30, with consensus sitting near $31.30 in EPS on about $50.6 billion in revenue, per Intellectia and the Fool. Because Tuesday's advance was built on semiconductors and AI names, Micron is the week's pivotal single name: a strong number reinforces the memory and AI bid, tied to the AI capex cycle, that is holding the index up, while a miss would hit the exact stocks carrying it. A weak print does not end the sector's run, but in a low-volume, low-VIX tape it can start a quick shift out of leadership.
The through-line is that Tuesday's flat index did not resolve anything; it just set up the week. Watch Thursday morning's claims for the first signal, then the September 30 trio of GDP, PCE and Micron. Reassuring prints extend the narrow bid, and hot ones test how much momentum a thin market can actually support. The data, not the rally, decides which. This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.