Meta Earnings Preview: A $130-145B Capex Guide Frames Q4

The print that frames the fourth quarter lands Wednesday at 20:30 UTC, when Meta Platforms reports third quarter results against a 2026 capex guide of $130 to $145 billion. The revenue and margin shape of the week's other big reports is already known; what the market is waiting on is whether that capital spending guidance narrows or widens into a quarter that loans were priced against.
Earnings that move the week
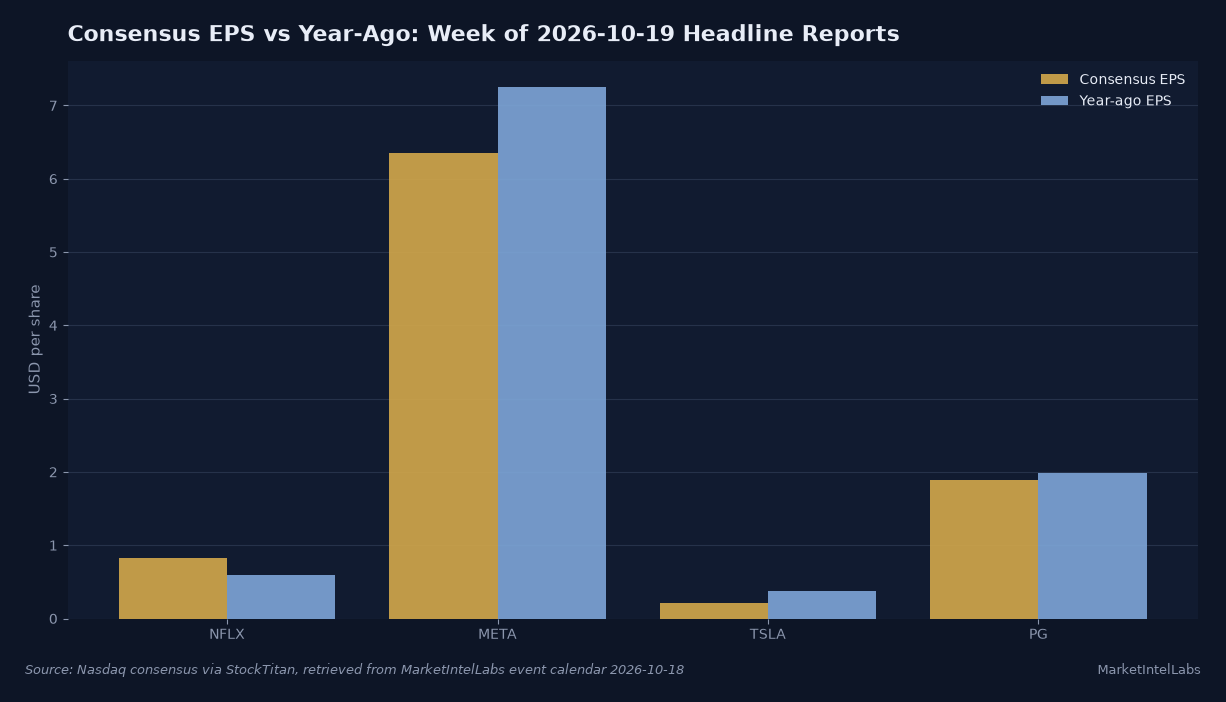
Meta is the anchor. At a near $1.88 trillion market capitalization it is the single largest report on the calendar, and the capex number is the reason. A $130 to $145 billion 2026 capital spending guide is the community-built consensus that every AI funding model in the sector leans on, and the 5.1% 10-year Treasury that the macro desk has been tracking changes the arithmetic underneath it. Capex is a multiyear commitment funded by cash flow and borrowings; at a 5.1% hurdle the marginal dollar of AI spend has to clear a higher cost of capital, which is exactly the credit-wall tension the weekend brief flagged. The earnings consensus at $6.35 sits some ways below the $7.25 earned a year ago, which tells you the market already expects the spending to compress margin. The live question is whether Meta restates the guide up, holds it, or walks it inward into Q4.
Related reading: PPI, Retail Sales and Jobless Claims Due Today: Three Prints Test the Fed's 37% October Hike Odds.
Netflix comes first, Tuesday at 20:01 UTC, and it is a cleaner setup. Consensus EPS of $0.82 compares with $0.59 a year ago, and the company has already guided revenue to $12,860 million, up 11.7% year over year, with an operating margin of 33.2%. The novelty this quarter is people, not numbers: after a change in the chief content officer, the market wants to hear how the content strategy resets, and whether subscriber additions surprise on the high side. Charted against the rest of the week, its consensus-to-prior spread is modest; the subscriber conversation is where the move would come from.
Tesla reports less than an hour after Meta, at 21:30 UTC, but the deliveries were disclosed October 2: 486,532 vehicles, up 1.3% quarter over quarter from 480,126. Consensus EPS of $0.21 versus $0.37 a year ago means the headline count is not new information. The webcast at 5:30pm ET is where margin and cash flow get their detail, and given a cut in year-ago earnings per share of nearly half, the margin print is the swing factor rather than unit volume. Procter and Gamble rounds out the headline set Thursday at 12:30 UTC with EPS consensus of $1.89 against $1.99 a year ago; its full-year organic sales growth guide of 1 to 3% is the bar the defensives watch.
Related reading: Costco, Darden and KB Home Put Post-Fed Demand to the Test.
Data and the watch-points
The data calendar is thinner than the earnings one, which is why the prints will carry more weight. Tuesday at 12:30 UTC brings September housing starts and building permits from the Census Bureau, the first read on whether residential construction is absorbing a mortgage rate that has stayed elevated into the fall. Thursday at 12:30 UTC delivers weekly initial and continuing claims from the Labor Department for the week ending October 17, the freshest labor market pulse ahead of next month's jobs report, followed at 16:00 UTC by the Freddie Mac weekly mortgage rate survey that ties the two housing threads together.
Across our four sectors the week reads as one macro trade. In equities, volatility should build into the Tuesday to Wednesday stack, when Netflix prints in one session and Meta and Tesla land back to back the next; index levels will swing on how those three dispose of an already-rich growth tape. In commodities, Brent holding above $100 with Hormuz disruption stays the undercurrent, and Meta's server buildout is the clearest industrial-demand leg into the complex, while Tesla's print is a chip and battery cost story more than a metals one. In crypto, bitcoin enters the week as the liquidity proxy it has been for most of this cycle, so the 5.1% yield and the AI capex question are the drivers to watch rather than any weekend tape.
Related reading: S&P 500 Sits Near a Record With Only 26% of Stocks Above Their 50-Day Average: The Capped-Breadth Rally.
What would surprise the consensus
Meta's capital spending guide is the binary risk of the week, and the answer only arrives live on the call at 4:30pm ET Wednesday. The scenarios are wide: a guide revision upward re-anchors the whole AI trade, a hold keeps the current narrative, and a walk-in remaps Q4 cost assumptions for everyone who has priced in relentless buildout. Netflix surprises if the post-CCO content reset produces a subscriber surprise on top of an in-line quarter, since the guide is already out. Tesla surprises on the margin print rather than deliveries, given the volume is disclosed. And for Procter and Gamble the market is not looking for a beat as much as for clarity that the 1 to 3% organic sales bar still stands; a guide hold is the win, a cut is the event.
Two-wars dashboard
Two-wars dashboard: Hormuz transits (daily) 1 vs 85/day baseline; Brent settle 104.32 $/bbl; ULSD (HO) crack vs Brent 92.44 $/bbl; EU diesel price y/y 38%; Russian refinery crude runs 3.8 mb/d (June; ~30% below year earlier); EU gas storage 70.6%; Ukraine agricultural exports, August (all routes) 1.48 Mt (-48.6% MoM; Odesa ports 152,126 t, -93.6%) (oldest figure as of 2026-09-11).
Related reading: Q3 Bank Earnings Open Mixed as JPMorgan Misses, Goldman and Citi Beat.
The week settles in three acts: Netflix Tuesday, the Meta and Tesla stack Wednesday, and the data and P&G follow-through Thursday. The number that ties them all together is Meta's capex guide next to a 5.1% 10-year, because that is the one print still capable of repricing growth across equities, commodities and crypto at once. That question is unresolved heading into the open, and the answer lands with the market's calendar Wednesday afternoon.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.