Two-thirds October hike odds face the PCE and payrolls test

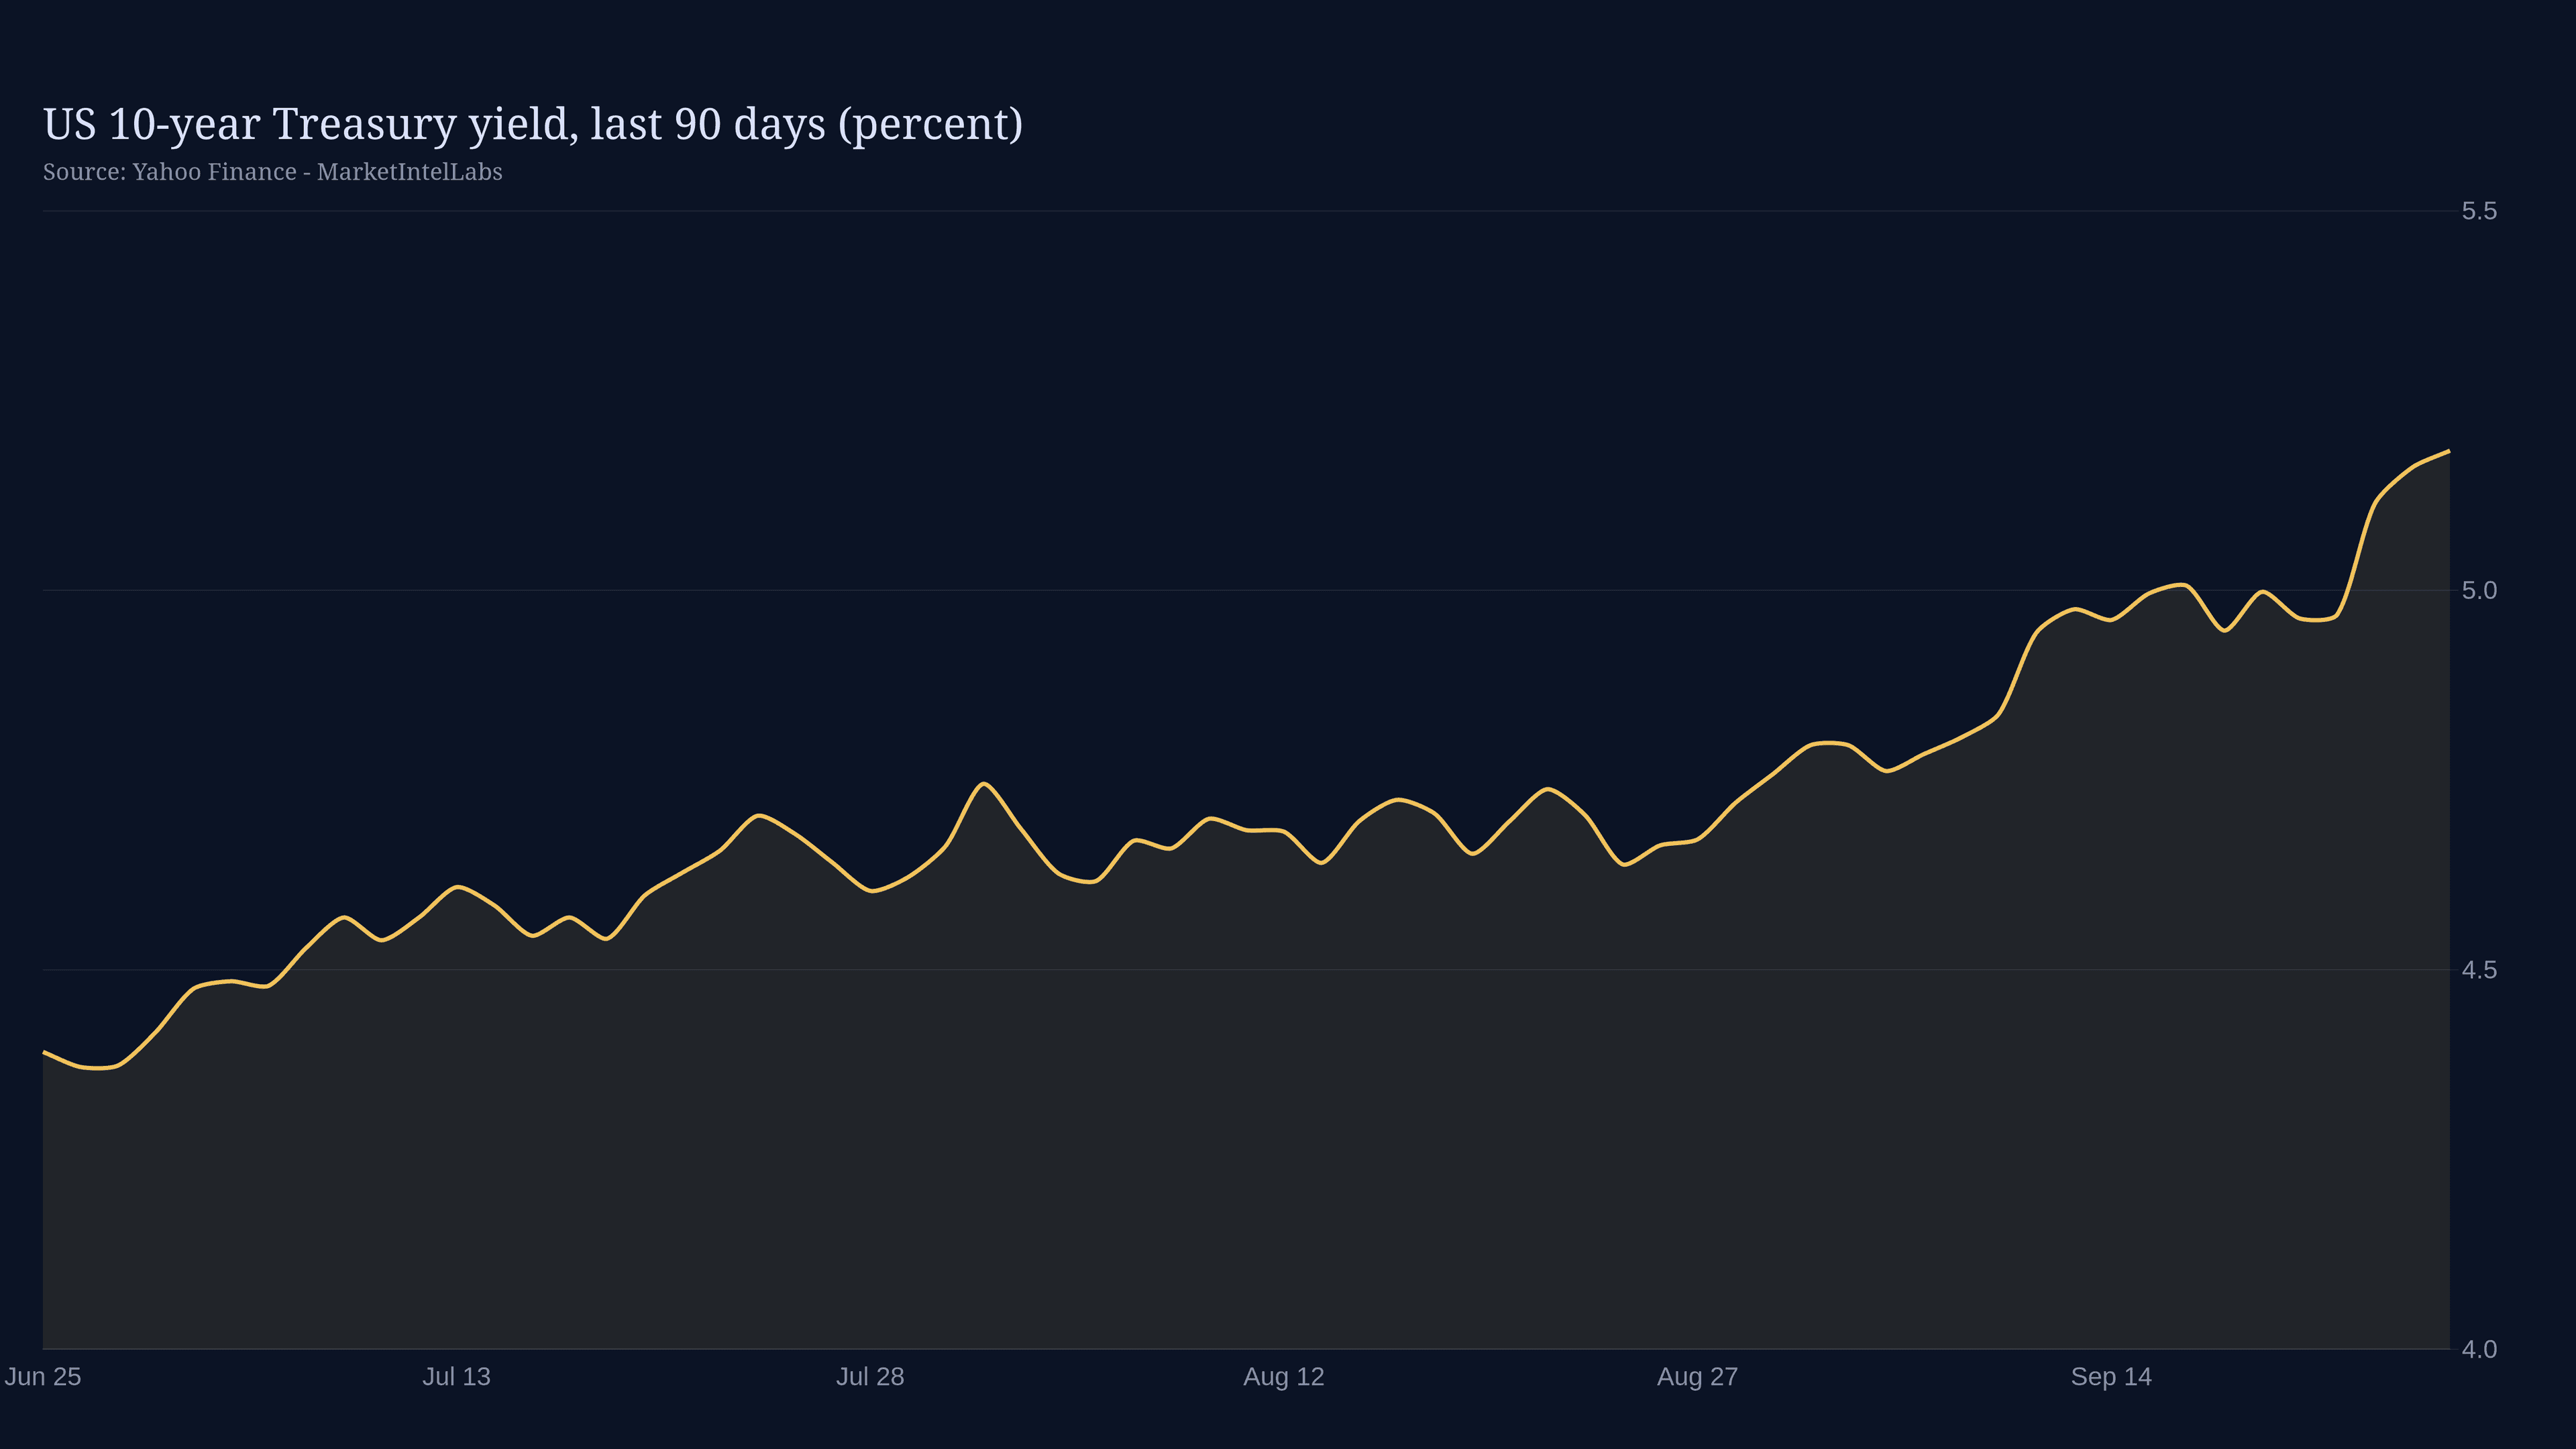
The final week of Q3 opens with the market carrying unusually firm odds that the Federal Reserve hikes again on October 28. Implied probability of a 25 basis point move at that meeting is running near two-thirds across prediction venues, Polymarket at roughly 65 percent and Prime Terminal and FXStreet sources at about 64 percent, per the research desk. Two prints will do the most to decide whether that repricing holds, and they land back to back: core PCE on Wednesday and the September employment report on Friday. Both sit close enough to a knife that the swing in either direction is what traders will actually trade this week, not the consensus number itself.
Related reading: What the August PCE Report Means for the Fed's Next Move, Kalshi Puts the October Fed Hike at Two Thirds and the December Ladder Agrees, and Fed Funds 3.88%, 10-Year 4.96%: Claims Today and PCE on Sept 30 Reprice October. For the broader backdrop, see our Fed policy coverage.
Start with where the regime stands. The FOMC raised the federal funds target to a 3.75%-4.00% range on September 16, a unanimous 12-0 vote and the first hike since 2023, and its projections showed 16 of 18 policymakers expecting at least one more increase this year, per the Fed's statement and CNBC. That repricing did not happen in a vacuum.
It sits on top of an energy-led inflation impulse: Brent near $106 a barrel, US diesel above $200, and the IEA's September Oil Market Report projecting 2026 world oil supply down 5.7 mb/d with over 10 mb/d of Gulf output still shut in. A supply shock of that size is exactly the case where more tightening cannot conjure the barrels, which is why the committee's credibility is the variable actually at stake over the next two weeks.
Wednesday carries the inflation half of the test. Consensus looks for core PCE at +0.3% month over month, per the TradingEconomics week-ahead calendar, with headline at +0.4% and the core running near 3.3% year over year, comfortably above the 2% target.
Because the Fed has already hiked once, the market's reaction function has inverted: a core print roughly in line is not reassurance, it is fuel for the October-or-pause debate. Anything above the 0.3% consensus hardens expectations of another move, and a downside surprise is the cleanest relief valve for a curve with the 10-year near 5.2%, its highest since 2007, against a firm dollar holding near 101, its strongest in two months. Wednesday also brings ADP and the final Q2 GDP reading, both of which matter less for the hike question than for the tone heading into Friday.
Thursday offers texture before the main event, with ISM manufacturing and JOLTS job openings on the same day. Neither is the decision-maker on October, but JOLTS in particular feeds the same question the employment report does on Friday: is the labor market cooling enough to argue policy is already restrictive, or is it firm enough to let the Fed justify following through?
Friday is the bigger swing. Consensus looks for September payrolls at +100k versus a +162k print in August, with the unemployment rate seen rising to 4.2% from 4.1%, per TradingEconomics. The named market estimates skew the same direction.
KXPAYROLLS puts roughly a 50% chance the print lands below the +100k consensus, about 35% at or near it in the 100k to 140k band, and only about 15% above 140k. KXU3 sees about a 55% chance the unemployment rate prints 4.2% or higher. That downside skew is the tell: continued labor-market cooling under restrictive policy and an energy shock is the base case these markets are pricing, and a print that merely matches consensus is not automatically hawkish fuel.
Here is the asymmetry worth holding. A genuinely hot PCE or a strong payroll number hardens the two-thirds October odds and pressures equities sitting at record-close proximity, with SPY near $771 against a $779.37 52-week high, an environment with thin cushion for a positive inflation or jobs shock. A soft labor number, by contrast, reframes the Fed as close to done, relieving the real-rate pressure that has kept gold lagging even as oil climbs and lifting the case for a pause.
December pricing also diverges across sources at a material spread, Polymarket near 68 percent versus Prime Terminal near 93 percent, a low-confidence input that itself tells you how unsettled the full path beyond October remains. Watch Wednesday's core print against the 0.3% consensus, Friday's payrolls against the 100k line, and the KX pins for where traders already lean.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.