Fed Funds 3.88%, 10-Year 4.96%: Claims Today and PCE on Sept 30 Reprice October

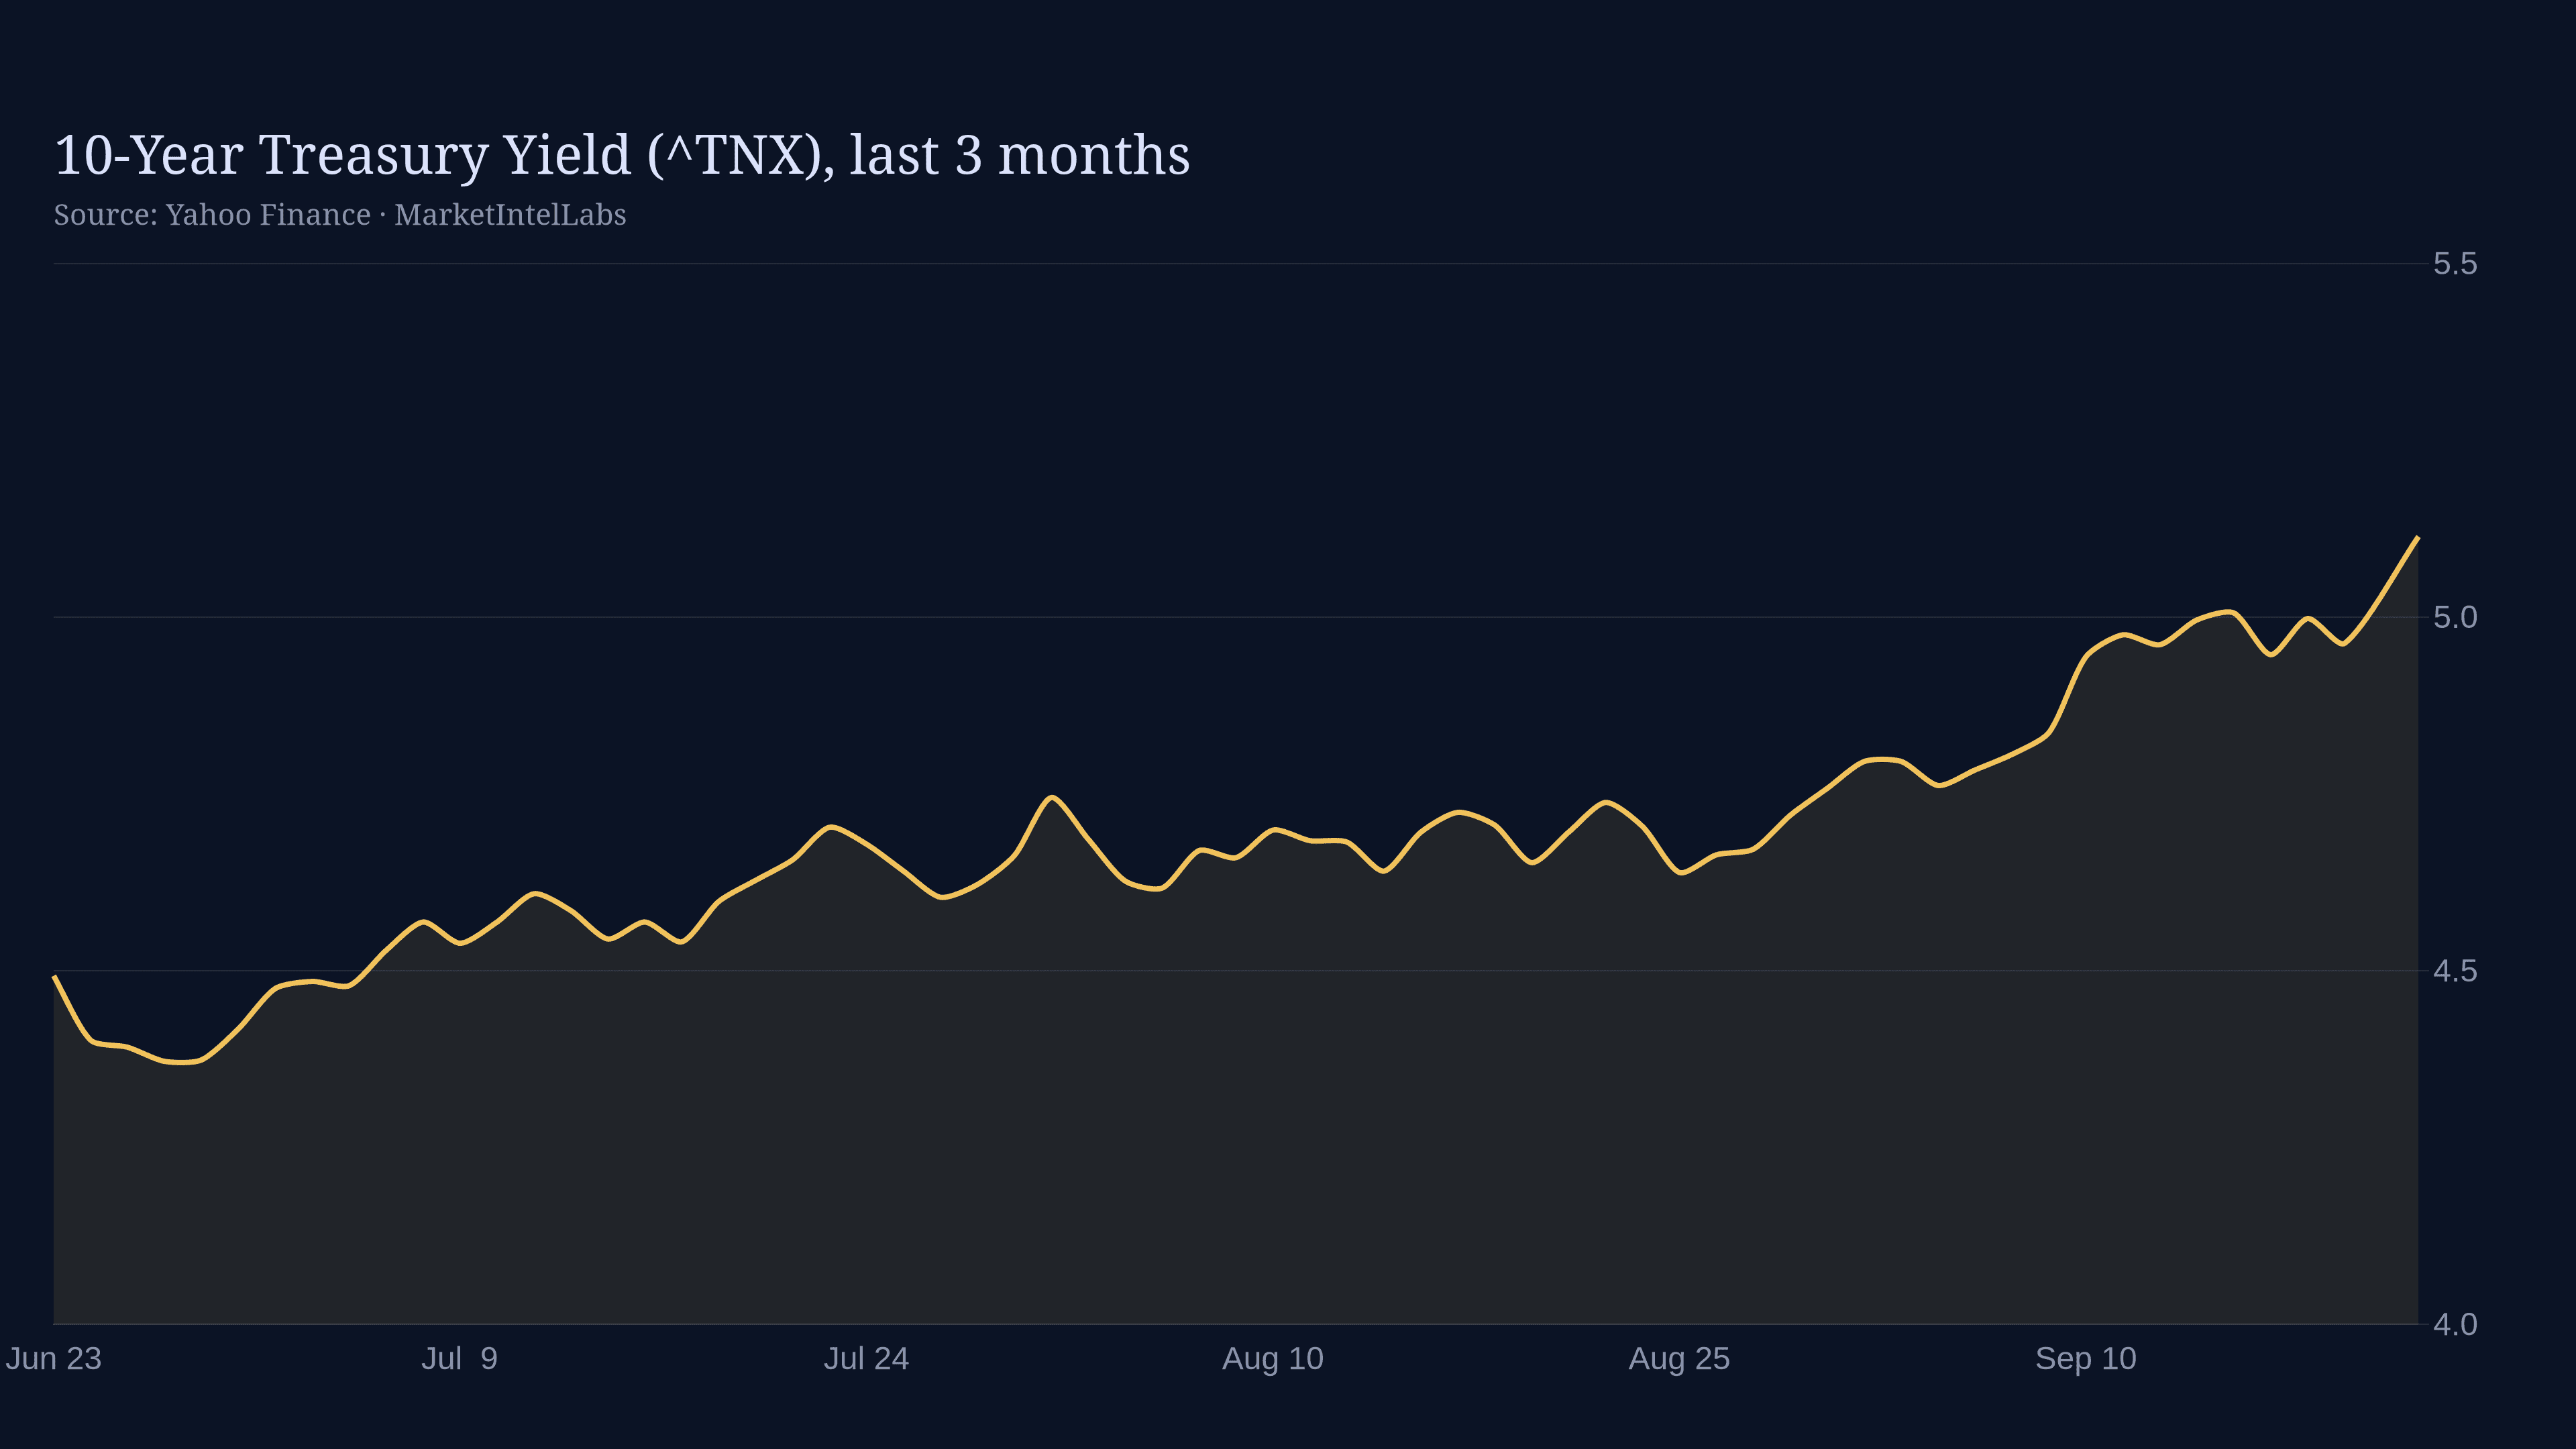
The Fed's next move now parks on two numbers this week. Today's jobless-claims print and the August PCE report due September 30 will tell markets whether the dot plot's “one more hike” actually lands at the October 27-28 meeting, or whether the hawkish repricing that followed the September 16 rate rise has already overshot.
The FOMC raised its target range a quarter point to 3.75%-4.00% on September 16, a unanimous 12-0 vote and the first increase since 2023, with the statement citing inflation that “remains elevated.” The mechanics confirmed the move: the daily effective fed funds rate stepped to 3.88% from 3.63%, per FRED, and the short end repriced with it. The 2-year has climbed to 4.71% and the 10-year to 4.96%, leaving the curve barely positive at a 10y-2y spread near +0.26% according to FRED data. That is the backdrop every print this week lands against.
Today's claims: the first read on the labor side
Weekly initial claims are due today at 12:30 UTC. The published consensus is 201,000, a step up from the 196,000 prior week, but the distribution has been narrow for a month: claims have printed between 196,000 and 209,000 over the past five weeks. Unemployment sat at 4.1% in August. A print on the soft side of consensus is the tariff the market assigns to the hikes being done. A strong number near or below the recent range does the opposite, it keeps the Fed's lane clear to prioritize price stability, which is where the Committee already put it.
September 30: PCE and GDP settle the October question
The bigger catalyst is August PCE, out September 30, alongside the Q2 GDP third estimate. The Cleveland Fed's nowcast, updated September 4, points to headline PCE near +0.35% month over month and +3.80% year over year, with core near +0.27% month over month and +3.40% year over year. Headline CPI already ran +3.35% year over year in August, a 0.40% monthly gain that marked a step up from July, so the PCE read is the confirmation or the contradiction of that re-acceleration. If core PCE comes in at or above the nowcast, the case for a second hike strengthens materially. If it prints below, hawkish expectations fade quickly.
What would move in each scenario is where the levels matter. Rate-sensitive growth has been the pressure point; in the session the brief captured, SPY fell 0.72% and QQQ 0.84%, the market pricing higher-for-longer against a 4.71% 2-year. Precious metals took the sharper hit on the opportunity-cost math, GLD off 1.80% and SLV down 4.23%. The near-term reads on the brief's asset signals are bearish for equities with medium confidence and neutral for gold and silver, until the PCE print sets direction. The medium-term case for metals is not broken: M2 is back to +5.66% year-over-year growth, a liquidity backdrop that historically supports hard assets once the initial hawkish shock is absorbed.
Both sides need an honest airing. The bear case for duration and metals is that growth stays firm, claims stay low and inflation re-accelerates, so yields stay elevated and a second hike lands in December if not October. The bull case is that this hike is late-cycle and near-terminal, that disinflation resumes through base effects, and that a liquidity-expanding M2 backdrop underpins real assets once the shock matures. On the data at hand the edge near term is with the bears; over the medium term it tilts back to the bull side. Either way, expect the range in the days around the PCE print to be wider than the week's early tape suggests. The front end has already repriced, so the next repricing needs a new number, and September 30 is where that number comes from.
Everything that has happened so far this month is priced. The question the market is actually trading this week is whether the data confirms the dot plot or calls its bluff.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Related reading: our Fed policy coverage, After the Fed's First Hike Since 2023, Two Prints Decide Whether October Follows, October's Fed Meeting Is a Coin Toss on Prediction Markets, The Fed's 25bp Hike to 4% Puts Cash on Top Until August PCE
Sources
Federal Reserve, “Federal Reserve issues FOMC statement,” Sept 16, 2026 (federalreserve.gov). FRED, Federal Funds Effective Rate and Treasury constant-maturity yields (DFF, DGS10, DGS2), Money Supply M2 (M2SL) and CPI (CPIAUCSL). Investing.com, initial jobless claims calendar (investing.com). Federal Reserve Bank of Cleveland, Inflation Nowcasting (clevelandfed.org). Bureau of Economic Analysis, release schedule (bea.gov). Yahoo Finance quotes for SPY, QQQ, GLD and SLV, retrieved 2026-09-24.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.