IFM Investors to Buy Majority Stake in Associated British Ports in $13.4 Billion Deal

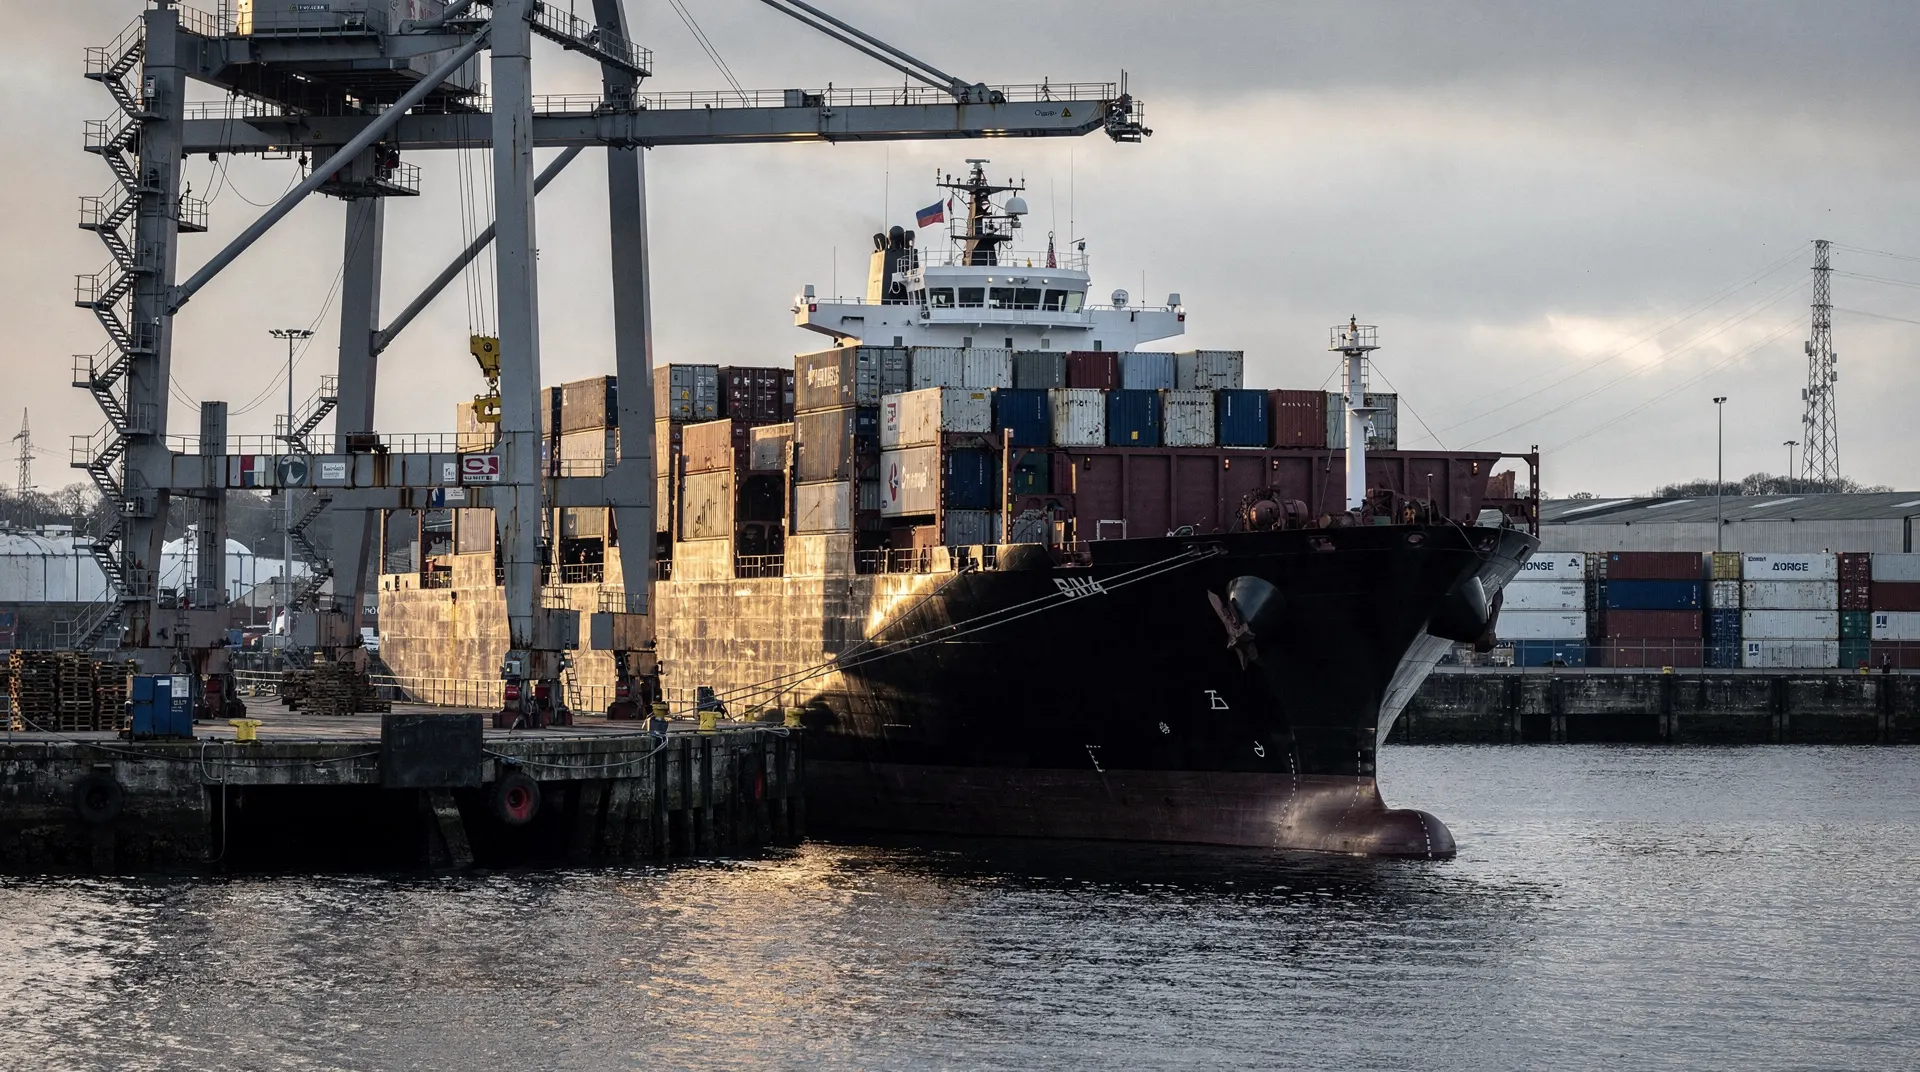
IFM Investors, the Australian and UK pension fund backed manager, has agreed to buy a 63.9 percent majority stake in Associated British Ports, the UK's largest port operator, in a deal that values the company at roughly 10 billion pounds, or about $13.4 billion. The transaction is among the UK's largest of 2026 and hands a critical piece of the country's trade infrastructure to a new long-term owner.
The valuation was put at approximately 10 billion pounds, about $13.4 billion, according to people familiar with the deal as reported by Bloomberg and the Financial Times. That figure places ABP among the most valuable transport infrastructure assets to change hands in the UK this year, and it validates two decades of ownership stretching back to when the port group was taken private.
Related reading: SpaceX Stock Price Slips to $147 as Q3 Earnings Due After Tuesday Close.
The structure of the transaction is direct. Canada Pension Plan Investment Board, often called CPP Investments, agreed to sell its entire 33.9 percent holding, while OMERS, the Ontario Municipal Employees Retirement System, agreed to sell its 30 percent stake. Together those two blocks form the 63.9 percent majority that IFM will control, giving the Melbourne based manager operational influence over a sprawling network of docks, rail connections and industrial land.
Associated British Ports is not a typical logistics company on a map. Its 19 facilities sit at the junction of the UK's seaborne supply chain, handling about a quarter of all the country's seaborne trade, according to reports from the Financial Times and gCaptain. That reach extends beyond cargo. The company also hosts more than half of the UK's offshore wind capacity at its ports, making it a landfall point for the energy transition as well as a goods gateway.
Related reading: IonQ Stock Falls on $1.3B Elisity All-Stock Deal.
For IFM, the appeal is the rare combination of a regulated, inflation-linked earnings base and a central role in two structural themes: the physical movement of goods and the buildout of offshore wind. Ports charge for cargo volumes, and UK trade flows are sticky, which gives an infrastructure owner exposure to economic activity without the volatility of shipping rates themselves. The asset fits squarely in the category that pension capital has favored for a decade: long-dated, cash-generating, and tied to real-world demand.
Twenty Years of Canadian Ownership Comes to an End
The seller side of the deal is as telling as the buyer. CPP Investments and OMERS have held their stakes in ABP for roughly two decades, a long arc for private equity adjacent pension holdings in a single asset. Their exit is not a fire sale. It is a realization, the cashing out of a position that has compounded through multiple UK port and rail cycles, and it suggests these funds see the value of holding a majority port owner near a cyclical peak rather than ahead of a regulatory clock ticking on new ownership.
Related reading: Schneider Electric to buy PTC for $22.6 billion in record all-cash deal.
The departure also raises a question about Canadian pension appetite for transport assets more broadly. After years as aggressive owners of UK and European infrastructure, CPP and OMERS choosing to rotate out of a flagship transport holding may signal a preference shift toward newer assets, technology, or digital infrastructure, or simply a desire to recycle capital. One large move is not yet a trend, but infrastructure watchers will read it as a signal about where those funds want their next decade of exposure.
The Bull Case and the Risks on the Other Side
The bull case for infrastructure consolidation starts with scale. A single owner holding a 63.9 percent stake can move faster on capital spending, coordinate investment across ports, and commit to the multi-year offshore wind buildout that a fragmented shareholder base might leave underfunded. IFM, with roughly $157 billion under management, brings the balance sheet and the patient mandate that port infrastructure requires, and its pension ownership structure aligns with ABP's very long asset life.
Related reading: Salesforce Braze Deal: $5.66B All-Cash Acquisition Sends Braze Stock Up 51%.
The risk case is execution and politics. Ports are politically visible and strategically sensitive, which is precisely why the deal faces a UK national security review alongside normal shareholder and regulatory approvals. A review can come with conditions, and in a year when governments have grown more protective of critical infrastructure, there is no guarantee the transaction closes exactly as structured. There is also integration risk. IFM is a large investor, but a majority operating stake in a 19 port network is a different operating burden than a passive fund position, and any misstep on labor, planning, or regulatory relations could erode the very cash flows that justify the price tag.
For the infrastructure and shipping sectors broadly, the deal is evidence that ports remain a destination for institutional capital even as rate volatility and trade-policy uncertainty swirl around the industry. ABP's strategic position, half a country's offshore wind and a quarter of its seaborne trade rolling through one operator, is hard to replicate, which is exactly why a $13.4 billion price could clear the bar.
What to Watch Next
The next dated catalyst is the review process. The transaction remains subject to shareholder and regulatory approval, including a national security review, and is expected to close in the first half of 2027. Watch for conditions attached to the national security clearance, the timeline of the shareholder vote, and whether either Canadian fund discloses where the proceeds are headed. For equity investors, the signal is less about ABP itself, which is private, than about what the deal says for the valuation of listed ports, logistics operators and pure infrastructure plays that sit in the same strategic lane.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.