October Hike Odds Jump 14 Points on the Barr Speech
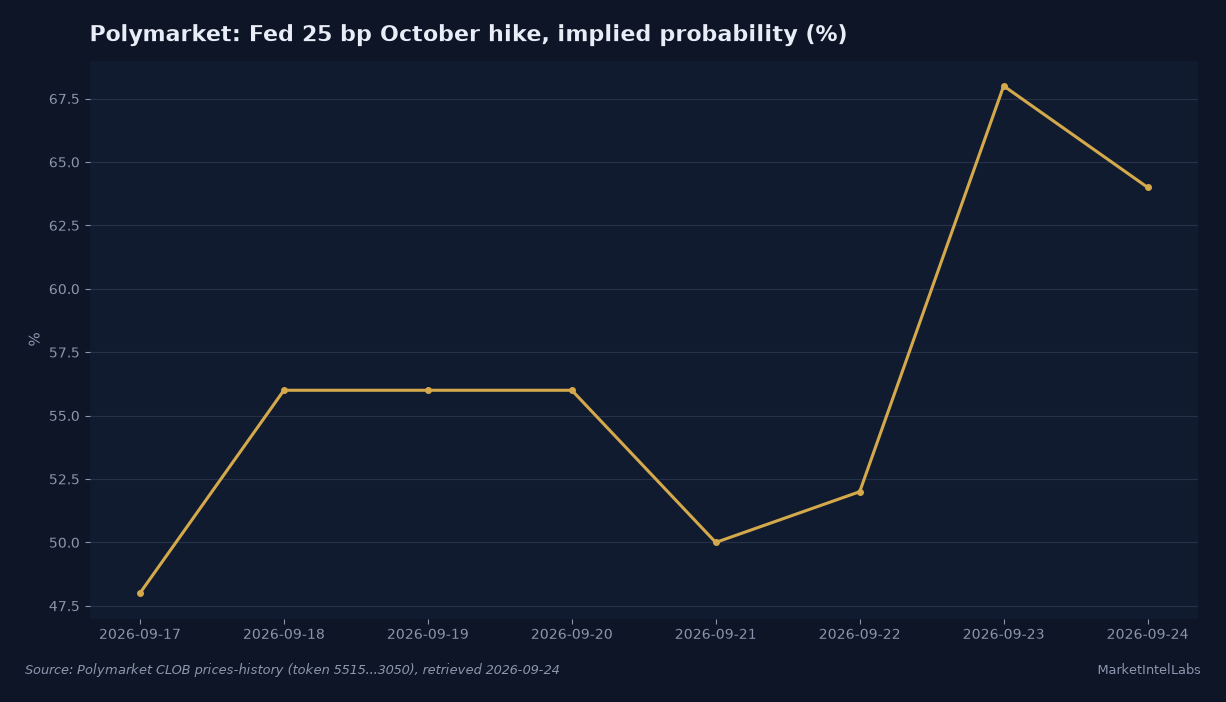
Polymarket put a 25 basis point Fed hike after the October 28-29 meeting at 64.5 cents on Thursday, September 24 at 07:45 UTC, up from 53.5 cents 24 hours earlier and as high as 69.5 cents in the immediate aftermath of Governor Michael Barr's Chicago speech on September 23. The no-change contract fell to 34.5 cents from 45.5. Roughly 360,000 dollars traded on the hike contract in the 24 hours to Thursday morning so far, the heaviest volume in Polymarket's Fed strip this week, and the reprice so far is worth about 14 probability points.
What moved the market
The move happened between 13:10 and 15:10 UTC on September 23, in the window after Barr's prepared remarks to the Chicago Fed's housing affordability summit hit the wire. Polymarket's contract on a 25 basis point October increase went from 53.5 cents to 68.5 cents inside two hours and touched 69.5 cents at 15:10 UTC. It settled back to 64.5 cents overnight. Barr, a governor who votes on rate decisions, said the Fed was "out of position" before last week's hike and that "in my base case, further policy adjustments are likely to be needed to ensure inflation comes down to target in a timely fashion." He added that risks to the inflation target have increased while risks to the labor market have receded.
Boston Fed President Susan Collins posted the same day that she supported the September 16 quarter-point hike and now sees "an increased likelihood" of scenarios in which inflation remains "notably" above the 2% target. Two voting Fed officials restating a willingness to tighten within 24 hours was enough to strip about 11 points off the odds that the Fed holds in October.
The cross-check
The conventional instruments agree with the event markets. The 2-year Treasury yield traded near 4.42% on September 24 per Yahoo Finance data, and the 10-year near 5.11%, both consistent with a market pricing more tightening rather than less. Kalshi's Fed ladder prices the same path from the other end: the October contract on the upper bound finishing above 4.00% bid 66 cents and asked 70 cents on September 24, which is roughly a two-thirds probability of at least one more hike this year, matching Polymarket's 64.5 cents within the spread.
December is where the ladder gets specific. Kalshi's December rung above 4.25%, which requires a second consecutive 25 basis point move, traded at a 49 to 54 cent spread on September 24. A second hike is close to a coin flip, up from the single-digit odds on further tightening that the December ladder carried before the September 16 decision. Our own desk piece on September 23 covered the earlier leg of this repricing, when the December ladder first put a second hike at 42%; one day and one Barr speech later, the market has added roughly another 7 to 9 points.
Liquidity is doing real work here. The Polymarket hike contract carries about 720,000 dollars of liquidity and nearly 3.0 million dollars of cumulative volume, so a 14-point move is a large repricing in a market that does not move on thin tape. The bid-ask spread sat at 64/65 cents on Thursday morning, one cent wide, meaning the quoted probability is a price, not a stale print. The 50-plus basis point rung trades at about 1 cent and the cut rungs below 1 cent, so the entire risk is concentrated in the single 25 basis point outcome, which is itself information: nobody is paying for a larger move or for easing.
The venue agreement matters more than either number alone. Kalshi and Polymarket run different order books and different participants, and on September 24 both put the October hike in the mid-60s with the residual spread accounted for by the size of the move. Divergence between the two venues has been a better tell in past Fed cycles than either level.
The October 28-29 FOMC decision settles these contracts, and the September jobs report and the October 13 CPI release are the two dated events left on the tape before the blackout. The September 16 decision was unanimous and the projections showed 16 of 18 officials expecting at least one more hike this year, so the desk's read is that the market is converging on what the Fed's policy framework itself signalled, not getting ahead of it. The next leg of information arrives with the next inflation print; the CPI contracts on Kalshi and the breakeven market will reprice first, and the Fed ladder will follow them.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.