Suez Transits Jump 17% and Asia-Europe Rates Break First
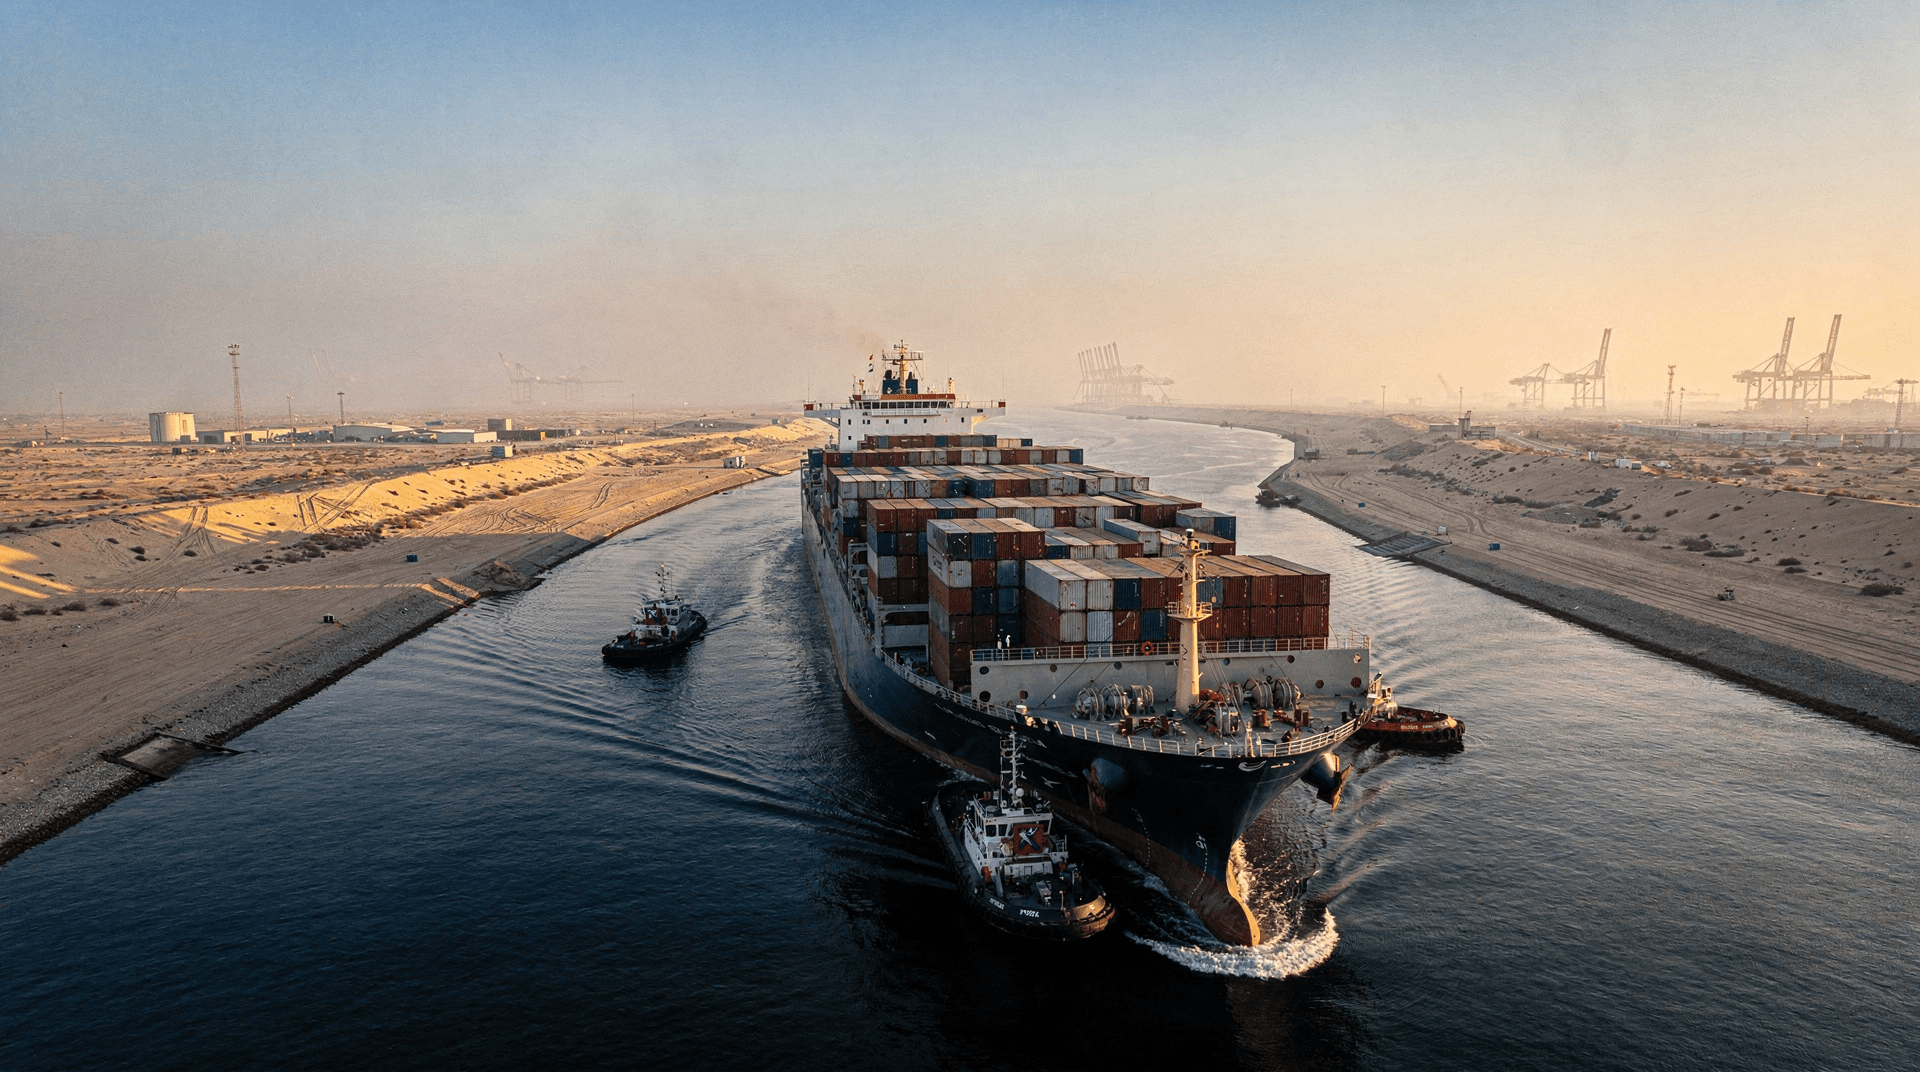
Suez transits jumped from 41 to 48 in the space of a week, and the lane that change hits first is already breaking. Drewry's World Container Index assessment for Thursday 24 September 2026 put the eight-lane composite down 1 percent at $4,468 per 40-foot container, entirely because of Asia-Europe: Shanghai to Genoa fell 5 percent to $3,835 and Shanghai to Rotterdam fell 4 percent to $3,485. On the Transpacific side, Shanghai to Los Angeles rose 2 percent to $7,838 and Shanghai to New York held at $10,373, within reach of the $10,394 peak from the 22 September print. One canal, two directions.
Capacity is returning faster than carriers can withdraw it
The mechanism is arithmetic. Carriers announced 15 blank sailings for next week, up from 9 this week, on the Transpacific, and 7 on Asia-Europe, up from 3. Normally that pulls rates up. This week it did not, because the Suez return is adding effective capacity on the Europe trade at the same time. Each voyage routed through the canal instead of the Cape of Good Hope shortens the round trip by roughly ten days, which puts the same ship back on the lane a full extra rotation per quarter. Drewry's own reading is that recovering effective capacity outweighs the blank sailings, and it expects Asia-Europe rates to keep declining next week.
The return is deliberate and dated. Maersk and Hapag-Lloyd said on 14 September that four more Gemini services would move from the Cape back to Suez, with first westbound sailings on 19 September for AE11, 21 September for AE5 and 24 September for ME2, according to the carriers' announcement and Linerlytica's tracking. Evergreen, ONE, HMM and Yang Ming had yet to return as of 14 September, which means the capacity arriving through the canal so far is a fraction of what is scheduled. The Strait of Hormuz has been effectively closed to container shipping since 28 February 2026, so the Gulf leg of the disruption persists; the Red Sea leg is the one unwinding.
The split since July tells you which lane absorbs it
Put the two trades side by side and the divergence is stark. Since 30 July 2026, Shanghai to New York spot is up 37.2 percent and Shanghai to Los Angeles is up 34.3 percent, driven by pre-Golden Week demand, carrier capacity management and record US import volumes. Over the same window Shanghai to Genoa is down 28.7 percent and Shanghai to Rotterdam is down 22.3 percent, after seven straight weekly declines on the Europe lanes. Asia-Europe rates are doing exactly what a lane does when effective capacity arrives before demand does.
The congestion data points the same way. Shanghai vessel waiting time rose from 65 hours in Week 36 to 78 hours in Week 37 as Golden Week cargo piled in, yet that has not lifted Europe-bound rates at all. When queues grow and prices fall on the same lane, the clearing factor is not demand. It is supply coming back online.
What it means for landed cost
For importers the practical read is that the two trades will not price the same in October. Transpacific spot at $7,838 to the West Coast and $10,373 to New York is a pre-holiday push, and Drewry expects rates to decrease next week as Golden Week factories shut from 1 to 7 October and the cargo behind the surge disappears. Asia-Europe is already through that turn: the rate is falling with every Suez transit added, and the post-holiday service restoration is expected to add around 27 percent capacity to the Europe trade once the holiday ends, per India Seatrade News. A European buyer negotiating a Q4 contract against the current Rotterdam print is negotiating against a rate with a falling floor, while a US buyer is still paying a capacity-scarcity premium that Shanghai to New York levels only sustain while blank sailings hold.
The next dated checkpoints are the Drewry WCI assessments on 1 and 8 October, the Golden Week shutdown itself from 1 to 7 October, and the post-holiday capacity restoration on Asia-Europe in mid-October. Watch whether Suez transits hold in the high 40s after the holiday. If they do, the Asia-Europe decline is structural rather than seasonal, and the 2027 supply wave BIMCO flagged on Tuesday arrives on a lane already pricing it in.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.