Golden Week Blank Sailings Hit 11% as Transpacific Spot Rates Top $10,000
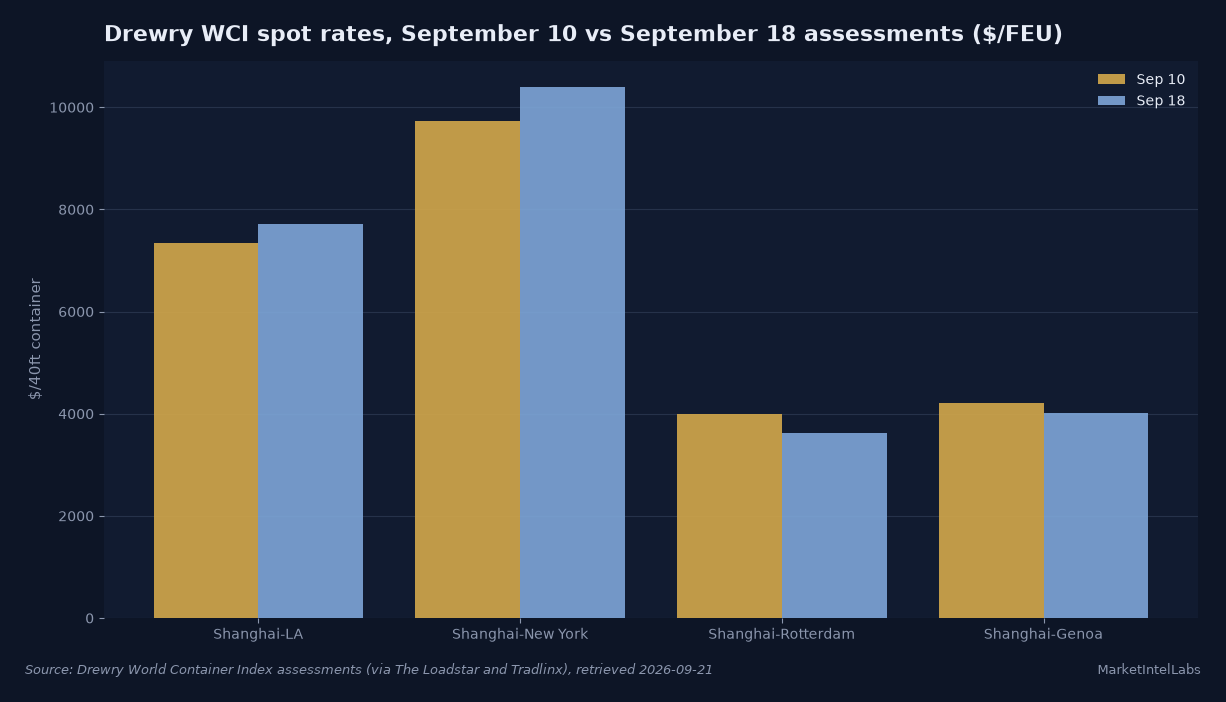
The week of September 14 delivered the sharpest split the container market has shown since the pandemic era. Drewry's World Container Index put the Shanghai to New York leg at $10,394 per 40ft container in its September 18 assessment, up 7% on the week and the first reading above $10,000 since mid-2022. The Shanghai to Los Angeles leg climbed 5% to $7,712. On the other side of the world, Shanghai to Rotterdam fell 9% to $3,626 and Shanghai to Genoa slipped 5% to $4,016.
The divergence has now run for seven straight weeks, and it is not one story but two. On the transpacific, capacity is getting scarcer. Chinese port congestion that peaked in early September is clearing, but the queue has moved to Southeast Asia: Linerlytica reports waiting times at Singapore above four days as vessels bunch. Carriers responded by pulling sailings. Drewry's Cancelled Sailings Tracker, dated September 11, counts 79 cancelled sailings out of 721 planned between September 14 and October 18, an 11% rate, up from 47 of 729, or 6%, the week before. Nine transpacific blank sailings are already announced for the coming week against eight this one.
The market has already priced much of this. ZIM trades at $30.10, within 1% of its 52-week high of $30.40 and up 144% over the past year. Matson sits at $232.92, up 168% over the year and close to its 52-week high of $240.87. The parcel carriers tell the domestic side of the goods economy: FedEx at $303.65, up 68% over 52 weeks, against UPS at $99.06, up 21%. Equities are not the thesis here, but the read-through is consistent: ocean carriers and time-definite logistics are being paid for tightness while the legacy parcel names reflect a slower US shipping market.
For context on the transpacific lane split, see our earlier coverage: Shanghai-New York Spot Near Record as Lanes Split, Transpacific Spot Rates Climb as Carriers Pull Capacity, and ISM Data Shows Costs Rising Even as Inventory Growth Slows.
What to watch next. Drewry's next WCI assessment lands Thursday, September 24, and the pre-Golden Week bump should show up in it; a flat or falling Shanghai-New York print would signal the peak is in. The ISM September manufacturing report arrives October 1, the same day the holiday starts, and the first post-Golden Week blank-sailing picture arrives in early October, when the true test is whether carriers keep capacity out of the water after the holiday or return it faster than demand warrants. The 11% cancellation rate for the next five weeks is the number that decides whether a shipper booking for mid-October pays $10,000 or watches rates unwind.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.