Energy Leads the Rotation: XLE +2.17% on Saudi Supply Shock

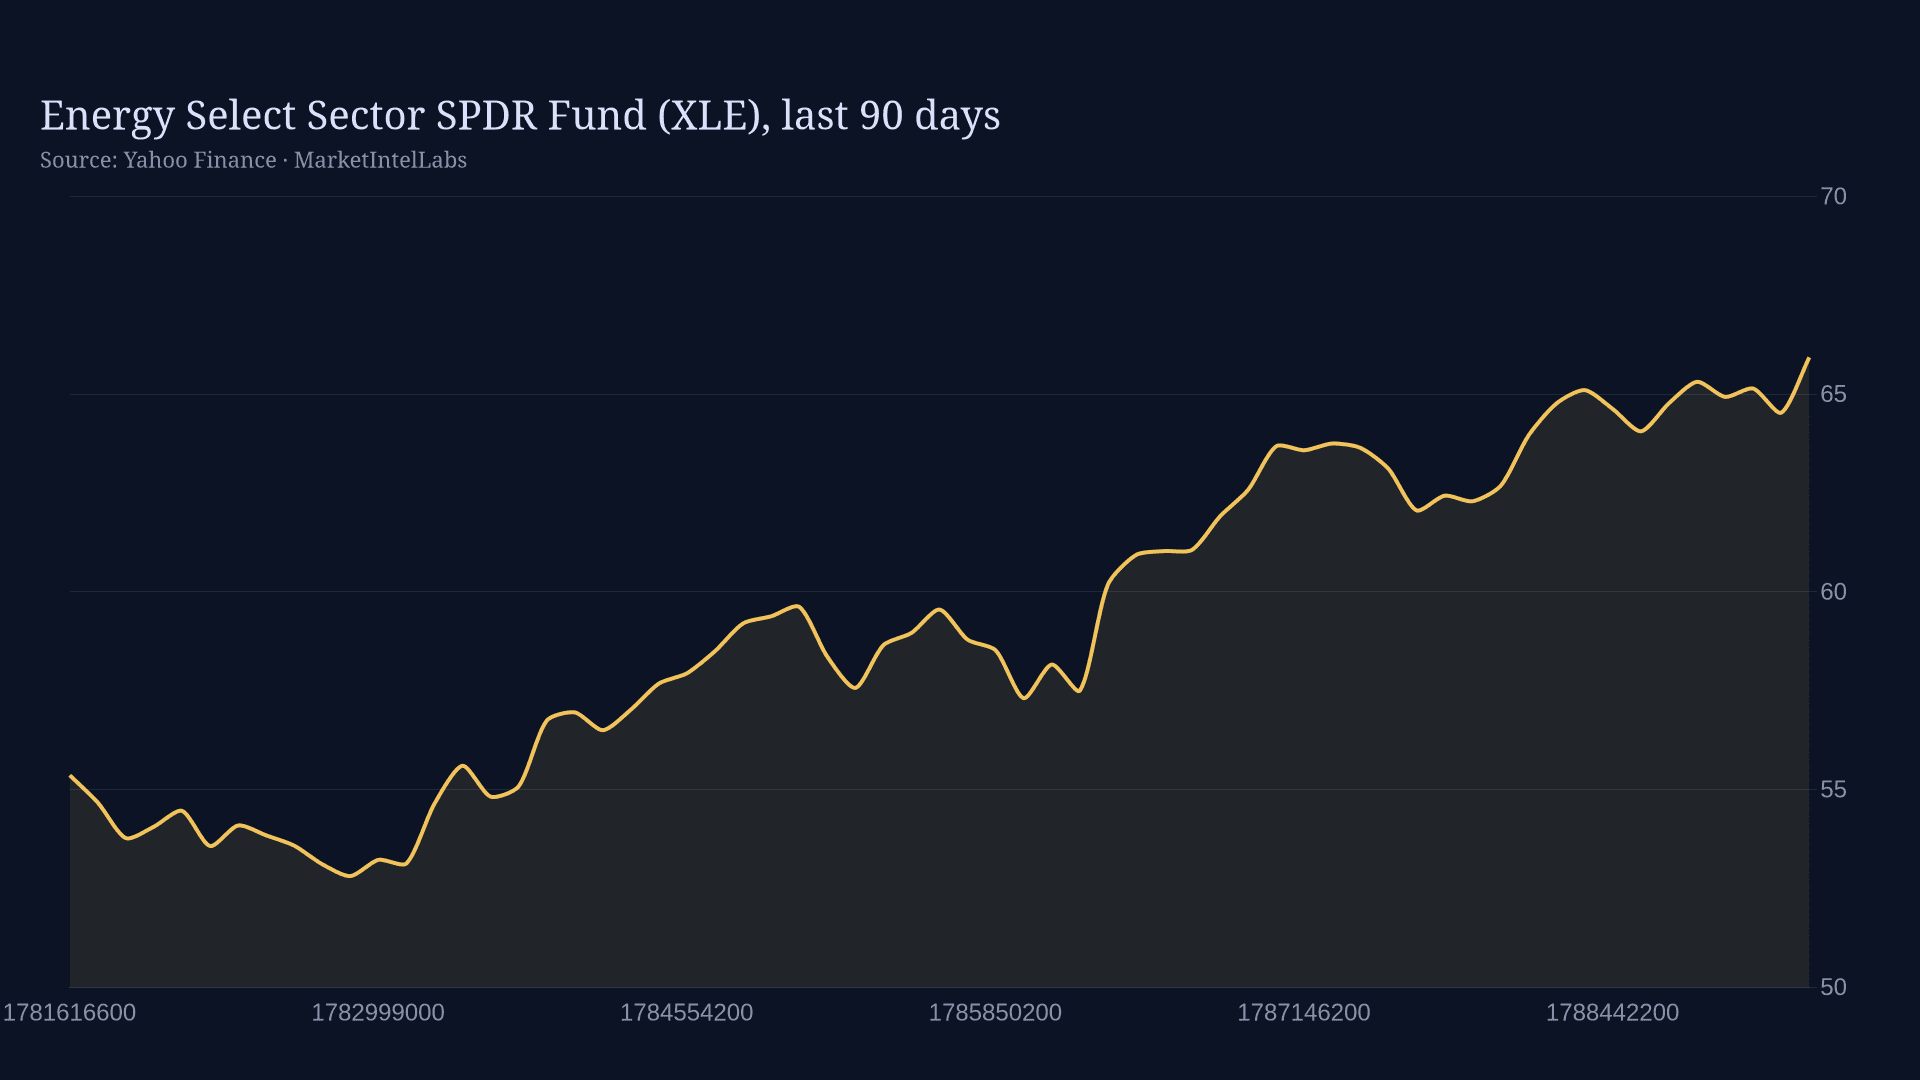
Energy is the day's standout, with the XLE energy fund up 2.17% to $65.93 even as the S&P 500 slips roughly half a percent ahead of this afternoon's FOMC decision. This is not a beta call. It is a sector rotation, and it is the clearest signal on today's tape that investors are positioning for a hawkish Fed and a supply-driven oil shock at the same time.
The catalyst is a supply shock, not a demand story. Saudi Arabia closed its East-West pipeline, with Riyadh blaming Iran-backed fighters in Iraq, and Houthi attacks have resumed in the Red Sea. That combination has WTI near $103 a barrel and Brent near $107, with up to 4% of global supply potentially at risk. For energy producers those are margin tailwinds, and the sector is pricing them in while the rest of the market wrestles with higher-for-longer rates. For more on the supply picture, see the premium the Crude Holds the Hormuz Premium as Saudi Pipeline Stays Shut: WTI Near $103 has held, plus our crude oil coverage.
The rate side is doing the opposite work. The 10-year Treasury yield sits at 5.00%, its highest since 2023, and the sectors most exposed to that reality are the session's casualties. Consumer discretionary is down 1.75% to $110.88, squeezed from both directions as high oil and high rates hit the consumer. Utilities are off 1.20% to $41.32, losing the income-sensitivity bid that usually supports them in downturns as fixed income becomes more competitive. The move is consistent with last week's 10-Year Yield Breaks 5% Into the FOMC: What's Priced and What Isn't. Financials are muted at -0.32%: higher yields help net interest margins, but a hawkish surprise would widen credit-stress concerns. Tech is softer at -0.29%, layered over an AI-safety sentiment overhang that has pressured mega-caps into the meeting. Only materials join the upside alongside energy, and modestly, at +0.48%.
Today's hike is heavily priced but not the real event. Interest-rate futures assign roughly 90% probability to a 25 basis point move to a 3.75%-4.00% target range, and a Reuters poll puts economist expectations near 85%. A hot August core CPI print, up 0.3% month over month against a 0.2% forecast, plus a blowout payroll report of +162k versus a +56k forecast, gave Chair Kevin Warsh room to tighten. The information that matters is in the dot plot and the 2:30pm press conference: whether this reads as a one-and-done insurance hike or the opening of a new sequence through year-end. The oil shock is the exogenous variable stacked against the Fed either way, since a disruption touching up to 4% of global supply makes it harder to credibly point back toward 2% inflation.
The contrarian risk is that consensus pricing cuts both ways. If Warsh strikes a more cautious tone than the market expects, it would reverse the yield spike and fuel a relief rally in tech, flipping today's rotation faster than most anticipate. Barring that, the defensive-to-energy rotation into this decision tells you where the market sees the path of least resistance. Watch SPY's $757.39 session support into the 2:00pm decision, and whether energy keeps its leadership once the dot plot lands. For the longer view, see Equities Sector Rotation: Opportunities and Risks.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.