Diesel Prices Near $6.18, Up 69% Year Over Year: What Freight Costs Next
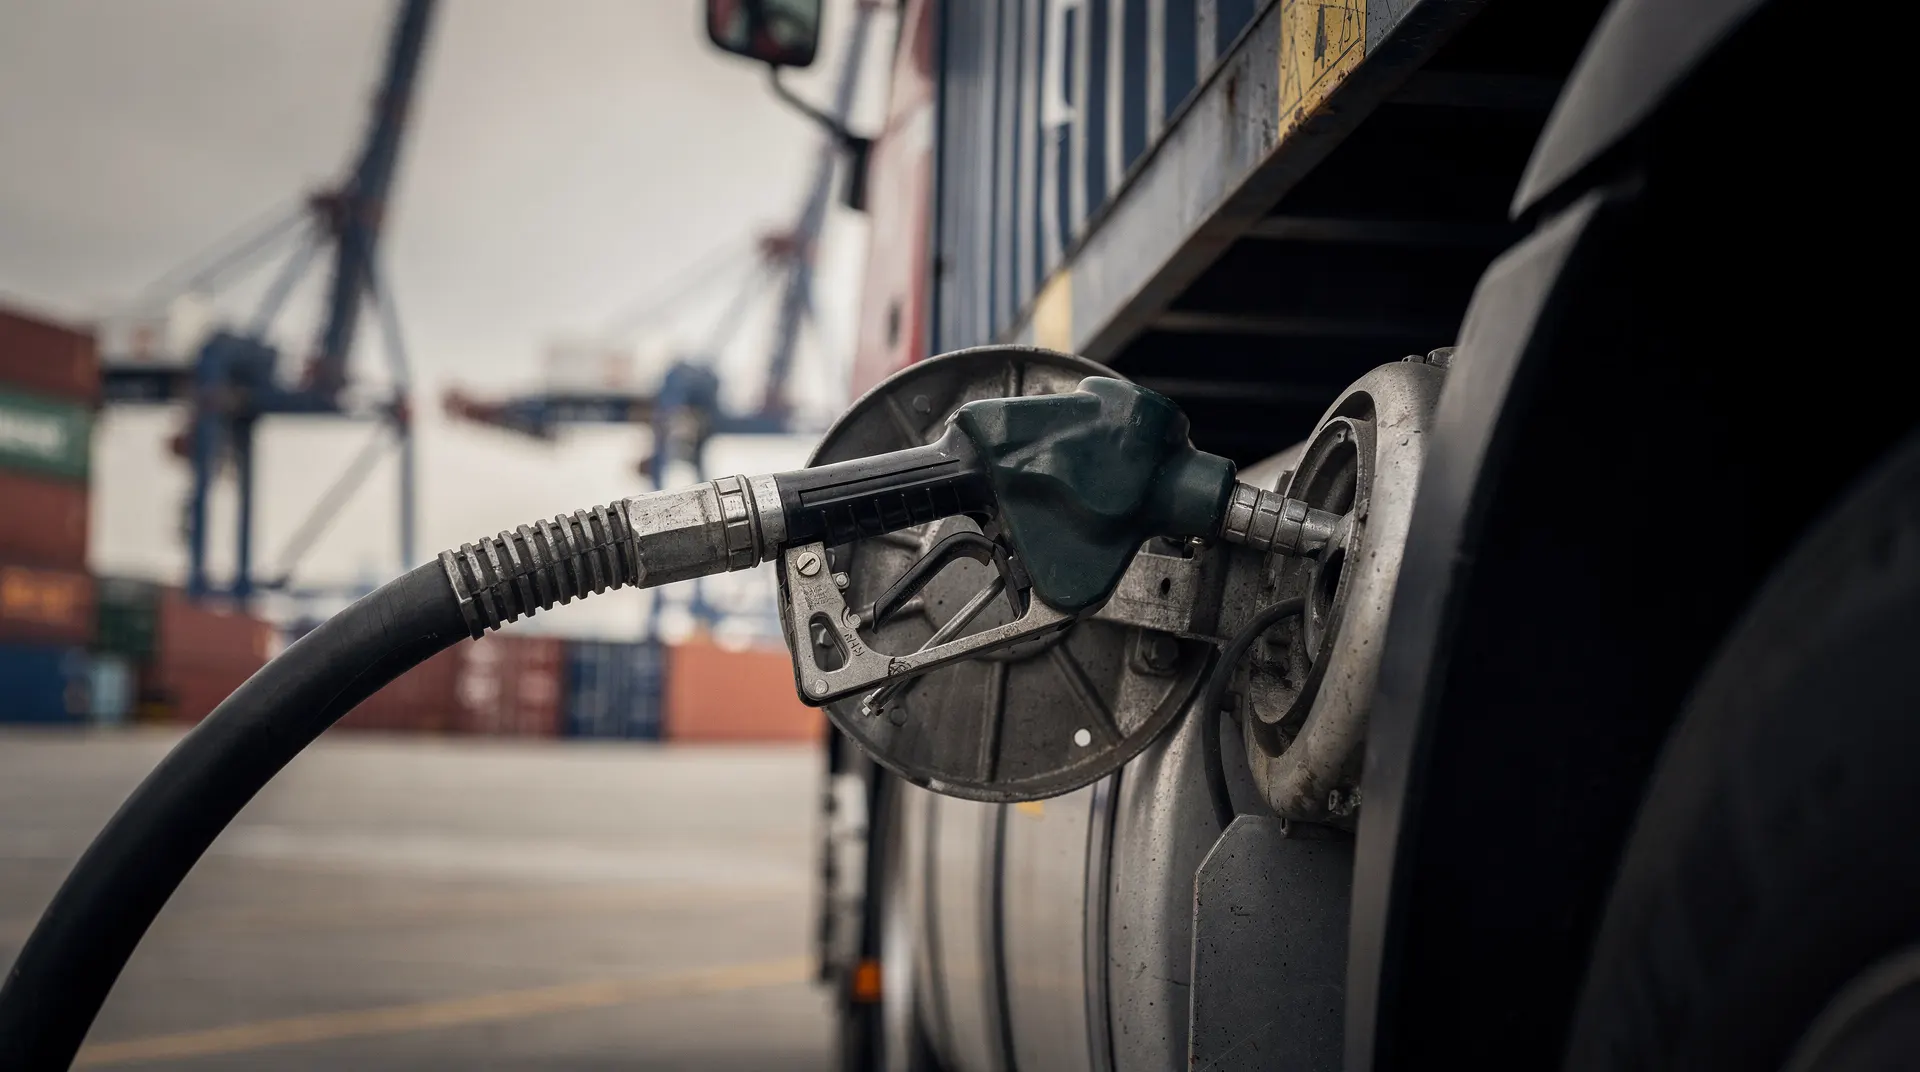
The week of October 19, the number that defines freight cost is the price of the fuel that moves it. On-highway diesel sat at $6.179 a gallon for the week ended October 12, up 68.6% from the $3.665 of a year earlier and still near levels not seen in years, even as it slipped from the $6.529 peak of late September. A gallon of diesel now carries roughly $2.50 more than it did a year ago, and that premium is working its way into every trucked shipment that lands on a U.S. dock or store shelf.
Diesel is the freight economy's rawest input. It prices the trucks that move roughly 60% of U.S. tonnage, and a fuel spike like this year's shows up twice: once in the rate a shipper pays, and again in the surcharge carriers layer on top. That double hit is why the fuel print, not just the container quote, is the freight number to watch this week.
Related reading: Diesel Falls to $6.20, Yet Freight Fuel Bills Remain High.
Diesel: off the peak, still far above last year
The EIA's weekly retail series tells a clear story. Diesel opened 2026 around $3.48 a gallon, roughly flat with the prior winter. Through late February it barely moved, then it broke higher in March and spent the summer climbing, topping out at $6.529 for the week ended September 21. The last three weekly prints have eased, to $6.382, $6.199 and $6.179, so the peak is likely behind us for now.
But easing off a peak and returning to normal are different things. Even after three down weeks, retail diesel sits 68.6% above the same week of 2025 and within about 5% of its late-September high. Compared with the $5.60 to $6.00 range of this summer, the pullback is modest. The fuel-cost headwind on truckload and less-than-truckload pricing is not going away anytime soon.
Related reading: Diesel Hits $6.29 a Gallon and the Truck Leg Now Sets Landed Cost.

Maersk's move captures the pass-through. The carrier raised its fuel surcharge on U.S. inland haulage by 54% earlier this month, an acknowledgment that the diesel bill on the last-mile truck leg has become a dominant line item. When the inland leg costs that much more, the quoted ocean rate understates what a shipment actually costs to land.
Container rates tell the second half of the freight story. Transpacific rates are still historically high but have begun to ease. SPOT Shanghai-to-Los Angeles moved up 3% in the latest Drewry read while Shanghai-to-New York slipped 1%, with West Coast bookings around $7,475 to $8,000 per FEU and East Coast around $9,600 to $11,000, near the strongest levels since mid-2022. Xeneta reports carriers blanked roughly 58,200 TEU on the Far East to U.S. West Coast trade this week and 35,500 TEU to the East Coast, a deliberate capacity pullback.
Related reading: Gas Prices Ease to $4.33 a Gallon as September Peak Fades.
The sequencing matters. Carriers are cutting sailings into what has been an unusually strong fall, an overt signal they do not expect the current rate level to hold. The National Retail Federation projects November arrivals to fall 11% month over month, and with Golden Week traffic behind us, the freight press is framing this as the start of a downward drift rather than a capex-driven pullback. Rates staying near multi-year highs while carriers trim capacity is a temporary equilibrium, not a settled one.
The survey side agrees with the cost story. ISM Manufacturing PMI for September came in at 54.5, barely off August's 54.6 and in expansion for the ninth straight month. The headline looks healthy, but the sub-indices tell the real story. The Prices Paid index jumped 6.8 points to 77.9, its sharpest climb in months, while supplier deliveries slowed for a tenth consecutive month at a reading of 59.0, meaning longer lead times at the worst possible moment for cost.
Related reading: Transpacific Container Rates Near Annual High at $7,884.
Survey panelists were unambiguous about the driver. In the September responses, 34% of negative comments cited tariffs and 46% flagged pricing volatility, with rising lead times at 21%. New orders expanded to 55.3 and employment to 52.7, so demand is not the constraint. The constraint is cost: raw materials, fuel and the delays that push everything through a more expensive pipeline.
Three dated prints land this week before the next Monday read. The October ISM Manufacturing PMI releases November 2. Census posts manufacturers' inventories and the advance trade balance in the week of October 27. And the Baltic Dry Index, at 2,545 on October 15 after an eight-day slide, continues to track the dry-bulk leg.
The freight story this week is not a container-rate story, and it is not a port-congestion story. It is a fuel-cost story with a sticker price of $6.18 a gallon on the pump, up 68.6% year over year, feeding into every surcharge and every landed-cost number a retailer or manufacturer runs this quarter. Until diesel digests its run-up, the fuel line stays the most expensive part of getting goods to a U.S. buyer.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.