Volatility Compresses as VIX Falls to 14.51 and Options Traders Turn Bullish

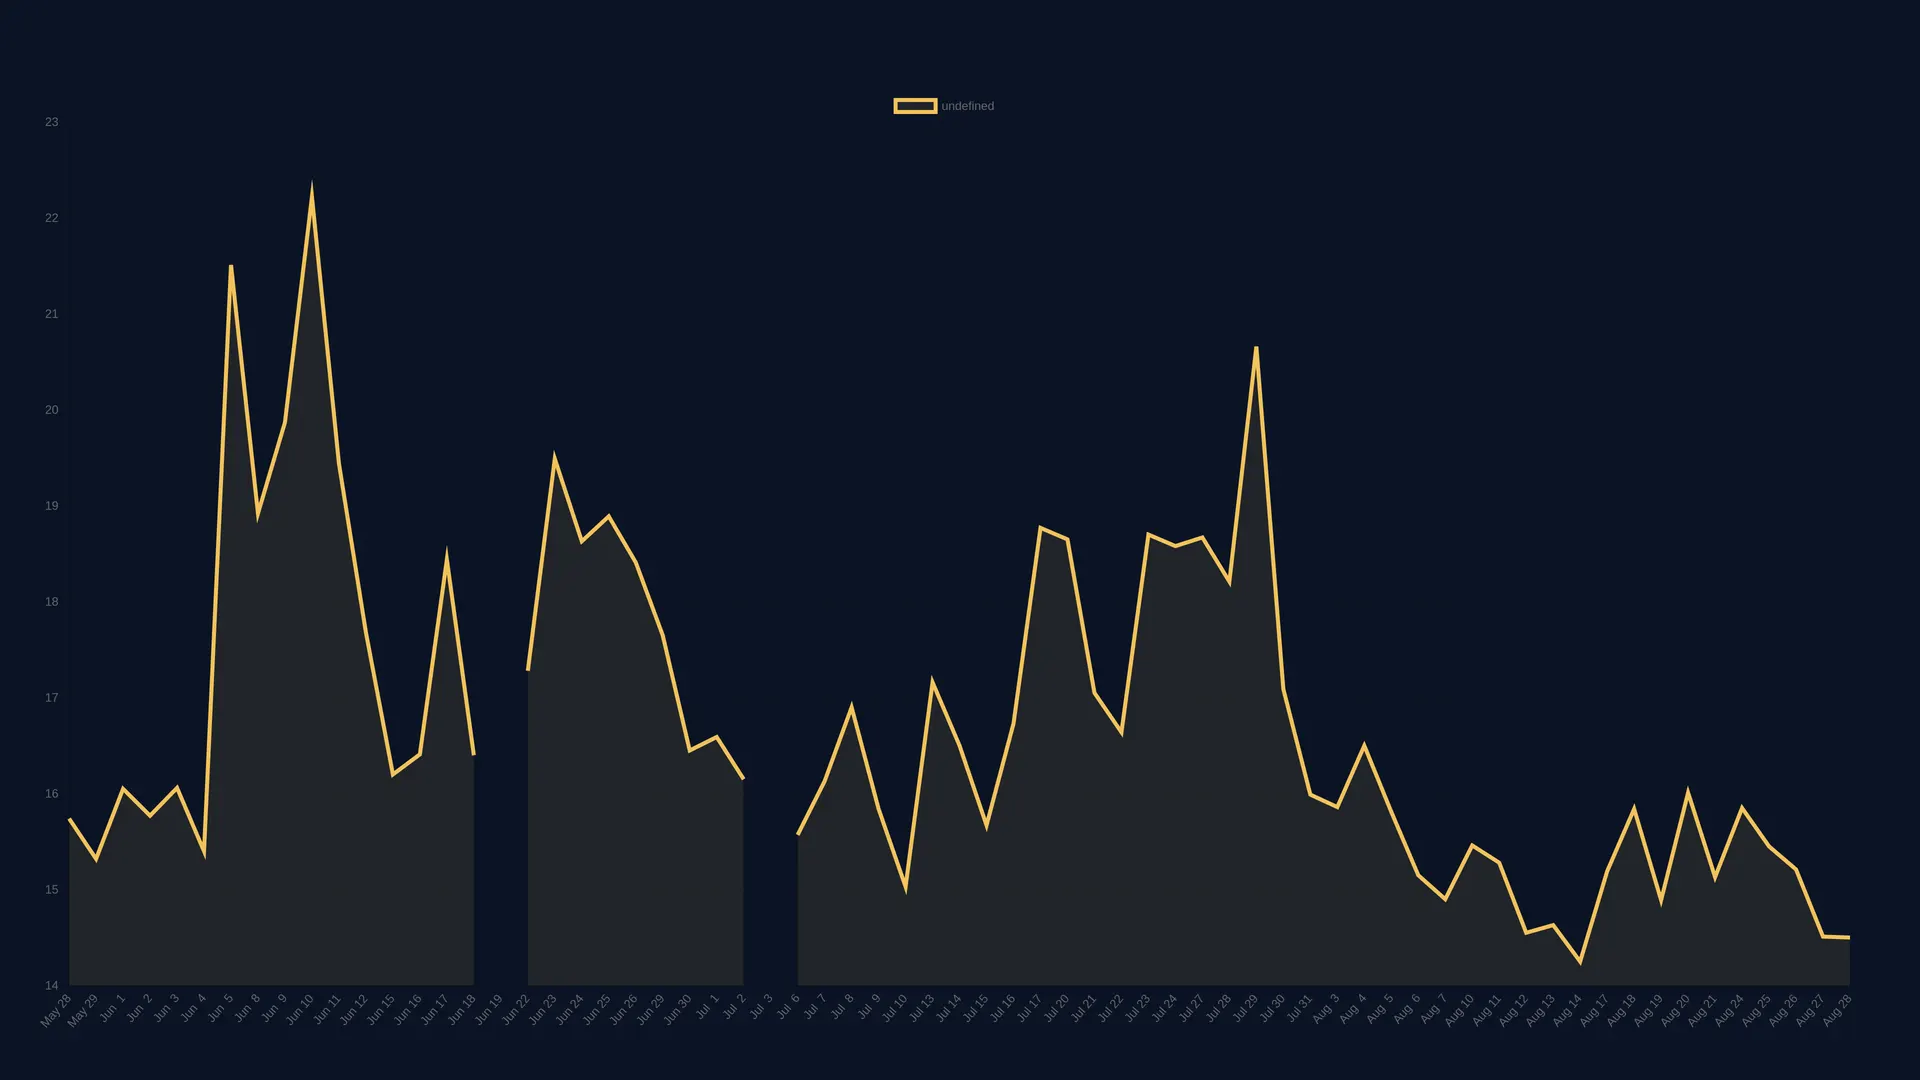
Market volatility compressed sharply on Friday as traders shed hedging positions. The CBOE Volatility Index dropped 4.60% to 14.51, well below its long-term average near 20.
The CBOE Total Put/Call Ratio followed suit, falling to 0.73. That reading signals a clear shift toward call-side positioning and reduced demand for downside protection.
Key Takeaways
VIX fell 4.60% to 14.51, indicating reduced near-term hedging demand CBOE Total Put/Call Ratio dropped to 0.73, a bullish zone below 0.85 10-year Treasury yield rose 0.17% to 4.67%, reflecting modest reflation expectations Compressed volatility leaves markets vulnerable to surprise shocks The combination of a falling VIX and low put/call ratio…
Keep reading with a free account
Get tomorrow's institutional market briefing before markets open, produced by specialized AI analysts researching markets 24/7. Takes under a minute, no card required.
- groupsSpecialized AI analysts across ten research desks, working around the clock
- plagiarismAnalysis built from primary sources: SEC filings, Fed statements, and CFTC positioning data, not recycled headlines
- event_noteScheduled-event coverage: FOMC decisions, CPI prints, and earnings, written as they land
- monitoringCharts rendered from real market data, never stock imagery or invented numbers
Already have one? Log in · Want everything the day it publishes? Go Premium
Secure checkout via Stripe