S&P 500 sector rotation picks energy and defensives as tech and small caps lag

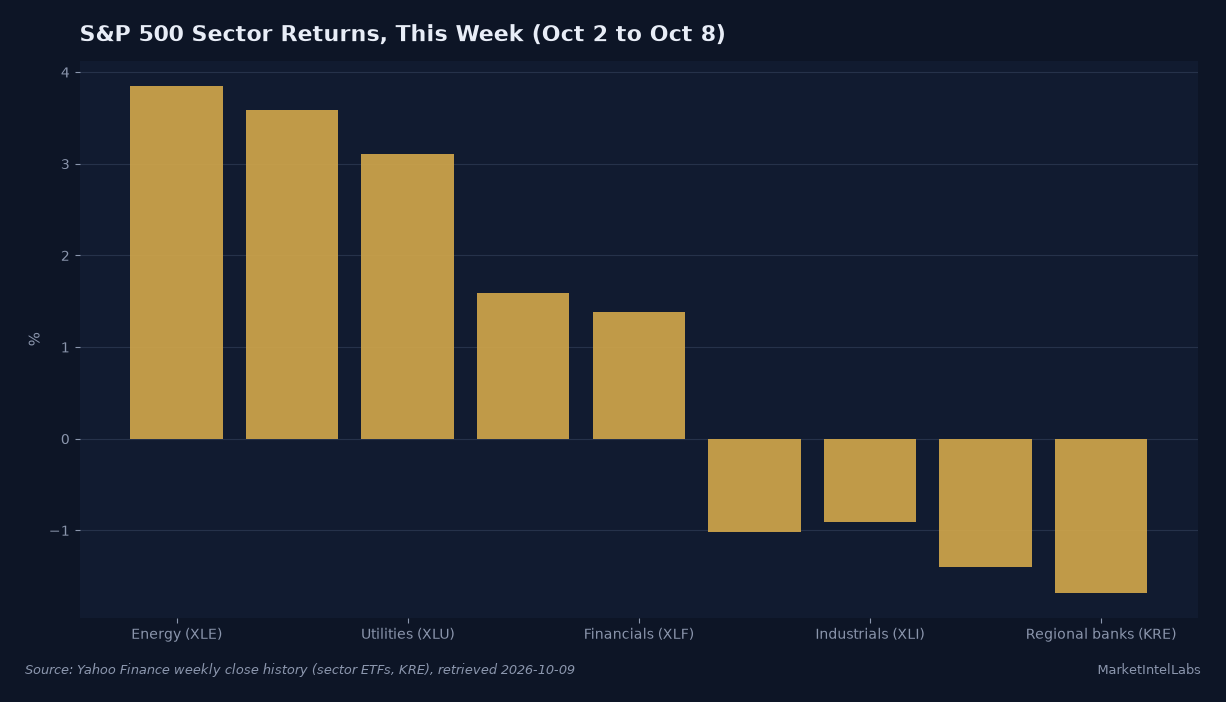
The S&P 500 set a record on Tuesday and is trading near it this week, but the tape underneath told a two-speed story so far in October. Energy, consumer staples and utilities led every sector while technology and small caps lagged, the cleanest rotation signal in weeks and a direct read on what a roughly 5.3% 10-year Treasury is doing to positioning.
A fresh record capped the recent open: SPY closed at $779.09 on Tuesday, Oct 6, after an intraday record of $781.62, then slipped to $773.93 by Thursday while the S&P 500 index settled at 7,765.36, down 0.47% (Swingfolio). That pullback was the interesting part: Thursday's drop was concentrated almost entirely in AI and chip names after the Financial Times reported OpenAI's annualized revenue near $50 billion, about $20 billion below earlier figures (Financial Times). The average stock moved the other way that session: the equal-weight index was 0.67% higher and 332 of 489 S&P 500 members traded in the green (What Moved the Market Today).
Related reading: Utilities lead rotation as the S&P caps at 7,670 into quarter-end.
The rotation, not the record, is the story that matters for the weeks ahead. Energy (XLE) surged 3.85% on an oil spike to roughly $104 a barrel as Iranian tanker attacks and Hurricane Isaias shut-ins tightened supply. Staples (XLP) gained 3.59% and utilities (XLU) 3.11% as low-duration income, the classic refuge when the 10-year sits at levels last seen in 2002: the yield touched a 24-year high near 5.35% intraday Monday and closed the week around 5.28% (Yahoo Finance, CNBC).
On the other side of the ledger, tech (XLK) fell 1.02% and industrials (XLI) 0.91%, the late-cycle rate victims. Small caps (IWM) dropped 1.40%, and regional banks (KRE) fell 1.68%, the most rate-sensitive exposures in a 5.3% yield regime. Breadth told the same capped story: 28% of stocks sit above their 50-day average, and Thursday brought 1,239 new 52-week lows against 459 new highs (StockSetups).
For the broader framework, see our crude oil coverage.
Related reading: Sector Rotation Signals: Tech and Industrials Lead as Market Breadth Narrows.
The next catalyst lands Tuesday, Oct 13, when JPMorgan, Goldman Sachs, Wells Fargo and Citigroup open bank earnings season. Higher rates create a net-interest-income tailwind for the big lenders, and financials (XLF) held up 1.38% this week on exactly that expectation. The fault line to watch is regional credit, because KRE sold off even as the sector held up, and a hot September CPI report around Oct 14 would push the 10-year back through 5.35% and reopen the small-cap, regional-bank pressure points (riskstock, Yahoo Finance).
For now the tape is healthy underneath the record: the index pulled back on a sector-specific story, and breadth improved the very day the cap-weighted average fell. A rotation into defensives and energy at the expense of tech and small caps is a signal the market is adjusting to a higher-for-longer rate path, and bank earnings will show whether the rate tail outweighs the credit risk that has been quietly building in the regionals.
Related reading: S&P 500 record 7,818.95 on a 5.3% long yield: big caps climb while small caps and semis lag.
Related reading: Small Cap Slump Signals Risk-Off Rotation Amid Rising Yields.
This content is for informational purposes only and does not constitute financial advice. Past performance is not indicative of future results. Consult a qualified financial advisor before making investment decisions.
Get daily intelligence delivered
Create a free account for the Daily Brief every weekday and The Week Ahead every Sunday. No card required.